What Are the Real Problems Facing Over 55s in the UK by 2027?
The real problems facing over 55s in the UK by 2027 are a pensions adequacy crisis affecting 15 million people, a state pension age rising to 67, adult social care costs pushing families toward financial ruin, digital exclusion affecting 2.4 million older people, and a loneliness epidemic set to hit two million over-50s. These are the problems everyone knows about. And they are the hardest to solve. CheeringupInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in UK have now and in near future.
I’m not here to sell you a fantasy. I’m here to look at what’s actually coming — and what we can actually do about it. Because the things we know for sure are problems are often the most difficult to solve. But difficult doesn’t mean impossible. It means we need to think differently.
The UK population is projected to reach 70 million by 2027, with the average age rising steadily. By 2037, 13% of the population will be aged 75 and over, compared to just 8% in 2012. This isn’t a distant problem. It’s here.
Let me walk you through the hardest problems — the ones we all know about — and then give you 12 realistic, lateral solutions that could change everything.
How Will the Rising State Pension Age Affect Over 55s in 2027?
The rising state pension age will affect over 55s in 2027 by pushing the pension age to 67 by early 2028, forcing millions to work longer or bridge a gap of up to 11 months without state support. Anyone who turns 66 before March 6, 2027 will see their retirement age increase by up to 11 months. The state pension age is currently 66 and will gradually rise to 67 between 2026 and 2028.
The Institute for Fiscal Studies has calculated this represents a £4,000 blow to workers. That’s not a rounding error. That’s a holiday, a home repair, six months of energy bills.
- State pension age rises from 66 to 67 by early 2028
- Full State Pension is worth just under £12,000 per year
- A moderate retirement lifestyle for a single person requires around £32,000 per year
- For a couple, that figure rises to £44,000
- The gap between State Pension and a moderate lifestyle is approximately £20,000 to £32,000 per year
The maths doesn’t work for most people. It never did.
Why Is the UK Retirement Savings Gap Getting Worse in 2027?
The UK retirement savings gap is getting worse in 2027 because 15 million working-age people are under saving for retirement, and the final Pensions Commission report expected in spring 2027 is set to confirm a pensions adequacy disaster. The Commission estimates that approximately 15 million people — around 43% of the UK’s working age population — are currently undersaving.
Someone retiring in 2050 is set to have 8% (£800 per year) lower private pension income compared to a retiree in 2025. The gender pensions gap in private pension wealth between males and females aged 55-59 is 48%.
This isn’t a future problem. It’s a now problem wearing a future costume.
- Only around a third of individuals are on track to achieve adequate retirement income
- Roughly 36% are not expected to have enough to meet their needs
- Middle earners, the self-employed, and women are hit hardest
- The Pensions and Lifetime Savings Association estimates a single person needs £32,000 a year for a moderate retirement
- The full State Pension is just under £12,000
The gap is £20,000 a year. For 20 years of retirement. That’s £400,000.
Why Are Adult Social Care Costs a Ticking Time Bomb for Over 55s?
Adult social care costs are a ticking time bomb for over 55s because frozen means-test thresholds have forced some care users to spend an additional £12,400 of their own money before qualifying for state support, with the Department of Health and Social Care estimating reform costs of £3.7 billion in 2027-28 alone. The social care support threshold has been frozen since 2010/11.
- A social care support threshold freeze since 2010/11 means some people must spend an additional £12,400 before qualifying for state support
- If the threshold had been uprated in line with inflation, it would have been over £35,600 in 2026/27
- The DHSC estimates the cost of charging reform at £3.7 billion in 2027 to 2028
- The Personal Expenses Allowance increases from £30.65 to just £31.80 per week in 2026-27
That’s £31.80 a week to live on after care costs. Not per day. Per week.
How Widespread Is Digital Exclusion Among Over 55s in the UK?
Digital exclusion among over 55s in the UK is widespread, with 2.4 million older people — nearly one in five — having limited use of the internet, going online less than once a month or not at all. Age UK’s analysis found that 19% of older people are digitally excluded, and 33% (4.3 million) don’t use a smartphone.
As government services, banking, health appointments, and even social connections move online, this isn’t a minor inconvenience. It’s a structural lockout.
- 2.4 million older people have limited internet use (19%)
- 4.3 million older people don’t use a smartphone
- 6 million (12%) older people do not use a mobile phone at all
- Three-quarters of supporters (76%) say the main person they support is over 55
- A lack of digital skills is higher among people receiving support over the age of 55 (60%)
The system is being rebuilt for digital-first. And millions are being left outside the door.
Why Is Loneliness Among Over 55s Set to Reach Crisis Levels?
Loneliness among over 55s is set to reach crisis levels because the number of over-50s experiencing loneliness is set to reach two million by 2025/26 — a 49% increase in just ten years. Nearly a quarter (22%) of adults aged 55 and over most fear loneliness and disconnection in later life.
- Half a million older people in the UK go at least five or six days a week without speaking to anyone at all
- Men aged 55-64 are the most adversely affected, with 15% reporting they have no close friends
- Up to 18% of UK adults feel lonely “always or often”
- Loneliness is linked with early mortality, poor physical health, mental ill-health, and cognitive decline
Loneliness isn’t a soft issue. It’s a health issue. It kills.
Why Is Downsizing Not Working for Over 55s in the UK?
Downsizing is not working for over 55s in the UK because only 19% plan to downsize in retirement, with 21% saying it’s too expensive to move and a further 8% citing stamp duty as a barrier. The shortage of specialist housing for people in later life has denied many the option of rightsizing from unsuitable properties into smaller, purpose-built homes.
- Only 19% of older homeowners plan to downsize
- 21% say it’s too expensive to move
- 8% cite stamp duty as a factor
- There is a need for 30,000 specialist homes per year compared to current output of 5,000-7,000
- More than a third of older homeowners struggle to find the right property, particularly bungalows or single-level homes
The family home becomes a trap. Too big to manage, too expensive to leave.
How Will Inheritance Tax Changes in April 2027 Affect Over 55s?
Inheritance tax changes in April 2027 will affect over 55s by bringing pensions into people’s estates for inheritance tax purposes for the first time, bringing many more estates into the taxpaying net. The inclusion of pensions in people’s estates for inheritance tax purposes from April 2027 will prompt people to look at ways to reduce the size of their overall estate.
This is a fundamental shift. Pensions were previously outside the IHT net. From April 2027, they’re in.
- Pensions included in estates for IHT from April 2027
- Many more estates will be brought into the taxpaying net
- The Pensions Commission final report expected spring 2027
- Automatic enrolment has created 11 million more pension savers than in 2012, but adequacy remains the problem
Why Are Over 55s Facing a Health and NHS Waiting List Crisis?
Over 55s are facing a health and NHS waiting list crisis because as of June 2025, 58,730 people aged 65+ were waiting for longer than 52 weeks, and over-55s are prepared to wait nearly four months for non-urgent treatment. As of June 2025, 63% of people aged 65+ were referred for third consultant-led treatment within 18 weeks.
- of 6.25 million people waiting for elective care on people 7.43 million pathways as at January 2025
- 56% of the overall waiting list is people aged 19-64
- A on wait lists are aged 65 and over
- The largest specialty for those aged 65+ is ophthalmology (14% of over 65s)
Waiting is not neutral. Waiting is deterioration.
Why Is Age Discrimination Still Blocking Over 55s from Work?
Age discrimination is still blocking over 55s from work because 78% of older workers say they’ve experienced age discrimination, and 45% of over-55s who lose their job are still searching after six months. The average age someone becomes undesirable to recruiters is 55, according to a poll of 4,000 UK adults.
- 78% of older workers say they’ve experienced age discrimination
- 45% of over-55s who lose their job are still searching after six months
- 69% of UK adults aged 50 to 66 felt older age was a disadvantage in the job market
- Only 11% thought being over 50 was an advantage
- In 2025, people in the 50-plus age group were the most likely to be made redundant in the UK
You’re not too old. The system is too rigid.
Why Are Over 55s Struggling with the Cost of Living?
Over 55s are struggling with the cost of living because 1.9 million pensioners are living in poverty — around one in six — and more than 3.7 million homeowners aged 55 to 79 do not have enough income to reach a moderate standard of living in retirement. One in 3 (34%) older people said they felt less financially secure heading into 2025 compared to when 2024 began — equivalent to 4.1 million people.
- 1.9 million pensioners living in poverty (16%)
- 3.7 million homeowners aged 55-79 without enough income for a moderate retirement
- 34% of older people felt less financially secure heading into 2025
- 45% of older people in a household with income less than £20,000 struggled with essentials
What Are 12 Innovative Solutions to Solve the Hardest Problems for Over 55s in 2027?
The 12 innovative solutions to solve the hardest problems for over 55s in 2027 are: pension bridging strategies, collective defined contribution schemes, home equity release innovations, digital skills peer networks, community-based co-living models, phased retirement pathways, preventive health investment, portable benefit platforms, micro-entrepreneurship hubs, care cost pooling, loneliness intervention technology, and intergenerational skills exchange. These aren’t theoretical. They’re being developed now.
- Pension Bridging Strategies
Pension bridging strategies solve the retirement income gap by using ISA savings, part-time work, and deferred State Pension to create a bridge between age 55 and State Pension age. With the State Pension age rising to 67, millions face a gap. By drawing from ISAs first and deferring State Pension, you can increase your eventual pension by up to 5.8% per year of deferral. The Pensions Commission’s final report in 2027 is expected to recommend new default decumulation pathways.
- Collective Defined Contribution (CDC) Schemes
Collective Defined Contribution schemes solve pension adequacy by pooling risk across members to provide better retirement outcomes than individual DC pots. The UK regulatory framework for Retirement CDC is expected in 2027, with master trusts preparing to launch solutions. LifeSight is the first master trust to confirm it will launch an R-CDC solution as soon as the framework allows. This isn’t a fringe idea. It’s coming.
- Home Equity Release Innovations
Home equity release innovations solve the downsizing trap by allowing over 55s to access property wealth without moving. With only 19% of older homeowners planning to downsize and 21% saying it’s too expensive to move, equity release becomes a practical alternative. New products are emerging that allow you to stay in your home while unlocking capital. The key is understanding the costs and ensuring it’s right for your circumstances.
- Digital Skills Peer Networks
Digital skills peer networks solve digital exclusion by having over 55s teach other over 55s, creating trust and reducing the intimidation factor. With 2.4 million older people digitally excluded, the traditional approach of younger people teaching older people isn’t working fast enough. Peer-to-peer learning removes the fear of looking stupid. It removes the power imbalance. It works.
- Community-Based Co-Living Models
Community-based co-living models solve loneliness and housing costs by creating shared living arrangements for over 55s that combine independence with connection. Half a million older people go at least five or six days a week without speaking to anyone at all. Co-living — where residents have private spaces but share kitchens, gardens, and social areas — addresses both loneliness and the cost of maintaining a large family home.
- Phased Retirement Pathways
Phased retirement pathways solve the cliff-edge retirement problem by allowing workers to gradually reduce hours while mentoring younger staff and maintaining income. With 78% of older workers reporting age discrimination and 90% of workers over 50 saying they’d like to stay in the workforce, the system needs to change. Phased retirement keeps skills in the economy, keeps income flowing, and keeps purpose alive.
- Preventive Health Investment
Preventive health investment solves the NHS waiting list crisis by reducing demand through proactive health management before problems become acute. With 58,730 people aged 65+ waiting longer than 52 weeks for treatment, prevention is the only scalable solution. This means structured exercise, nutrition, sleep optimisation, and mental health support — not as luxuries, but as core retirement infrastructure.
- Portable Benefit Platforms
Portable benefit platforms solve the fragmented support problem by allowing over 55s to access all available benefits, discounts, and entitlements in one place. With 1.9 million pensioners in poverty, millions are not claiming what they’re entitled to. A single platform that identifies Pension Credit, Attendance Allowance, Council Tax reductions, and energy discounts could put thousands back in people’s pockets.
- Micro-Entrepreneurship Hubs
Micro-entrepreneurship hubs solve income adequacy by helping over 55s turn skills and experience into small businesses with low overheads and high autonomy. With 3.7 million homeowners aged 55-79 unable to reach a moderate retirement standard, traditional employment isn’t the only answer. Consulting, freelancing, tutoring, and craft businesses can generate income while providing purpose and flexibility.
- Care Cost Pooling
Care cost pooling solves the catastrophic risk of social care costs by spreading the financial burden across a wider group, similar to insurance principles. With the social care threshold frozen since 2010/11 and care users forced to spend an additional £12,400 before qualifying for state support, individual risk is unsustainable. Pooling mechanisms — whether through insurance products or community schemes — can protect individuals from ruin.
- Loneliness Intervention Technology
Loneliness intervention technology solves isolation by using simple, accessible tools to connect over 55s with local activities, interest groups, and companions. The number of over-50s experiencing loneliness is set to reach two million by 2025/26. But the solution isn’t more apps. It’s using technology to facilitate real-world connection — walking groups, coffee mornings, skill-sharing sessions.
- Intergenerational Skills Exchange
Intergenerational skills exchange solves both loneliness and digital exclusion by creating structured programmes where over 55s share life skills and younger people share digital skills. Three-quarters of digital supporters say the main person they support is over 55. But what if the exchange went both ways? What if over 55s taught budgeting, cooking, gardening, and resilience, while younger people taught smartphone skills, online banking, and video calling?
What Does the Future of Retirement Look Like Beyond 2027?
The future of retirement beyond 2027 looks like a shift from a cliff-edge model to a fluid, phased, and self-directed approach where work, learning, health, and community are continuous rather than sequential. The Pensions Commission’s final report in spring 2027 will make recommendations for future pension policy. The regulatory framework for Retirement CDC will be published, with schemes rolled out in 2027/28. Inheritance tax treatment of pensions changes in April 2027.
The old model — work 40 years, retire at 65, live on a pension — is dead. It died when the State Pension age started rising, when final salary schemes closed, when the cost of living outstripped pension increases.
The new model is being built now. By people who refuse to accept that the only options are struggle or surrender.
- Phased retirement becomes normal, not exceptional
- Collective pension schemes provide better outcomes than individual pots
- Home equity becomes a legitimate retirement income source
- Digital inclusion becomes a basic right, not a luxury
- Community becomes infrastructure, not afterthought
What Is CheeringUpInfo Retirement Club Exploring?
CheeringUpInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in UK have now and in near future. The club is focused on improving retirement lifestyles in the UK by connecting like-minded people, sharing practical solutions, and challenging the conventional wisdom that says retirement means decline.
The club operates outside standard structures. It attracts people who want pure abundance — in health, in wealth, in connection, in purpose. People who are driven by personal freedom and radical autonomy. People who refuse to accept that the best years are behind them.
The problems are real. The stats don’t lie. But the solutions exist. And the first step is refusing to accept that the problems are unsolvable.
The hardest problems are the ones everyone knows about. The ones we’ve been told are too difficult. The ones that require thinking differently.
That’s where the innovation happens. That’s where the future gets built.
#Over55sUK #RetirementSolutions2027 #RetirementClub #RetirementMagazine #RetirementTV
Get help to protect and grow your business faster with CheeringupInfo by offering amazing deals at still profitable prices to over 55s in the UK
Find out more about targeted advertising and marketing to over 55s in UK
Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips
Connect with CheeringUpInfo for free retirement lifestyle improvement tips
Read more retirement lifestyle improvement articles and view videos for free
Retirement in the UK isn’t a reward. It’s a trap. And 15 million over 55s are walking into it with their eyes wide shut.
The 2027 Retirement Trap: 15 Million Undersaving, £20,000 Annual Gap, And The 12 Solutions Nobody Talks About
- The State Pension is just under £12,000 a year.
- A moderate retirement lifestyle costs £32,000 a year.
- That’s a £20,000 hole. Every single year. For 20 years. That’s £400,000.
- Do the math. Most people can’t.
But here’s what’s really disturbing…
- 1.9 million pensioners are already living in poverty — that’s one in six.
- 2.4 million over 55s are digitally excluded — locked out of banking, appointments, even social connection.
- 500,000 older people go five or six days a week without speaking to anyone at all.
- 78% of older workers say they’ve faced age discrimination.
- And from April 2027, your pension is included in your estate for inheritance tax. The government is coming for it either way.
And it gets worse.
The state pension age rises to 67 by early 2028. The social care means-test threshold has been frozen since 2010/11 — some care users now spend an additional £12,400 before getting state support. NHS waiting lists for over 65s hit 58,730 people waiting longer than 52 weeks.
Most people will read this and feel stuck. They’ll hope for the best. They’ll vote for someone who promises change. They’ll keep scrolling.
But a few will do something different.
They’ll look at the 12 solutions that actually exist: pension bridging, collective defined contribution schemes, home equity release, digital peer networks, co-living models, phased retirement, preventive health, portable benefit platforms, micro-entrepreneurship hubs, care cost pooling, loneliness intervention tech, and intergenerational skills exchange.
These aren’t fantasies. They’re being built right now. And they work.
Most people stop here. The ones who don’t are the ones who change their retirement.
Email editor@cheeringup.info with the subject line RETIREMENT CLUB for more information on Retirement Club.
CheeringUpInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in the UK have now and in the near future. You can too.
Featured Products For Over 55s
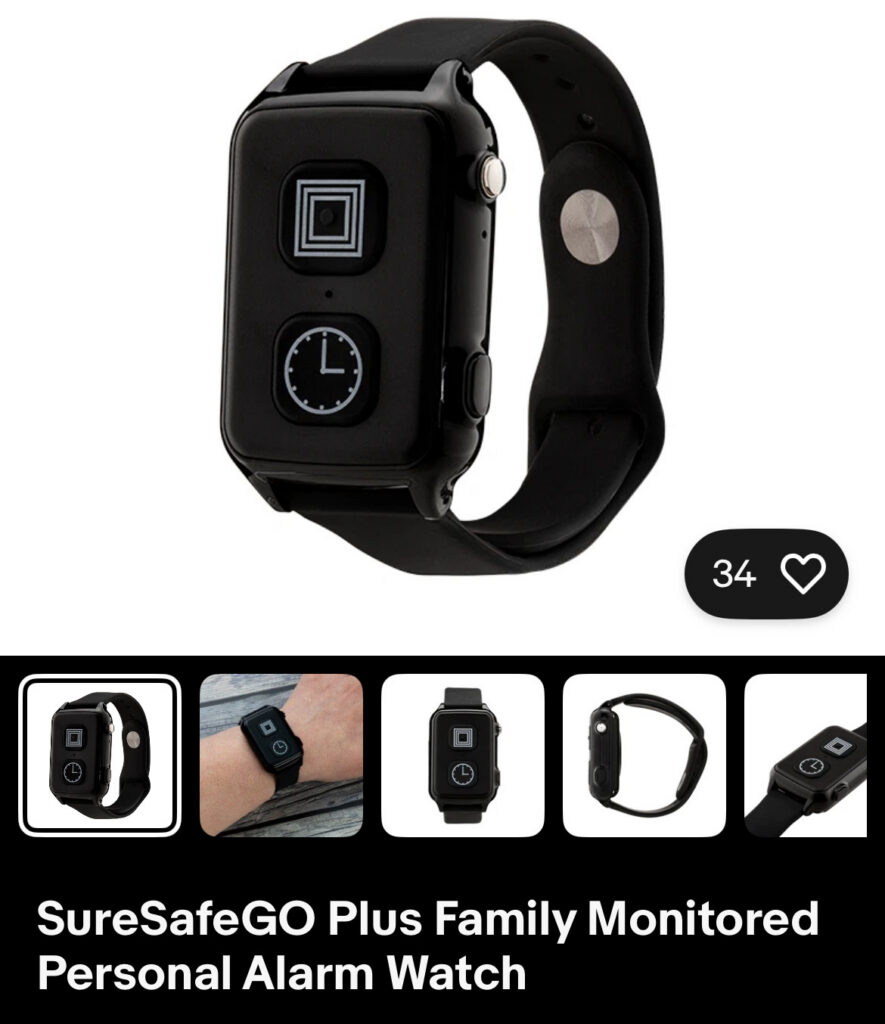
https://ebay.io/m/JXKOEN
As an eBay Partner, I may be compensated if you make a purchase
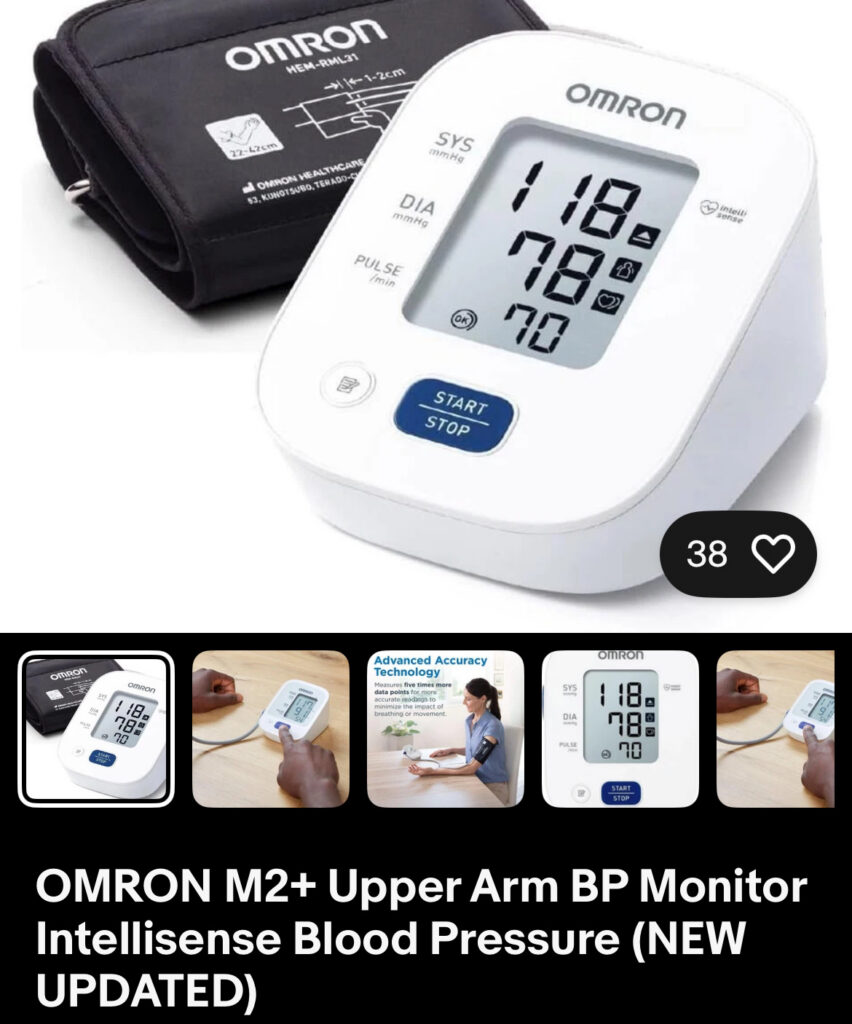
https://ebay.io/m/Yx0pX5
As an eBay Partner, I may be compensated if you make a purchase
https://ebay.io/m/9GU7Q3
As an eBay Partner, I may be compensated if you make a purchase
What Are the 2027 Problems for Over 55s UK? 12 Solutions