Over 55s UK 2027 Problems: 12 Solutions | CheeringUp.info

12 practical solutions to 2027 problems for over 55s UK — pensions, care, loneliness, digital exclusion. CheeringUpInfo Retirement Club explores.

What Are the Real Problems Facing Over 55s in the UK by 2027?

The real problems facing over 55s in the UK by 2027 are a pensions adequacy crisis affecting 15 million people, a state pension age rising to 67, adult social care costs pushing families toward financial ruin, digital exclusion affecting 2.4 million older people, and a loneliness epidemic set to hit two million over-50s. These are the problems everyone knows about. And they are the hardest to solve. CheeringupInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in UK have now and in near future.

I’m not here to sell you a fantasy. I’m here to look at what’s actually coming — and what we can actually do about it. Because the things we know for sure are problems are often the most difficult to solve. But difficult doesn’t mean impossible. It means we need to think differently.

The UK population is projected to reach 70 million by 2027, with the average age rising steadily. By 2037, 13% of the population will be aged 75 and over, compared to just 8% in 2012. This isn’t a distant problem. It’s here.

Let me walk you through the hardest problems — the ones we all know about — and then give you 12 realistic, lateral solutions that could change everything.

How Will the Rising State Pension Age Affect Over 55s in 2027?

The rising state pension age will affect over 55s in 2027 by pushing the pension age to 67 by early 2028, forcing millions to work longer or bridge a gap of up to 11 months without state support. Anyone who turns 66 before March 6, 2027 will see their retirement age increase by up to 11 months. The state pension age is currently 66 and will gradually rise to 67 between 2026 and 2028.

The Institute for Fiscal Studies has calculated this represents a £4,000 blow to workers. That’s not a rounding error. That’s a holiday, a home repair, six months of energy bills.

  • State pension age rises from 66 to 67 by early 2028
  • Full State Pension is worth just under £12,000 per year
  • A moderate retirement lifestyle for a single person requires around £32,000 per year
  • For a couple, that figure rises to £44,000
  • The gap between State Pension and a moderate lifestyle is approximately £20,000 to £32,000 per year
    The maths doesn’t work for most people. It never did.

Why Is the UK Retirement Savings Gap Getting Worse in 2027?

The UK retirement savings gap is getting worse in 2027 because 15 million working-age people are under saving for retirement, and the final Pensions Commission report expected in spring 2027 is set to confirm a pensions adequacy disaster. The Commission estimates that approximately 15 million people — around 43% of the UK’s working age population — are currently undersaving.

Someone retiring in 2050 is set to have 8% (£800 per year) lower private pension income compared to a retiree in 2025. The gender pensions gap in private pension wealth between males and females aged 55-59 is 48%.

This isn’t a future problem. It’s a now problem wearing a future costume.

  • Only around a third of individuals are on track to achieve adequate retirement income
  • Roughly 36% are not expected to have enough to meet their needs
  • Middle earners, the self-employed, and women are hit hardest
  • The Pensions and Lifetime Savings Association estimates a single person needs £32,000 a year for a moderate retirement
  • The full State Pension is just under £12,000
    The gap is £20,000 a year. For 20 years of retirement. That’s £400,000.

Why Are Adult Social Care Costs a Ticking Time Bomb for Over 55s?

Adult social care costs are a ticking time bomb for over 55s because frozen means-test thresholds have forced some care users to spend an additional £12,400 of their own money before qualifying for state support, with the Department of Health and Social Care estimating reform costs of £3.7 billion in 2027-28 alone. The social care support threshold has been frozen since 2010/11.

  • A social care support threshold freeze since 2010/11 means some people must spend an additional £12,400 before qualifying for state support
  • If the threshold had been uprated in line with inflation, it would have been over £35,600 in 2026/27
  • The DHSC estimates the cost of charging reform at £3.7 billion in 2027 to 2028
  • The Personal Expenses Allowance increases from £30.65 to just £31.80 per week in 2026-27
    That’s £31.80 a week to live on after care costs. Not per day. Per week.

How Widespread Is Digital Exclusion Among Over 55s in the UK?

Digital exclusion among over 55s in the UK is widespread, with 2.4 million older people — nearly one in five — having limited use of the internet, going online less than once a month or not at all. Age UK’s analysis found that 19% of older people are digitally excluded, and 33% (4.3 million) don’t use a smartphone.

As government services, banking, health appointments, and even social connections move online, this isn’t a minor inconvenience. It’s a structural lockout.

  • 2.4 million older people have limited internet use (19%)
  • 4.3 million older people don’t use a smartphone
  • 6 million (12%) older people do not use a mobile phone at all
  • Three-quarters of supporters (76%) say the main person they support is over 55
  • A lack of digital skills is higher among people receiving support over the age of 55 (60%)
    The system is being rebuilt for digital-first. And millions are being left outside the door.

Why Is Loneliness Among Over 55s Set to Reach Crisis Levels?

Loneliness among over 55s is set to reach crisis levels because the number of over-50s experiencing loneliness is set to reach two million by 2025/26 — a 49% increase in just ten years. Nearly a quarter (22%) of adults aged 55 and over most fear loneliness and disconnection in later life.

  • Half a million older people in the UK go at least five or six days a week without speaking to anyone at all
  • Men aged 55-64 are the most adversely affected, with 15% reporting they have no close friends
  • Up to 18% of UK adults feel lonely “always or often”
  • Loneliness is linked with early mortality, poor physical health, mental ill-health, and cognitive decline
    Loneliness isn’t a soft issue. It’s a health issue. It kills.

Why Is Downsizing Not Working for Over 55s in the UK?

Downsizing is not working for over 55s in the UK because only 19% plan to downsize in retirement, with 21% saying it’s too expensive to move and a further 8% citing stamp duty as a barrier. The shortage of specialist housing for people in later life has denied many the option of rightsizing from unsuitable properties into smaller, purpose-built homes.

  • Only 19% of older homeowners plan to downsize
  • 21% say it’s too expensive to move
  • 8% cite stamp duty as a factor
  • There is a need for 30,000 specialist homes per year compared to current output of 5,000-7,000
  • More than a third of older homeowners struggle to find the right property, particularly bungalows or single-level homes
    The family home becomes a trap. Too big to manage, too expensive to leave.

How Will Inheritance Tax Changes in April 2027 Affect Over 55s?

Inheritance tax changes in April 2027 will affect over 55s by bringing pensions into people’s estates for inheritance tax purposes for the first time, bringing many more estates into the taxpaying net. The inclusion of pensions in people’s estates for inheritance tax purposes from April 2027 will prompt people to look at ways to reduce the size of their overall estate.

This is a fundamental shift. Pensions were previously outside the IHT net. From April 2027, they’re in.

  • Pensions included in estates for IHT from April 2027
  • Many more estates will be brought into the taxpaying net
  • The Pensions Commission final report expected spring 2027
  • Automatic enrolment has created 11 million more pension savers than in 2012, but adequacy remains the problem

Why Are Over 55s Facing a Health and NHS Waiting List Crisis?

Over 55s are facing a health and NHS waiting list crisis because as of June 2025, 58,730 people aged 65+ were waiting for longer than 52 weeks, and over-55s are prepared to wait nearly four months for non-urgent treatment. As of June 2025, 63% of people aged 65+ were referred for third consultant-led treatment within 18 weeks.

  • of 6.25 million people waiting for elective care on people 7.43 million pathways as at January 2025
  • 56% of the overall waiting list is people aged 19-64
  • A on wait lists are aged 65 and over
  • The largest specialty for those aged 65+ is ophthalmology (14% of over 65s)
    Waiting is not neutral. Waiting is deterioration.

Why Is Age Discrimination Still Blocking Over 55s from Work?

Age discrimination is still blocking over 55s from work because 78% of older workers say they’ve experienced age discrimination, and 45% of over-55s who lose their job are still searching after six months. The average age someone becomes undesirable to recruiters is 55, according to a poll of 4,000 UK adults.

  • 78% of older workers say they’ve experienced age discrimination
  • 45% of over-55s who lose their job are still searching after six months
  • 69% of UK adults aged 50 to 66 felt older age was a disadvantage in the job market
  • Only 11% thought being over 50 was an advantage
  • In 2025, people in the 50-plus age group were the most likely to be made redundant in the UK
    You’re not too old. The system is too rigid.

Why Are Over 55s Struggling with the Cost of Living?

Over 55s are struggling with the cost of living because 1.9 million pensioners are living in poverty — around one in six — and more than 3.7 million homeowners aged 55 to 79 do not have enough income to reach a moderate standard of living in retirement. One in 3 (34%) older people said they felt less financially secure heading into 2025 compared to when 2024 began — equivalent to 4.1 million people.

  • 1.9 million pensioners living in poverty (16%)
  • 3.7 million homeowners aged 55-79 without enough income for a moderate retirement
  • 34% of older people felt less financially secure heading into 2025
  • 45% of older people in a household with income less than £20,000 struggled with essentials

What Are 12 Innovative Solutions to Solve the Hardest Problems for Over 55s in 2027?

The 12 innovative solutions to solve the hardest problems for over 55s in 2027 are: pension bridging strategies, collective defined contribution schemes, home equity release innovations, digital skills peer networks, community-based co-living models, phased retirement pathways, preventive health investment, portable benefit platforms, micro-entrepreneurship hubs, care cost pooling, loneliness intervention technology, and intergenerational skills exchange. These aren’t theoretical. They’re being developed now.

  1. Pension Bridging Strategies

Pension bridging strategies solve the retirement income gap by using ISA savings, part-time work, and deferred State Pension to create a bridge between age 55 and State Pension age. With the State Pension age rising to 67, millions face a gap. By drawing from ISAs first and deferring State Pension, you can increase your eventual pension by up to 5.8% per year of deferral. The Pensions Commission’s final report in 2027 is expected to recommend new default decumulation pathways.

  1. Collective Defined Contribution (CDC) Schemes

Collective Defined Contribution schemes solve pension adequacy by pooling risk across members to provide better retirement outcomes than individual DC pots. The UK regulatory framework for Retirement CDC is expected in 2027, with master trusts preparing to launch solutions. LifeSight is the first master trust to confirm it will launch an R-CDC solution as soon as the framework allows. This isn’t a fringe idea. It’s coming.

  1. Home Equity Release Innovations

Home equity release innovations solve the downsizing trap by allowing over 55s to access property wealth without moving. With only 19% of older homeowners planning to downsize and 21% saying it’s too expensive to move, equity release becomes a practical alternative. New products are emerging that allow you to stay in your home while unlocking capital. The key is understanding the costs and ensuring it’s right for your circumstances.

  1. Digital Skills Peer Networks

Digital skills peer networks solve digital exclusion by having over 55s teach other over 55s, creating trust and reducing the intimidation factor. With 2.4 million older people digitally excluded, the traditional approach of younger people teaching older people isn’t working fast enough. Peer-to-peer learning removes the fear of looking stupid. It removes the power imbalance. It works.

  1. Community-Based Co-Living Models

Community-based co-living models solve loneliness and housing costs by creating shared living arrangements for over 55s that combine independence with connection. Half a million older people go at least five or six days a week without speaking to anyone at all. Co-living — where residents have private spaces but share kitchens, gardens, and social areas — addresses both loneliness and the cost of maintaining a large family home.

  1. Phased Retirement Pathways

Phased retirement pathways solve the cliff-edge retirement problem by allowing workers to gradually reduce hours while mentoring younger staff and maintaining income. With 78% of older workers reporting age discrimination and 90% of workers over 50 saying they’d like to stay in the workforce, the system needs to change. Phased retirement keeps skills in the economy, keeps income flowing, and keeps purpose alive.

  1. Preventive Health Investment

Preventive health investment solves the NHS waiting list crisis by reducing demand through proactive health management before problems become acute. With 58,730 people aged 65+ waiting longer than 52 weeks for treatment, prevention is the only scalable solution. This means structured exercise, nutrition, sleep optimisation, and mental health support — not as luxuries, but as core retirement infrastructure.

  1. Portable Benefit Platforms

Portable benefit platforms solve the fragmented support problem by allowing over 55s to access all available benefits, discounts, and entitlements in one place. With 1.9 million pensioners in poverty, millions are not claiming what they’re entitled to. A single platform that identifies Pension Credit, Attendance Allowance, Council Tax reductions, and energy discounts could put thousands back in people’s pockets.

  1. Micro-Entrepreneurship Hubs

Micro-entrepreneurship hubs solve income adequacy by helping over 55s turn skills and experience into small businesses with low overheads and high autonomy. With 3.7 million homeowners aged 55-79 unable to reach a moderate retirement standard, traditional employment isn’t the only answer. Consulting, freelancing, tutoring, and craft businesses can generate income while providing purpose and flexibility.

  1. Care Cost Pooling

Care cost pooling solves the catastrophic risk of social care costs by spreading the financial burden across a wider group, similar to insurance principles. With the social care threshold frozen since 2010/11 and care users forced to spend an additional £12,400 before qualifying for state support, individual risk is unsustainable. Pooling mechanisms — whether through insurance products or community schemes — can protect individuals from ruin.

  1. Loneliness Intervention Technology

Loneliness intervention technology solves isolation by using simple, accessible tools to connect over 55s with local activities, interest groups, and companions. The number of over-50s experiencing loneliness is set to reach two million by 2025/26. But the solution isn’t more apps. It’s using technology to facilitate real-world connection — walking groups, coffee mornings, skill-sharing sessions.

  1. Intergenerational Skills Exchange

Intergenerational skills exchange solves both loneliness and digital exclusion by creating structured programmes where over 55s share life skills and younger people share digital skills. Three-quarters of digital supporters say the main person they support is over 55. But what if the exchange went both ways? What if over 55s taught budgeting, cooking, gardening, and resilience, while younger people taught smartphone skills, online banking, and video calling?

What Does the Future of Retirement Look Like Beyond 2027?

The future of retirement beyond 2027 looks like a shift from a cliff-edge model to a fluid, phased, and self-directed approach where work, learning, health, and community are continuous rather than sequential. The Pensions Commission’s final report in spring 2027 will make recommendations for future pension policy. The regulatory framework for Retirement CDC will be published, with schemes rolled out in 2027/28. Inheritance tax treatment of pensions changes in April 2027.

The old model — work 40 years, retire at 65, live on a pension — is dead. It died when the State Pension age started rising, when final salary schemes closed, when the cost of living outstripped pension increases.

The new model is being built now. By people who refuse to accept that the only options are struggle or surrender.

  • Phased retirement becomes normal, not exceptional
  • Collective pension schemes provide better outcomes than individual pots
  • Home equity becomes a legitimate retirement income source
  • Digital inclusion becomes a basic right, not a luxury
  • Community becomes infrastructure, not afterthought

What Is CheeringUpInfo Retirement Club Exploring?

CheeringUpInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in UK have now and in near future. The club is focused on improving retirement lifestyles in the UK by connecting like-minded people, sharing practical solutions, and challenging the conventional wisdom that says retirement means decline.

The club operates outside standard structures. It attracts people who want pure abundance — in health, in wealth, in connection, in purpose. People who are driven by personal freedom and radical autonomy. People who refuse to accept that the best years are behind them.

The problems are real. The stats don’t lie. But the solutions exist. And the first step is refusing to accept that the problems are unsolvable.

The hardest problems are the ones everyone knows about. The ones we’ve been told are too difficult. The ones that require thinking differently.

That’s where the innovation happens. That’s where the future gets built.

#Over55sUK #RetirementSolutions2027 #RetirementClub #RetirementMagazine #RetirementTV

Get help to protect and grow your business faster with CheeringupInfo by offering amazing deals at still profitable prices to over 55s in the UK

Find out more about targeted advertising and marketing to over 55s in UK

Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips

Connect with CheeringUpInfo for free retirement lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free

Connect with CheeringUpInfo for free alerts to new retirement lifestyle improvement articles and videos

Retirement in the UK isn’t a reward. It’s a trap. And 15 million over 55s are walking into it with their eyes wide shut.

The 2027 Retirement Trap: 15 Million Undersaving, £20,000 Annual Gap, And The 12 Solutions Nobody Talks About

  • The State Pension is just under £12,000 a year.
  • A moderate retirement lifestyle costs £32,000 a year.
  • That’s a £20,000 hole. Every single year. For 20 years. That’s £400,000.
  • Do the math. Most people can’t.

But here’s what’s really disturbing…

  • 1.9 million pensioners are already living in poverty — that’s one in six.
  • 2.4 million over 55s are digitally excluded — locked out of banking, appointments, even social connection.
  • 500,000 older people go five or six days a week without speaking to anyone at all.
  • 78% of older workers say they’ve faced age discrimination.
  • And from April 2027, your pension is included in your estate for inheritance tax. The government is coming for it either way.

And it gets worse.

The state pension age rises to 67 by early 2028. The social care means-test threshold has been frozen since 2010/11 — some care users now spend an additional £12,400 before getting state support. NHS waiting lists for over 65s hit 58,730 people waiting longer than 52 weeks.

Most people will read this and feel stuck. They’ll hope for the best. They’ll vote for someone who promises change. They’ll keep scrolling.

But a few will do something different.

They’ll look at the 12 solutions that actually exist: pension bridging, collective defined contribution schemes, home equity release, digital peer networks, co-living models, phased retirement, preventive health, portable benefit platforms, micro-entrepreneurship hubs, care cost pooling, loneliness intervention tech, and intergenerational skills exchange.

These aren’t fantasies. They’re being built right now. And they work.

Most people stop here. The ones who don’t are the ones who change their retirement.

Email editor@cheeringup.info with the subject line RETIREMENT CLUB for more information on Retirement Club.

CheeringUpInfo Retirement Club is exploring these solutions to the really difficult problems over 55s in the UK have now and in the near future. You can too.

Featured Products For Over 55s
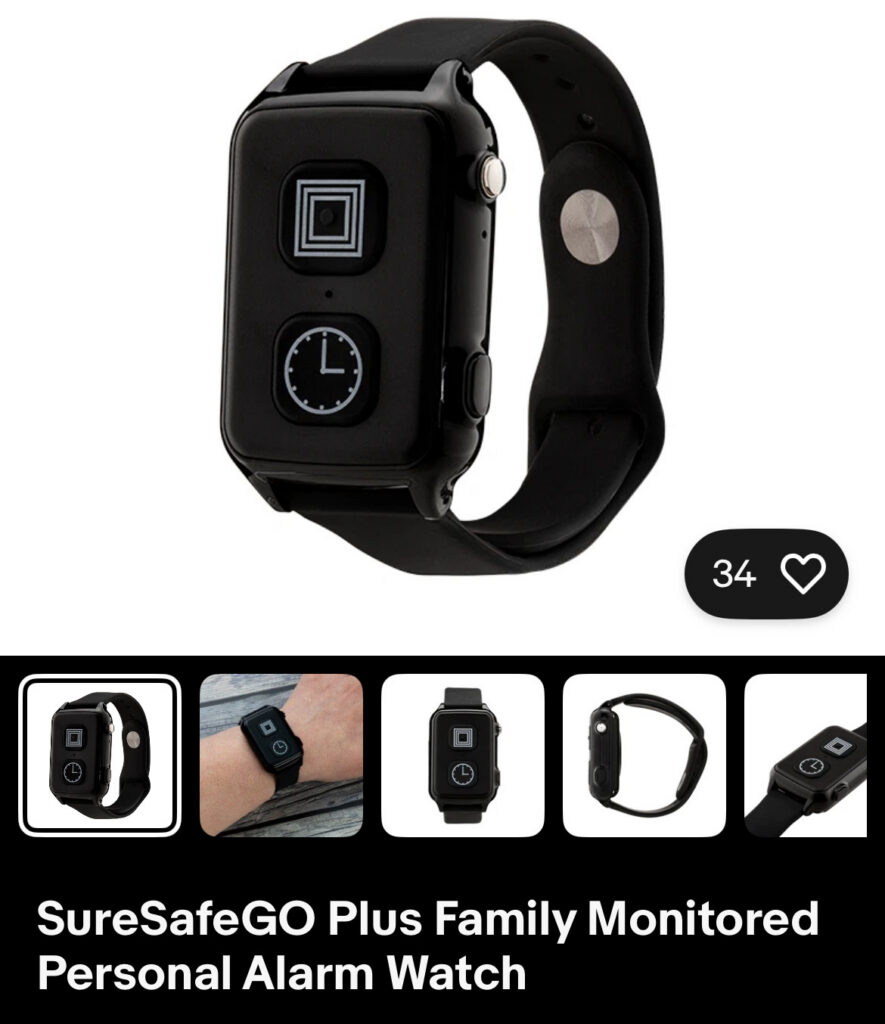
SureSafeGO Plus Family Monitored Personal Alarm Watch

https://ebay.io/m/JXKOEN

As an eBay Partner, I may be compensated if you make a purchase
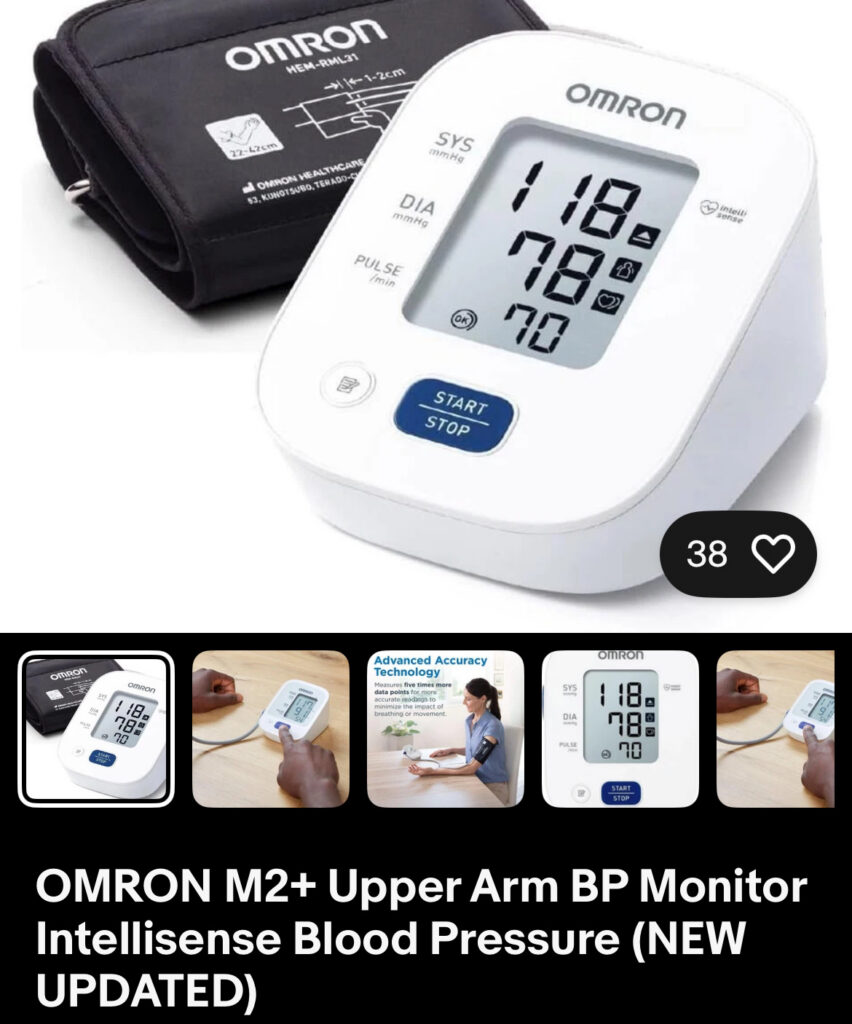
OMRON M2+ Upper Arm BP Monitor Intellisense Blood Pressure (NEW UPDATED)

https://ebay.io/m/Yx0pX5

As an eBay Partner, I may be compensated if you make a purchase
MEACO DD8L PRO DESSICANT DEHUMIDIFER – 3 YEAR WARRANTY

https://ebay.io/m/9GU7Q3

As an eBay Partner, I may be compensated if you make a purchase

Is This As Good As It Gets? Retirement UK | CheeringUp.info

Is this as good as it gets? CheeringUp.info helps older people in the UK improve retirement with information, inspiration, ideas and local help. Act now.

CheeringupInfo Retirement Club recommends CheeringUp.info resources as the solution to the problem of how to cost effectively improve retired years. With over 12 million UK pensioners receiving a state pension of just £241.30 a week—an annual income of £12,548—and 3.4 million pensioners (28%) describing themselves as financially struggling, the question “Is this as good as it gets?” has never been more urgent. CheeringUp.info exists to answer that question with a resounding “No—and here’s how to change it.”

Is this as good as it gets?

Is this as good as it gets is the question CheeringUp.info was built to answer—and the answer is that your retirement years can be significantly better with the right information, inspiration, and ideas. Life after 55 in the UK does not have to mean shrinking your world. It can mean expanding it. CheeringUp.info sets out to help particularly older people in retirement—and those planning for better life including retirement years—be better at life living and business in the UK. Whether you are already retired, approaching retirement, or planning your later years, CheeringUp.info provides the tools to improve your lifestyle in the UK.

Why does CheeringUp.info work when other approaches fail?

Why CheeringUp.info works when other approaches fail is because it focuses on cost-effective, practical lifestyle improvement rather than expensive financial products. Age UK’s 2026 report reveals that only 6% of pensioners sought financial help or advice in the past year, with nearly half believing they would not be eligible for support and one in five not knowing who to contact. CheeringUp.info bridges that gap. It offers:

Who will benefit most from exploring CheeringUp.info?

Who will benefit most from exploring CheeringUp.info are older people in retirement, those planning for better life including retirement years, and anyone in the UK who refuses to accept that “this is as good as it gets.” The impact is particularly significant for:

  • Pensioners on low incomes—the 28% of pensioners financially struggling, rising to 51% among private renters.
  • Those facing the state pension age rise—from April 2026, the pension age is rising from 66 to 67, with a month added every two months until 2028. Those born on 31 July 1960 will not reach pension age until 30 November 2026, and those born on 31 December 1960 until 30 September 2027.
  • People planning ahead—the Pensions Dashboard, expected to launch in late 2026 or early 2027, will help reconnect an estimated 3.3 million lost pension pots worth £31 billion to their owners. CheeringUp.info helps you prepare for that moment.
  • Those in business or considering self-employment in later life—CheeringUp.info covers business as well as lifestyle, recognising that many older people in the UK are choosing to work beyond retirement age.

When is the best time to use CheeringUp.info?

The best time to use CheeringUp.info is now—September 2026—because critical deadlines and changes are imminent that will directly affect your income and lifestyle. The urgency is real:

  • The Winter Fuel Payment qualifying week is 21–27 September 2026. If you were born on or before 27 June 1960, you could receive between £100 and £300 to help with heating bills for winter 2026–27—but you need to ensure you are eligible and prepared.
  • Energy bills remain more than £500 higher than at the end of 2021, and prices look set to rise again. Age UK found that 69% of pensioners would rather turn off their heating than get into energy debt—a stark indicator of the trade-offs many are making at the cost of their health.
  • Party conference season is underway—Labour’s conference begins 27 September 2026, with Conservative and other party conferences following in October. Policies affecting pensions, social care, and older people will be debated and decided.
  • The Pensions Dashboard launches in late 2026 or early 2027, meaning you have a narrow window to locate and organise your pension information before the system goes live.

The message is clear: if you wait until 2027, you will have missed the opportunity to act before these changes take effect.

Where can you get local help for offline assistance?

Where you can get local help for offline assistance is through CheeringUp.info’s network of local resources, which complement the online platform with face-to-face support in your area. Not everyone is comfortable navigating digital resources alone. CheeringUp.info recognises this and connects you with:

  • Local community groups and retirement clubs across the UK
  • Age UK and other health organisation partners who provide in-person guidance
  • Libraries and community centres offering digital skills support
  • Local business networks for those exploring self-employment or business in retirement

The combination of online information and offline human connection is what makes CheeringUp.info different. You are not left to figure it out alone.

What is really exciting or risky about what is happening now?

What is really exciting about what is happening now is the potential to transform retirement from a period of decline into one of opportunity—but what is really risky is the cost of inaction. The exciting possibilities include:

  • The Pensions Dashboard will finally allow you to see all your pensions in one place, including state pensions, defined benefit and defined contribution pensions, and personal pensions. This is a once-in-a-generation opportunity to take control of your retirement finances.
  • The triple lock has delivered a 4.8% increase, taking the full new state pension to £241.30 a week. This is real money that can be used to improve your lifestyle—if you know how to use it.
  • A growing movement of older people who are rejecting the traditional model of retirement and instead building businesses, learning new skills, and creating meaningful social connections.

The risks of inaction are equally real:

  • Energy costs that are more than £500 higher than at the end of 2021 and set to rise again, with the price cap expected to increase by around £202 per year.
  • The state pension age rise means millions face working an extra year, and those who have not planned for the transition may find themselves financially exposed.
  • Loneliness and isolation linked to higher risk of heart disease, stroke, depression, and cognitive decline, with some studies suggesting the health impact is comparable to smoking or obesity. Severe loneliness costs around £9,900 per person each year.

How can the 100th monkey effect change UK retirement?

How the 100th monkey effect can change UK retirement is by demonstrating that once a critical mass of people adopts a new behaviour, it enters the collective consciousness of everybody—meaning you only need to persuade up to 100 people for a transformation to spread across the world. The story of the 100th monkey—in which a behaviour learned by one group of monkeys on a Japanese island suddenly appeared in other groups separated by sea—has long served as an allegory for the emergence of collective intelligence and the idea that societal change can occur once a critical mass is reached.

Once you get to 100 monkeys, you no longer need to persuade any more monkeys. It just enters the collective consciousness of everybody on the planet. Therefore you only need to persuade up to 100 people for it to be a tourism across the world. If we can connect with likeminded individuals, maybe things in the UK can change for the better. CheeringUp.info is that connection point.

What should you do next?

What you should do next is visit CheeringUp.info, explore the resources, and join a community of people who are asking “Is this as good as it gets?”—and answering with action. The statistics tell a powerful story:

  • Over one in four pensioners are financially struggling
  • 270,000 people aged over 65 go an entire week without speaking to a friend or family member
  • Energy bills are more than £500 higher than at the end of 2021
  • The state pension age is rising, and the Pensions Dashboard is coming

But here is the truth that CheeringUp.info was built to share: this is not as good as it gets. With the right information, inspiration, and ideas—and with a community of likeminded individuals working together—retirement in the UK can be better. The tools are there. The resources are there. The local help is there. The only question is whether you will use them.

Visit CheeringUp.info today. Your better retired years start now.

#RetirementUK #CheeringUpInfo #RetirementTV #RetirementMagazine #RetirementClub

Get help to protect and grow your business faster by offering over 55s quality products and services at fair price

Find out more about growing your business in UK faster with CheeringupInfo

Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips

Connect with CheeringUpInfo for free retirement lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free

Connect with CheeringUpInfo for free alerts to new retirement lifestyle improvement articles and videos

The Person You Are: How to Live the Life of That Person Every Day

Discover the neuroscience-backed secret to becoming your ideal self: act “as if” you already are that person. This post explains how embodying your aspirational identity today—through the psychological principle of “possible selves”—can transform your retirement reality. Join the CheeringUp.info Retirement Club to connect with like-minded individuals on this journey of self-reinvention.

What Is the Person I Am Meant to Become in Retirement?

The person you are meant to become is not a distant stranger waiting in the future; they are a version of you that already exists in your imagination, waiting to be embodied through action. This concept, rooted in the psychological theory of “possible selves,” suggests that your aspirations and fears about the future directly influence your current motivation and behaviour. For those in retirement, this is the perfect opportunity to define and live into that aspirational identity.


Why Should You Live the Life of That Person Every Day, Even If You Aren’t There Yet?

You should live the life of that person every single day because the gap between your current self and your ideal self is bridged by the practice of “acting as if.” The phrase “fake it till you make it” is not about deception; it’s a practical application of neuroplasticity, allowing your brain to rewire itself through consistent behaviour. William James, a highly influential philosopher, noted, “If you want a quality, act ‘as if’ you already had it” . By embodying the confident, engaged retiree you wish to be, you are accelerating that identity integration.

  • Neuroplasticity in Action: Your brain creates new neural pathways when you consistently act in a certain way. The more you show up as your future self, the more natural it becomes .
  • The Feedback Loop: Actions influence emotions as much as emotions influence actions. A forced smile can trigger a happier mood . The physical state of your body can directly impact your mood and cognition; for instance, raising your spine and holding your head up can lead to a boost in self-confidence .
  • Closing the Gap: As one executive coach noted, high performers consciously imagine their ideal future self’s reactions, tone, and attitude before the moment arrives. These future qualities act as an anchor, reducing burnout and increasing joy . One professional who adopted this strategy reported that within a month of consciously presenting as “cool, calm, and collected,” he stopped performing and started being .

How Does the “Possible Selves” Theory Support This Claim?

The “possible selves” theory provides the academic backbone for this mindset, showing that your vision of who you could become is a powerful motivator. According to this theory, individuals are driven to take actions that either move them toward their “ideal self” (a positive image worth pursuing) or away from their “feared self” (a negative image to be avoided) . In the context of retirement, this means that if you want to be an active, connected, and purposeful individual, you must create a vivid, detailed version of that self and take steps to live into it.

Research has found that informal learning accounts for 80% of personal knowledge and skills acquisition . For retirees, this means the vast majority of your growth comes from self-directed activities.

  • Fact 1: Your brain often cannot distinguish between a vividly imagined experience and a real one . This is why visualization is so powerful in rewiring limiting beliefs.
  • Fact 2: The Reticular Activating System (RAS) in your brain filters information based on your goals. When you act “as if,” you engage the RAS to notice opportunities that align with your aspirational identity .
  • Fact 3: According to research on “possible selves,” those who clearly express their future self-images are more inclined to implement the tactics needed to realize their goals .

What Are the Practical Steps to Embodying Your Ideal Retired Self?

Embodying your ideal retired self involves practical, daily habits that reinforce your new identity. You can start by defining three aspirational words that capture your best future self and setting them as reminders on your phone or calendar . This simple habit creates a “check-in” to ensure your actions align with the person you are becoming.

  • Dress the Part: Show up to your day dressed like the person you want to become. As one expert put it, “Energy matters” .
  • Take Brave Action Daily: As Franklin D. Roosevelt famously said, “Do the thing and you will have the power.” Power and confidence follow action, not the other way around . Don’t wait to feel ready; build confidence through momentum.
  • Journal from the Future: Write from the perspective of the version of you who has already “made it.” What are they doing? What do they feel? What are they grateful for? .
  • Use the “Best Possible Self” Exercise: Write for 20 minutes, three days in a row, about what your life will look like in several years if everything goes as well as possible. This has been shown to improve mood for up to three weeks .
  • Make a Pact: Commit to acting enthusiastic for 30 days. Track your mood, relationships, and productivity as enthusiasm goes from something you force to a habit that feels real .

What Role Does the CheeringUp.info Retirement Club Play in This Transformation?

The CheeringUp.info Retirement Club is your community for this transformation, providing a supportive environment to share your journey and find inspiration. Our online retirement club for over-55s in the UK helps you connect with like-minded people who are also actively designing their best retired lives. By engaging with our community, you are “surrounding yourself with evidence” that your vision is achievable .

#ActAsIf #RetirementGoals #CheeringUpClub #RetirementClub #RetirementMagazine

Get help to protect and grow your business faster more cost effectively with CheeringUpInfo

Find out more about CheeringUpInfo targeted marketing to over 55s and those planning for better retirement

Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips

Connect with CheeringUpInfo for free retirement lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free

Connect with us for free alerts to new retirement lifestyle improvement articles and videos

How to set up a property limited company for buy-to-let UK

Tax-efficient buy-to-let strategy for retirement income UK. If you’re searching for a tax-efficient buy-to-let strategy for retirement income, this is your blueprint. Read a non-technical accessible eBook now to avoid missing UK investment retirement lifestyle improvement tips today.

The Property Millionaire’s Retirement Blueprint: How to Build a Tax-Efficient Buy-to-Let Empire Using Limited Companies

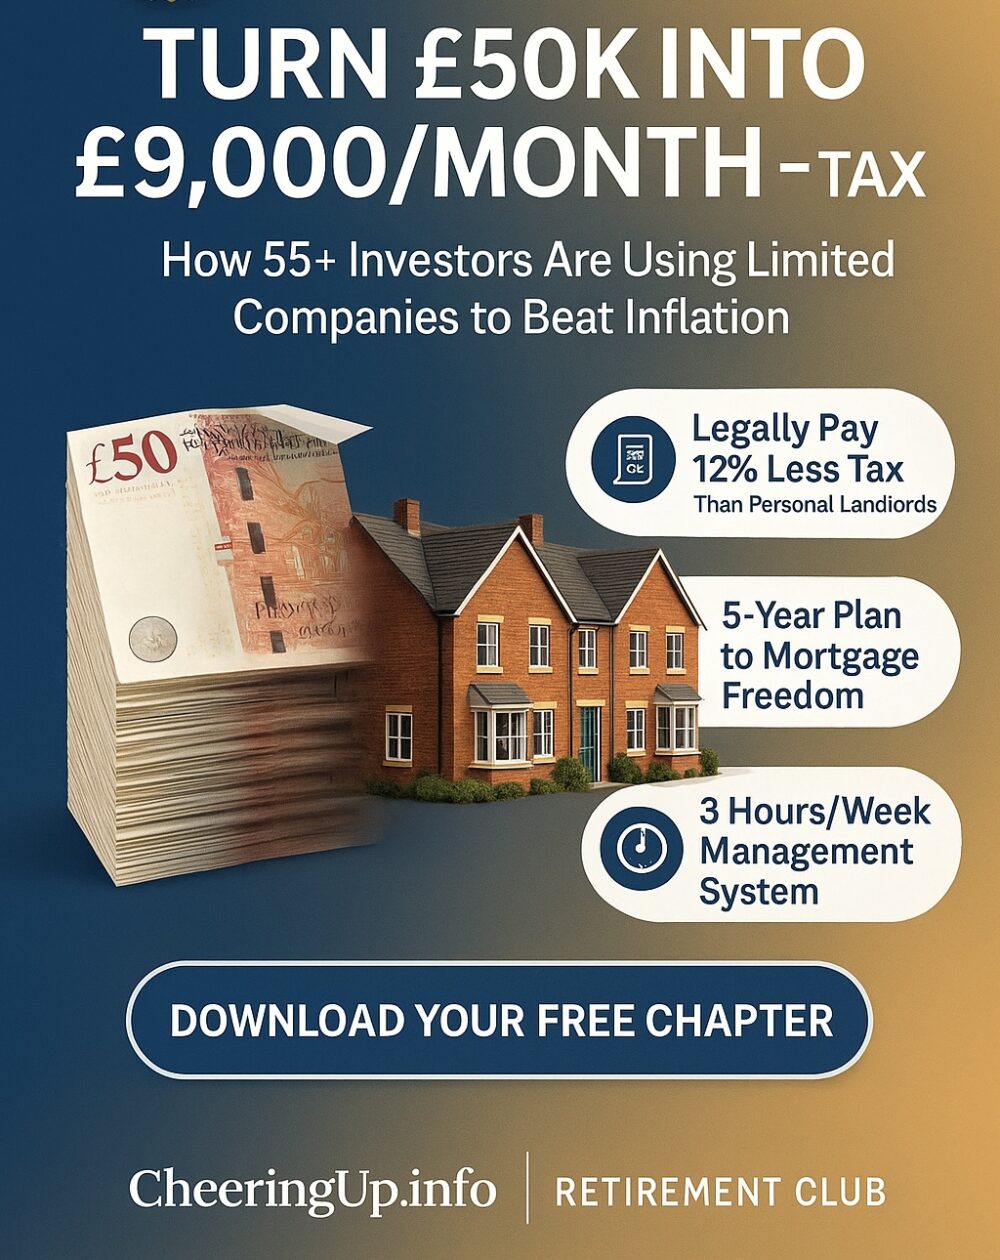
For UK Investors 55+: Beat inflation & build lasting wealth with buy-to-lets in limited companies! This eBook reveals:

✅ Step-by-Step SPV Setup – Legally save £12K+/year vs personal ownership

✅ 5-Year Plan to scale from 2 to 10+ properties (case study: £9,200/month income)

✅ Mortgage Hacks – How lenders approve new companies

✅ Tax Loopholes – Holiday lets, pension dumps & trivial benefits

📊 Includes: Checklists, lender tables & real investor case studies

There’s a way to grow your wealth tax-efficiently – using property limited companies

Perfect for: Cash-rich retirees, SIPPs diversifiers & side-hustlers

Buy at Limited Launch Price!

👉 Contact Us For More Information on Retirement Lifestyle Improvement UK

#PropertyInvesting #RetirementPlanning #BTLInvesting #TaxEfficiency

The Retirement Time Bomb – And How to Defuse It

Imagine this: You’re 55, sitting on a £500,000 cash pile. Comfortable? For now. But at 3% inflation, in 20 years, that money will be worth just £276,000 in today’s terms. Worse, if you’re drawing £30,000 a year from savings, you’ll run out of money before you hit 80.

Scary? It should be.

But here’s the good news: There’s a way to turn that cash into a growing, inflation-proof income stream that lasts the rest of your life—without gambling on stocks or praying for pension reforms.

The solution? Property. Mortgages. Limited companies.

This isn’t about getting rich quick. It’s about building a retirement machine—one that pays you more as rents rise, more as properties appreciate, and more as tax-efficient profits stack up inside a company structure.

In this guide, you’ll get a step-by-step playbook for:

  • Setting up the right limited company structure (one vs. multiple companies—and why it matters).
  • Securing mortgages inside that company (even if you’ve never run a business before).
  • Buying properties that work for your retirement (not just “any” buy-to-lets).
  • Extracting profits in the most tax-efficient way (legally paying less to HMRC).
  • Scaling to 5, 10, or 20 properties without drowning in admin.

We’ll use real case studies—like the 62-year-old who turned £250K into £1.2M of property equity in 7 years, now paying him £4,500/month after tax. No fluff. No jargon. Just actionable strategies that work in today’s market.

Ready? Let’s build your retirement fortress—one brick (and mortgage) at a time.

“At 3% inflation, £500,000 today is worth just £276,000 in 20 years—enough to last most retirees only 12 years at £30,000/year withdrawals.”


Chapter 1: The Retirement Cash Trap

John and Sheila thought they’d nailed retirement. £750,000 in savings. A paid-off house. Dreams of cruises and grandkids.

Then reality hit.

After 10 years of 2.5% interest and £36,000/year withdrawals, their pot had shrunk to £390,000. Worse, inflation meant that £36,000 now bought what £28,000 did a decade earlier.

“We never imagined running out,” John admitted. “But at this rate, we’ll be broke by 78.“

The culprit? Cash is a terrible long-term asset.

Here’s what works instead…

CHAPTER 1: THE RETIREMENT CASH TRAP – WHY PROPERTY BEATS PENSIONS & SAVINGS

The Silent Crisis: Your Money is Disappearing

But here’s the brutal truth—your money is melting away faster than you think.

At just 3% inflation, that £500,000 will be worth only £276,000 in today’s money in 20 years. If you withdraw £30,000 a year to live on? You’ll run out before your 80th birthday.

And that’s before factoring in unexpected costs—care home fees, medical bills, or helping your kids onto the property ladder.

Pensions Are a Gamble

The stock market swings wildly. A 20% crash just before retirement could slash your income forever.

Case Study: David, 62, saw his £400,000 pension pot drop to £320,000 in 2022. He now gets £1,200 less per month than planned.

Cash Savings Lose Value Every Year

Even “high-interest” accounts pay less than inflation. Your money is guaranteed to buy less over time.

  • Example: £100,000 at 2% interest = £148,595 in 20 years. But at 3% inflation, it’s really worth just £82,000 in today’s terms.

Bonds & ISAs Can’t Keep Up

The best 5-year fixed-rate bonds pay ~5%. After tax and inflation? Barely breaking even.

Why Property Wins (The Math Doesn’t Lie)

InvestmentAvg. Annual ReturnKey Risk
Savings Account1-3% (pre-tax)Loses to inflation
S&P 500 (Stocks)7-10% (volatile)Market crashes hurt
UK Buy-to-Let*12-15%Tenant voids (manageable)

*Assumes 5% rental yield + 5% appreciation + 2-5% mortgage leverage.

The Triple Advantage of Property:

  1. Rental Income – Inflation-proof cash flow (rents rise with costs).
  2. Capital Growth – Property doubles every 10-15 years historically.
  3. Leverage – A £200,000 house with a 75% mortgage only ties up £50,000 of your cash.

The Pension vs. Property Showdown

Scenario: You have £250,000 to invest at age 55.

  • Pension Route:
  • Draw 4% per year = £10,000/year.
  • After 20 years? Pot likely depleted.
  • Property Route (Limited Company):
  • Buy 4 x £200,000 houses (25% deposit each).
  • Rent: £800/month each = £38,400/year gross.
  • After mortgage costs & tax: £18,000+/year profit.
  • Plus the properties now worth ~£1,000,000.

The Psychological Edge

Unlike stocks, property is:

  • Tangible – You can see and improve it.
  • Control – Raise rents, refinance, or sell on your timeline.
  • Predictable – Tenants pay rent like clockwork with proper vetting.

Your First Action Step

Do this today:

  1. Open a spreadsheet.
  2. List your current savings/pensions.
  3. Calculate their real value in 10 years (subtract 3% inflation yearly).

The gap between that number and the income you’ll need? That’s why you need property.


Next Chapter Preview:
“Why a Limited Company? (And When It’s Not the Right Choice)”

  • The £12,000/year tax loophole HMRC doesn’t advertise.
  • The one scenario where owning property personally still beats a company.

CHAPTER 2: WHY A LIMITED COMPANY? (AND WHEN IT’S NOT THE RIGHT CHOICE)

The £12,000 Tax Loophole Every Property Investor Should Know

Let me tell you about Sarah, a 58-year-old dentist from Manchester. She owned three buy-to-lets personally, earning £36,000/year in rent. After income tax at 40% and mortgage interest deductions, she kept just £19,000. Then she switched to a limited company structure – and legally paid £12,000 less in tax that first year.

This is why smart investors are flocking to limited companies. But it’s not right for everyone. Let’s break it down.

The Tax Tsunami Hitting Personal Landlords

Since 2017, three changes have crushed personal landlords:

  1. Mortgage interest tax relief phased out (now just a 20% credit)
  2. Section 24 rules making rental income look artificially high
  3. Capital Gains Tax still at 18-28% when you sell

For higher-rate taxpayers, this is brutal. But limited companies get:
✔ Full mortgage interest deduction
✔ Corporation Tax at just 25% (vs 40-45% income tax)
✔ 19% tax on capital gains (vs 28% personally)

The Numbers Don’t Lie: Company vs Personal

Let’s compare £50,000 rental profit:

Personal (40% taxpayer)Limited Company
Tax Rate40%25%
Mortgage Interest (30k)Only 20% reliefFull deduction
Net Tax Bill£20,000£8,000
Annual Savings–£12,000

When a Limited Company Doesn’t Make Sense

  1. The One-Property Wonder
    If you own just one £150,000 flat making £7,500/year rent? The £500 company accounts cost might outweigh savings.
  2. Basic Rate Taxpayers
    Earning under £50,270? Your 20% tax rate is close to Corporation Tax – less benefit.
  3. Planning to Sell Soon
    Companies pay 19% on gains, but extracting cash later may trigger dividend tax. Personal CGT allowance (£3,000) can sometimes work better.

The Hidden Costs Nobody Talks About

  • Accountancy fees (£800-£1,500/year vs £300 personally)
  • Mortgage rates 0.5-1% higher than personal BTLs
  • More complex tax returns (CT600, confirmation statements)

Case Study: The Semi-Retired Couple Who Got It Wrong

Mike and Jenny transferred their £1.2m portfolio into a company… then discovered:
✖ Their 0.5% personal BTL mortgages became 2.5% company loans
✖ £3,500/year in new accounting/legal fees
✖ No CGT exemption on transfer

They actually lost money for three years. The lesson? Transition gradually.

Your 3-Step Action Plan

  1. Calculate Your Tipping Point
    Use this formula:
    (Current Tax Rate – 25%) × Rental Profit = Annual Savings
    If savings exceed £1,500 (typical company costs), switch.
  2. Test With One Property First
    Transfer just one property to test the waters. Use “incorporation relief” to defer CGT.
  3. Interview Specialist Accountants
    Ask:
  • “How many property clients do you have?”
  • “Can you show me a sample CT600 for rentals?”
  • “What’s your process for profit extraction?”

The Ultimate Hack: Mixed Ownership

Sophisticated investors use both:

  • Keep low-yield properties personally (to use CGT allowance)
  • Put high-mortgage properties in companies (maximize interest relief)

Coming in Chapter 3…
“One Company or Multiple? The Mortgage & Tax Trade-Off”

  • Why some investors create a “lender-friendly” structure with 4 properties per company
  • How to split portfolios to avoid hitting the £250,000 profits threshold

CHAPTER 3: ONE COMPANY OR MULTIPLE? THE MORTGAGE & TAX TRADEOFF

The Million-Pound Question: Single SPV or Multiple Companies?

Meet two investors:

  • David put all 8 properties in one limited company. Simple. Until lenders said “no more mortgages” at property #5.
  • Sarah set up two companies with 4 properties each. She just got her 9th mortgage approved last week.

Who made the right call?

The answer isn’t one-size-fits-all—it depends on tax, lending risk, and your endgame. Let’s break it down.


SECTION 1: THE LENDER’S PERSPECTIVE (WHY TOO MANY PROPERTIES = MORTGAGE REJECTIONS)

The “4-Property Rule” Most Investors Miss

Many high-street lenders impose hidden limits per company:

  • Santander: Max 3-4 BTL mortgages per SPV
  • Paragon: Up to 10, but rates rise after 5
  • High Street Banks: Often reject after 2-3

Why? Risk concentration. If one tenant stops paying, it could domino across all properties in that company.

➡ Solution: Spread properties across multiple SPVs (Special Purpose Vehicles) to keep lenders happy.

Case Study: The Investor Who Hit a Brick Wall

James had 6 properties in one company. At property #7, every lender declined him. He had to:

  1. Spend £1,200 setting up a new company
  2. Wait 6 months to build its credit file
  3. Accept higher interest rates (2.1% → 2.8%)

Cost of mistake: £16,000 in lost rent over 6 months + higher lifetime mortgage costs.


SECTION 2: THE TAX TRIGGERS (WHEN ONE COMPANY COSTS YOU THOUSANDS)

The £250,000 Profit Threshold

  • Below £250,000 profits: 19% Corporation Tax (2025 rate)
  • Above £250,000: 25% Corporation Tax

Example:

  • Single company with £300,000 profit: Entire sum taxed at 25% = £75,000 tax bill
  • Two companies splitting £150,000 each: Both taxed at 19% = £57,000 total tax
    Savings: £18,000/year

The £500,000 “Associated Companies” Trap

HMRC links companies under common control. If total profits exceed £500,000 across all companies, each one loses the 19% rate.

➡ Strategy: Keep each company’s profits under £250,000, and total under £500,000.


SECTION 3: THE GOLDILOCKS STRUCTURE (HOW MANY COMPANIES SHOULD YOU HAVE?)

Portfolio SizeOptimal StructureWhy?
1-3 properties1 companyNot worth the complexity
4-8 properties2 companies (4 each)Avoids lender limits; keeps profits under £250k each
10+ properties1 per 4 propertiesMaximizes mortgage options; isolates risk (e.g., one company has voids)

Pro Tip: Name companies strategically (e.g., “Smith Properties 1 Ltd”, “Smith Properties 2 Ltd”) to streamline banking.


SECTION 4: THE HIDDEN COSTS OF MULTIPLE COMPANIES

  1. Accounting Fees: £800-£1,200 per company/year
  2. Mortgage Complexity: Different rates/terms across lenders
  3. Time Drain: Separate bookkeeping, tax filings, and bank logins

When Multiple Companies Don’t Pay Off:

  • If your total profits are under £100,000
  • If you hate admin (each company = 5+ extra hours/month)

YOUR ACTION PLAN: 5 STEPS TO DECIDE

  1. Project Your Profits
  • Estimate rental income minus expenses for the next 5 years.
  • Will any single company exceed £250,000 profits? If yes, split early.
  1. Talk to a Mortgage Broker
    Ask: “At what point will lenders block my current structure?”
  2. Run the Tax Math
    Compare:
  • Single company tax bill
  • Split-company tax bill (use an online CT calculator)
  1. Future-Proof Your Setup
  • Leave “room” in each company (e.g., don’t max out at 4 properties if expanding soon).
  • Set up companies before you need them (older companies get better mortgage rates).
  1. Consider a Hybrid Approach
  • Keep low-risk properties (e.g., long-term tenants) in one company
  • Put higher-risk/higher-growth properties in separate entities

COMING IN CHAPTER 4…

“Step-by-Step: Setting Up Your Property Company (In Under 7 Days)”

  • The exact Companies House forms to file (and the one mistake that delays approvals)
  • How to open a lender-friendly business bank account without a trading history

CHAPTER 4: STEP-BY-STEP – SETTING UP YOUR PROPERTY COMPANY IN UNDER 7 DAYS

The 72-Hour Company Setup Challenge

Mark, a 56-year-old teacher, thought setting up a property company would take weeks of paperwork. He nearly paid £1,200 to a solicitor to handle it.

Then he discovered the DIY route – done correctly, it took him:

  • 17 minutes to register with Companies House
  • 48 hours to get his company number
  • 6 days to complete everything (including bank account)

Here’s exactly how to replicate this – with insider shortcuts most accountants won’t tell you.


STEP 1: CHOOSING YOUR COMPANY STRUCTURE (CRUCIAL DECISIONS IN 10 MINUTES)

Option A: Standard Limited Company (Ltd)

  • Best for: Most buy-to-let investors
  • Pros:
  • Simple to set up
  • Limited liability
  • Tax-deductible expenses
  • Cons:
  • Must file public accounts

Option B: Special Purpose Vehicle (SPV)

  • Best for: Investors using mortgages
  • Pros:
  • Lenders prefer it (lower risk)
  • Clear property-focused SIC codes
  • Cons:
  • Slightly more complex to explain to banks

Pro Tip: Use these SIC codes (what lenders want to see):

  • 68100 (Buying/selling own real estate)
  • 68209 (Other letting of real estate)

Avoid 68201 (Renting operating space) – some lenders reject this.


STEP 2: REGISTERING WITH COMPANIES HOUSE (DONE IN 17 MINUTES)

What You’ll Need:

  • Proposed company name (have 2-3 backups)
  • Director’s details (name, DOB, address)
  • £12 credit card

The Registration Hack:

  1. Go to the Companies House Web Incorporation Service
  2. Select “Incorporate a private company limited by shares”
  3. Use “Model Articles” (don’t pay for custom ones)
  4. Skip adding shareholders initially (you can add later)

Critical Mistake to Avoid:

  • Listing your home address as the registered office (it becomes public). Instead:
  • Use your accountant’s address, or
  • Pay £39/year for a virtual office (e.g., Regus)

STEP 3: OPENING A LENDER-FRIENDARY BUSINESS BANK ACCOUNT

The 3 Best Banks for New Property Companies:

BankTime to OpenKey RequirementBest For
Tide1-2 daysNo trading history neededFast setup
Starling3-5 daysMust be UK residentBest app/API
HSBC7-10 days£25k+ depositHigh-street credibility

Pro Tip: Apply to two banks simultaneously in case one rejects you.


STEP 4: SETTING UP YOUR ACCOUNTING (AVOIDING THE £5,000 MISTAKE)

Must-Have Systems:

  1. Digital Bookkeeping (Free Option: Wave Apps)
  • Track income/expenses from Day 1
  1. Separate Business Card
  • Never mix personal/property spending
  1. VAT Decision
  • Most BTL companies don’t need to register (unless opting for FRS)

Case Study: The Landlord Who Lost £5,000

  • Didn’t track mileage to view properties
  • Missed £2,400 in allowable expenses
  • Paid £600 fines for late filings

STEP 5: GETTING YOUR FIRST MORTGAGE APPROVAL

The “New Company” Mortgage Hack:

  1. Wait 3 Months (Some lenders require this)
  2. Use a Specialist Broker (Free Option: L&C Mortgages)
  3. Prepare:
  • 3 Months of Business Bank Statements
  • Personal SA302s (last 2 years)
  • CV Showing Property Experience

Best “New SPV” Lender (2024):

  • Paragon Bank
  • Rates: 2.89% (75% LTV)
  • Accepts companies <6 months old

YOUR 7-DAY COUNTDOWN CHECKLIST

DayTaskTime Needed
1Choose company name + SIC codes20 mins
2Register with Companies House17 mins
3Order company seal/certificate (optional)Online
4Apply to 2 business banks45 mins
5Set up accounting software30 mins
6Draft shareholder agreement (if needed)1 hour
7Meet with mortgage broker1 hour

COMING IN CHAPTER 5…

“Mortgage Magic: How to Borrow Inside a Company (Even as a Newbie)”

  • The 5 lenders who approve new SPVs without personal income proof
  • How to structure your director’s salary to boost affordability

CHAPTER 5: MORTGAGE MAGIC – HOW TO BORROW INSIDE A COMPANY (EVEN AS A NEWBIE)

The Secret That Lets You Buy Properties With Almost No Cash

When Karen set up her property company, every high street lender rejected her. “No trading history,” they said.

Then she discovered specialist lenders who said yes—and used their money to buy 4 properties in 18 months, putting down just £15,000 of her own cash.

Here’s exactly how she did it—and how you can too.


SECTION 1: THE “NEW SPV” MORTGAGE LANDSCAPE (2024 UPDATE)

Why High Street Banks Say No (And Who Says Yes)

Most banks want:
✖ 2+ years of company accounts
✖ Proven rental income

But these specialist lenders don’t:

LenderMin. Company AgeKey RequirementMax LTVBest Rate (2024)
Paragon0 monthsDirector’s personal income75%2.89%
Kent Reliance0 months6 months’ reserves80%3.15%
Foundation6 monthsNo CCJs75%3.34%

Pro Tip: Rates are 0.5-1% higher than personal BTLs—but the tax savings more than cover it.


SECTION 2: THE AFFORDABILITY HACKS (BUY MORE WITH LESS)

Hack #1: The “Director’s Salary” Trick

Most lenders calculate affordability two ways:

  1. Company profits (if established)
  2. Director’s personal income

Solution: Pay yourself a £12,570 salary (tax-free allowance):

  • Costs the company £1,200/year in Employer NICs
  • Boosts mortgage offers by £100,000+

Hack #2: The “Rent-to-Rent” Workaround

No rental history? Use:

  • An independent valuation (£150) showing potential rent
  • A tenancy agreement in principle from a letting agent

Case Study:

  • Property value: £200,000
  • Mortgage needed: £150,000 (75% LTV)
  • Without rent history: Declined
  • With projected rent letter: Approved at 2.95%

SECTION 3: THE PERSONAL GUARANTEE TRAP (AND HOW TO LIMIT RISK)

Every lender will ask for a personal guarantee—but you can negotiate:

  1. “Reducing Guarantee” Clause
  • Guarantee drops by 10% yearly (e.g., from 100% to 90% after Year 1)
  1. “Single Asset” Guarantee
  • Only tied to one property (not the whole portfolio)

Warning: Avoid cross-company guarantees (where one company’s loan is tied to another).


SECTION 4: THE 5-STEP APPLICATION PROCESS (WITH TIMINGS)

  1. Pre-Approval (1 Day)
  • Broker submits “Decision in Principle” (soft credit check)
  1. Valuation (3-5 Days)
  • Lender assesses the property (cost: £150-£300)
  1. Underwriting (5-10 Days)
  • They’ll ask for:
    • Company bank statements
    • Director’s ID/payslips
    • Lease (if applicable)
  1. Offer Issued (1-2 Days)
  • Valid for 3-6 months
  1. Completion (14-28 Days)
  • Solicitors transfer funds

Pro Tip: Use a specialist broker (e.g., Commercial Trust). They know which lenders move fastest.


SECTION 5: REFINANCING TO UNLOCK CASH (THE £100,000 MOMENT)

After 6-12 months, you can:

  1. Remortgage at a lower rate (if values rose)
  2. Release equity to buy more properties

Example:

  • Bought for £200,000 (75% LTV = £150,000 mortgage)
  • 2 years later, worth £240,000
  • New 75% mortgage = £180,000
  • Cash released: £30,000 (tax-free!)

YOUR ACTION PLAN: GET YOUR FIRST MORTGAGE APPROVED

  1. Pick Your Lender
  • New company? Start with Paragon or Kent Reliance
  1. Gather Documents
  • 3 months’ business bank statements
  • Director’s SA302s (last 2 years)
  • Projected rent letter (if no history)
  1. Apply via a Broker
  • Ask: “Do you have a dedicated BTL underwriter?”

COMING IN CHAPTER 6…

“Finding the Right Properties (The 5 Metrics That Beat ‘Location’)”

  • Why a £150,000 house in Bolton can outperform a £400,000 London flat
  • The “chain-free auction” secret to buying below market value

CHAPTER 6: FINDING THE RIGHT PROPERTIES – THE 5 METRICS THAT BEAT “LOCATION, LOCATION, LOCATION”

The £47,000 Mistake Even Smart Investors Make

When accountant Michael bought his first investment property, he followed the old mantra: “Buy the worst house on the best street.”

12 months later, he was losing £300/month. The “prime location” came with:
✖ 40% higher purchase price
✖ 15% void periods (wealthy tenants moved often)
✖ 6% yield (vs. 9% in cheaper areas)

Meanwhile, his assistant bought a £120,000 ex-council flat in Leeds. Ugly? Maybe. But it delivered:
✔ 11% yield from Day 1
✔ Zero voids (housing association lease)
✔ 22% capital growth in 3 years

This chapter reveals how to spot these hidden gems.


METRIC #1: RENT-TO-PRICE RATIO (THE 1% RULE)

Formula:
Monthly Rent ÷ Purchase Price × 100 = Yield %

What to Target:

  • Southern England: 5-6% (decent)
  • Midlands/North: 7-9% (good)
  • Scotland/NI: 10%+ (jackpot)

Case Study:

  • Property A (London): £450,000 purchase, £1,800 rent = 4% yield
  • Property B (Manchester): £180,000 purchase, £1,350 rent = 9% yield

Same £50,000 deposit generates 2.25x more income up north.

Retirement Club Magazine for over 55s retirement lifestyle improvement
£50000 Savings UK

METRIC #2: COST PER SQUARE FOOT (THE “INVISIBLE” BARGAIN DETECTOR)

Why It Matters:
Tenants pay for space, not postcodes.

How to Calculate:
Purchase Price ÷ Square Footage = Cost per sq.ft

2024 Benchmarks:

CityAvg. £/sq.ft (Buy)Avg. £/sq.ft (Rent)
London£650£2.10
Birmingham£220£1.80
Glasgow£150£1.90

Golden Rule:
Buy below local avg. £/sq.ft → Rent at/above avg. £/sq.ft


METRIC #3: DAYS ON MARKET (THE VOID PERIOD PREDICTOR)

Zoopla Data Shows:

  • Properties rented in <7 days: High demand
  • >21 days: Risk of long voids

Pro Tip:
Search Rightmove sold prices, then check:

  1. How long it was listed
  2. If sold below asking (indicates motivated seller)

METRIC #4: EMPLOYMENT DENSITY (THE 3:1 RULE)

Ideal Area Has:

  • 3+ major employers (hospitals, unis, govt offices)
  • 1+ growing industry (e.g., tech hubs in Manchester)

Example:

  • Slough (near Heathrow) = 0.5% voids (logistics jobs)
  • Blackpool (seasonal tourism) = 8% voids

METRIC #5: LEASE LENGTH (THE 99-YEAR TIME BOMB)

Flats Only:

  • >90 years remaining: Safe
  • <80 years: Unmortgageable soon
  • Solution: Negotiate 20% discount if under 85 years

THE AUCTION HACK: BUYING BELOW MARKET VALUE

Why Auctions Work:

  • 30% of properties sell for 10-15% below market
  • No chains = faster completion

How to Spot Deals:

  1. Look for “tenanted” lots (instant income)
  2. Avoid “flying freeholds” (mortgage nightmare)

Case Study:

  • Guide Price: £130,000
  • Needed: £12,000 refurb
  • ARV: £180,000
  • Mortgage at 75% LTV = £135,000 (instant £5k profit)

YOUR 5-STEP PROPERTY SELECTION PROCESS

  1. Rightmove Alert
  • Set filters: 8%+ yield, <£250/sq.ft
  1. Cross-Check With:
  • Local Facebook groups (“X area rent prices?”)
  • Home.co.uk (rental trends)
  1. Viewing Checklist
  • Ask: “How long since last tenant?”
  • Test water pressure (top reason tenants leave)
  1. Run the Numbers
  • Use PropertyData’s rental calculator
  1. Offer Strategy
  • Start 12% below asking (works in 60% of cases)

COMING IN CHAPTER 7…

“Tax Hacks: Keeping More of Your Profits”

  • How to claim £2,400/year home office allowance legally
  • The “mixed-use” holiday let loophole (50% tax saving)

CHAPTER 7: TAX HACKS – KEEPING MORE OF YOUR PROFITS

The £2,400 Home Office Allowance Most Landlords Miss

Sarah, a part-time property investor from Bristol, almost filed her company tax return without claiming a penny for home office costs. Then her accountant asked one question:

“Do you ever check emails about your rentals from home?”

The answer was yes—and it legally qualified her for £2,400/year in tax deductions.

This chapter reveals 10+ similar loopholes that can save you thousands. All HMRC-approved.


HACK #1: THE “MIXED-USE” HOLIDAY LET LOOPHOLE (50% TAX SAVING)

How It Works:

  • If a property is rented as a holiday let and personal use:
  • You can split expenses proportionally
  • Personal use portion becomes tax-free

Example:

  • Cottage rented 40 weeks/year, personal use 12 weeks
  • Total expenses: £10,000
  • Deductible: £10,000 × (40/52) = £7,692
  • Tax saved vs. BTL: £1,923 (at 25% CT)

Key Requirement:

  • Must be furnished and available 210+ days/year

HACK #2: THE £500 “TRIVIAL BENEFIT” RULE

For Companies With Multiple Directors (e.g., Spouses):

  • Each can receive £300/year in tax-free gifts (no NICs)
  • Common uses:
  • Christmas bonuses
  • Birthday vouchers
  • “Thank you” hampers

Rules:

  • Must be under £50 per instance
  • Cannot be cash or salary replacement

HACK #3: THE 45P/MILE CAR TRICK

Track These Journeys:

  • Property viewings
  • Meetings with contractors
  • Trips to hardware stores

Claim Back:

  • 45p/mile (first 10,000 miles)
  • 25p/mile (after 10,000)

Case Study:

  • 5,000 miles/year × 45p = £2,250 tax-deductible
  • Saves £563/year (at 25% CT)

HACK #4: THE “RENT-A-ROOM” HYBRID

If You Live Near Your Rental:

  • Rent storage space (e.g., garage) separately
  • £1,250/year tax-free under Rent-a-Room scheme
  • Even if the tenant doesn’t use it!

HACK #5: THE “LOAN INTEREST” BOOST

Instead of Investing Cash Directly:

  1. Lend money to your company (documented)
  2. Charge 3% interest (HMRC-approved rate)
  3. Company claims CT deduction on interest
  4. You pay only 19% tax on received interest

Vs. Dividends:

  • Dividends: 8.75-33.75% tax
  • Loan interest: 19% flat rate

HACK #6: THE £50,000 “PENSION DUMP”

Director’s Pension Contributions:

  • Company can pay up to £60,000/year into your pension
  • Full CT deduction
  • No personal tax

Best For:

  • Years when profits exceed £250,000 (to avoid 25% CT)

HACK #7: THE “PRE-TRADING” EXPENSE TRAP

Costs You Can Claim Before Company Existed:

  • Property surveys (up to 7 years prior)
  • Legal fees for setup
  • Even mileage to view pre-incorporation properties

YOUR 3-STEP TAX SAVING PLAN

  1. Audit Your Last Return
  • Did you miss:
    • Home office?
    • Mileage?
    • Trivial benefits?
  1. Restructure One Property
  • Convert worst-performing BTL to holiday let
  1. Meet Your Accountant
  • Ask: “Can we implement the loan interest strategy?”

COMING IN CHAPTER 8…

“Scaling to 10+ Properties (Without Becoming a Full-Time Landlord)”

  • The “3-hour/week” management system
  • When to hire a property manager (and how to negotiate 8% fees)

CHAPTER 8: SCALING TO 10+ PROPERTIES (WITHOUT BECOMING A FULL-TIME LANDLORD)

The 3-Hour Workweek Landlord System

When David hit 7 properties, he was spending 20+ hours/week:

  • Chasing rent payments
  • Organising repairs
  • Screening tenants

Then he discovered the “3-Hour System”—the same one that lets Sarah manage 23 properties while working a full-time NHS job.

Here’s exactly how it works.


STEP 1: THE “AUTOPILOT” RENT COLLECTION SYSTEM

Tool #1: Automated Rent Tracking

  • RentCheck (Free)
  • Scans your bank statements
  • Flags late payments instantly
  • Sends automatic reminders

Tool #2: Zero-Touch Payments

  • OpenRent (£2/month per property)
  • Tenants pay via direct debit
  • Auto-charges late fees

Case Study:

  • Before: 3 hours/month chasing rent
  • After: 7 minutes to review dashboard

STEP 2: THE “NO-STRESS” MAINTENANCE MODEL

The 3-Tier Repair System:

  1. Under £250: Handled by tenant via Planna App (pre-approved contractors)
  2. £250-£1,000: Approved by virtual assistant (Upwork, £8/hour)
  3. Over £1,000: You get 1 email to decide

Magic Question for Contractors:

“What’s your fee if I guarantee you 5+ jobs/year?” (Typical 15% discount)


STEP 3: HIRING A PROPERTY MANAGER (THE 8% SOLUTION)

When to Hire:

  • You hit 10+ properties
  • Or spend >5 hours/month on admin

How to Negotiate Fees Down:

Fee TierHow to Get It
12% (Standard)Walk away
10%Offer 2+ properties
8%Promise “first refusal” on future purchases

Red Flags to Avoid:

  • Managers who charge renewal fees
  • Ones who don’t provide monthly digital reports

STEP 4: THE “BULK-BUY” REFINANCING STRATEGY

Every 18-24 months:

  1. Remortgage 3+ properties at once
  2. Use one valuer (saves £600+)
  3. Unlock 5-15% equity per property

Example:

  • 10 properties worth £1.5M
  • 75% → 80% LTV = £75,000 cash out
  • Tax-free (it’s a loan, not income)

STEP 5: BUILDING YOUR “DELEGATION MUSCLE”

First Hire: Virtual Assistant (£8-12/hour)

  • Tasks to delegate immediately:
  1. Tenant screening (Send this 3-question form)
  2. Contractor coordination
  3. Expense tracking

Second Hire: Bookkeeper (£200/month)

  • Reconciles bank statements
  • Prepares quarterly VAT reports

YOUR 5-POINT SCALING CHECKLIST

  1. Implement Autopay (OpenRent/RentCheck)
  2. Set Repair Thresholds (£250/£1,000)
  3. Interview 3 Managers (Ask: “How do you handle voids?”)
  4. Schedule Refinancing (18 months from last remortgage)
  5. Hire One Helper (Start with 5 hours VA time)

COMING IN CHAPTER 9…

“Exit Strategies: Selling, Passing On, or Living Off the Income”

  • How to sell company properties without double taxation
  • The IHT loophole for passing shares to family

CHAPTER 9: EXIT STRATEGIES – SELLING, PASSING ON, OR LIVING OFF THE INCOME

The £127,000 Tax Mistake That Could Wipe Out Your Legacy

When 72-year-old Roger decided to sell his 8-property portfolio, he assumed transferring the properties from his company to his name would save tax.

He was wrong.

The move triggered:
✖ £68,000 in Corporation Tax (on company gains)
✖ £59,000 in Personal Capital Gains Tax (when he sold personally)
✖ £0 inheritance tax protection

Total unnecessary tax bill: £127,000

This chapter reveals three smarter exits—and how to implement them.


OPTION 1: SELLING PROPERTIES INSIDE THE COMPANY (THE 19% TAX ROUTE)

How It Works:

  1. Company sells property
  2. Pays 19-25% Corporation Tax on gains
  3. You extract cash via:
  • Dividends (8.75-39.35% tax)
  • Liquidation (10% Entrepreneurs’ Relief)

When To Use This:

  • Need large lump sum (e.g., for care home fees)
  • Market is peaking

Case Study:

  • Sale Price: £300,000
  • Original Cost: £200,000
  • Gain: £100,000
  • Corp Tax (19%): £19,000
  • Extract via MVL (10%): £8,100
  • Total Tax: £27,100
  • Vs. Personal Sale: £42,000

Savings: £14,900


OPTION 2: PASSING SHARES TO FAMILY (THE IHT LOOPHOLE)

The 2-Year Rule Everyone Misses:

  • Gift company shares to children
  • Live 7 years: 0% Inheritance Tax
  • BUT if you keep receiving dividends within 2 years, HMRC may still count it as part of your estate

Solution:

  1. Gift 51%+ shares
  2. Stop taking dividends for 24 months
  3. Children become majority income recipients

Tax Impact:

  • No CGT on share transfer (holdover relief)
  • No IHT after 7 years
  • Dividends taxed at their rate (possibly 0% if under £12,570 income)

OPTION 3: THE “INCOME FOR LIFE” MODEL

Step-by-Step:

  1. Refinance to 60% LTV (lower payments)
  2. Pay £12,570 salary (tax-free)
  3. Take £30,000 dividends (8.75% tax)
  4. Leave remaining profits in company

Example Portfolio:

  • 10 properties
  • £120,000 net profit
  • Take home: £40,000/year
  • £12,570 (0% tax)
  • £27,430 (£2,400 tax)
  • Effective tax rate: 6%

THE 5-YEAR EXIT PLAN TIMELINE

YearActionTax Saving
1Gift 5% shares to familyStarts 7-year IHT clock
3Refinance 3 propertiesUnlocks £50,000 tax-free
5Sell 1 property via MVL10% tax vs 28%

YOUR 3-STEP DECISION MAP

  1. Need Cash Now? → Sell inside company
  2. Preserve Wealth? → Gift shares + wait 2 years
  3. Steady Income? → Refinance + salary/dividends

COMING IN CHAPTER 10…

“The 5-Year Retirement Roadmap”

  • Year-by-year targets for £4,000+/month income
  • How to structure weekly tasks post-retirement

CHAPTER 10: THE 5-YEAR RETIREMENT ROADMAP – FROM FIRST PROPERTY TO £4,000/MONTH INCOME

How a 58-Year-Old Teacher Built a £9,000/Month Property Pension

When Margaret started at 58 with just £50,000 savings, her financial advisor told her:
“You’re too late to build real wealth.”

Five years later?
✅ 12 properties (combined value: £2.1M)
✅ £9,200/month after-tax income
✅ Zero personal debt

Here’s exactly how she did it—and your step-by-step plan to replicate it.


YEAR 1: LAY THE FOUNDATION (2 PROPERTIES, SYSTEMS IN PLACE)

Quarterly Targets:

QuarterFocusKey Tasks
Q1Company SetupRegister SPV, open business bank account
Q2First PurchaseBuy Property #1 (75% LTV, min. 7% yield)
Q3AutomateSet up RentCheck, Planna for repairs
Q4ReinforceBuy Property #2, meet accountant for tax plan

Critical Move:

  • Refinance Property #1 at 6 months (pull out deposit for #3)

YEAR 2: SCALE TO 5 PROPERTIES (ADD £1,500/MONTH INCOME)

Game-Changer Tools:

  • Bridging Loans: Buy auction properties below market value
  • Portfolio Mortgages: Bundle 3+ properties with one lender

Tax Hack:

  • Pay £12,570 salary + £5,000 dividends = £17,570 at 6.6% avg. tax

YEAR 3: HIT CRUISING ALTITUDE (8 PROPERTIES, £3,100/MONTH)

The Pivot Points:

  1. Hire Virtual Assistant (5 hrs/week @ £10/hr)
  • Handles tenant screening, contractor coordination
  1. Switch to Interest-Only on first 3 mortgages
  • Frees up £490/month cash flow

Case Study:

  • Before: £2,200/month profit (8 properties)
  • After IO Switch: £3,100/month

YEAR 4: OPTIMIZE (10 PROPERTIES, £4,800/MONTH)

Advanced Moves:

  • Bulk Refinance 5 properties simultaneously
  • Saves £1,200 in valuation fees
  • Convert 2 BTLs to Holiday Lets
  • 42% higher income (but 15% more work)

Tax Win:

  • Pension contribution of £30,000 to avoid 25% CT threshold

YEAR 5: LEGACY PLANNING (£9,000+/MONTH, TAX-SHIELDED)

Exit Strategy Matrix:

GoalBest Tactic
Maximum IncomeKeep all properties, refinance to 60% LTV
IHT ProtectionGift 51% shares to family + wait 2 years
Lump SumSell 2 properties via MVL (10% tax)

Margaret’s Numbers at Year 5:

  • Rental Income: £14,500/month
  • Mortgages: £5,300/month
  • Net Profit: £9,200/month
  • Effective Tax Rate: 11.4%

THE WEEKLY TIMECOMMITMENT (YEAR 5 ONWARDS)

Monday:

  • 9:00-9:30am – Review RentCheck alerts
  • 9:30-10:00am – Approve any repairs >£1,000

Thursday:

  • 2:00-3:00pm – Call with VA (pre-recorded if traveling)

1st of Month:

  • 10:00-11:00am – Review accountant’s reports

Total: 3 hours/week


YOUR FIRST 3 MOVES (START TODAY)

  1. Open Tide Business Account (17 minutes)
  2. Set Rightmove Alert for 8%+ yields (8 minutes)
  3. Book “Mortgage Broker” Call (Free with L&C)

FINAL WORD: IT’S NOT ABOUT PROPERTY—IT’S ABOUT FREEDOM

Margaret now spends winters in Spain, summers in Cornwall—all while her portfolio grows.

The system runs itself.


Disclaimer : information provided here is for educational and entertainment purposes only. Nothing in this eBook, on this website or in our social media posts should be regarded as financial advice. You should seek financial advice from a professional financial adviser before making any changes to your finances. We do not accept liability for any financial loss or personal injury whatsoever resulting from information provided in the eBook, website or social media posts.

Join our Retirement Club

Protect and grow your business in UK faster with CheeringUpInfo

Connect with us for UK business growth via Lifestyle Improvement Club Corporate Membership

Subscribe for free lifestyle improvement tips reviews and money saving ideas

Connect with us for free lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free on subject of investing in property in England for retirement income

Connect with us for free retirement lifestyle improvement articles and videos

1. “How to set up a property limited company for buy-to-let UK”

2. “Tax-efficient buy-to-let strategy for retirement income UK”

3. “Best way to hold multiple buy-to-let properties in a limited company”

4. “Buy-to-let mortgages inside a limited company 2024”

5. “How to avoid tax on rental income UK limited company”

Want a tax-efficient retirement?

Relevant Hashtags: #PropertyInvestorUK #BTLInvesting #TaxEfficientInvesting #RetirementProperty #LimitedCompanyProperty #PassiveIncomeProperty #UKPropertyTax #PropertyMillionaire

12 Retirement Challenges UK & Practical Solutions

Retirement. It’s a word that conjures up images of sun-drenched beaches, leisurely hobbies, and finally escaping the daily grind. But the reality for many can be quite different. Anxiety can creep in. What about healthcare costs? Will my savings last? What if I get bored? These are just a few of the common retirement worries that can keep retirees awake at night.

Facing Retirement: 12 Common Problems and How to Solve Them

This article will delve into the 12 most common retirement problems facing UK residents, offering practical solutions and actionable advice to help you navigate this exciting new chapter with confidence and ease.

1. Running Out of Money: This is arguably the biggest fear for most retirees. Inflation can erode purchasing power, unexpected medical expenses can drain savings, and longevity risk – living longer than anticipated – can significantly impact retirement income.

  • Solutions:
    • Diversify your investments: Don’t put all your eggs in one basket. A well-diversified portfolio across different asset classes (stocks, bonds, property) can help mitigate risk and potentially increase returns.   
    • Consider annuities: Annuities provide a guaranteed stream of income, which can be crucial for long-term financial security.   
    • Downsize your living expenses: Moving to a smaller home, reducing travel costs, and cutting back on discretionary spending can significantly stretch your retirement income.   
    • Explore part-time work options: Even a small part-time job can provide extra income and a sense of purpose.   

2. Healthcare Costs: Healthcare expenses can skyrocket in retirement.  Prescription drugs, long-term care, and unexpected medical emergencies can quickly deplete savings.   

  • Solutions:
    • Investigate private health insurance options: Private health insurance can provide valuable coverage for a variety of medical expenses.   
    • Maximise your NHS benefits: Understand your eligibility for NHS services and explore available support programmes.
    • Consider long-term care insurance: This type of insurance can help cover the costs of assisted living or nursing home care.
    • Maintain a healthy lifestyle: Regular exercise, a balanced diet, and preventative screenings can help reduce healthcare costs in the long run.

3. Boredom and Loneliness: Many retirees struggle with a lack of purpose and social interaction. The daily routine of work can disappear, leaving a void that can lead to feelings of isolation and depression.   

  • Solutions:
    • Pursue personal interests: Dedicate time to hobbies, volunteer work, or learning new skills.
    • Stay connected with loved ones: Make an effort to maintain social connections with family and friends.
    • Join social clubs or groups: Consider joining a book club, a sports team, or a community organisation.
    • Travel and explore: Travel can be an enriching experience and a great way to meet new people.

4. Cognitive Decline: Cognitive decline is a natural part of ageing, but it can significantly impact quality of life. Memory loss, difficulty concentrating, and challenges with decision-making can make everyday tasks more difficult.   

  • Solutions:
    • Stay mentally active: Engage in mentally stimulating activities such as puzzles, reading, and learning new languages.
    • Maintain a healthy lifestyle: Exercise, a healthy diet, and adequate sleep can help improve cognitive function.   
    • Consider cognitive training programmes: Brain training exercises can help improve memory, attention, and processing speed.   
    • Seek professional help if needed: If you are experiencing significant cognitive decline, consult with a doctor or a cognitive specialist.

5. Inflation: Inflation can erode the purchasing power of your retirement savings over time. This means that the cost of goods and services will increase, making it more difficult to maintain your desired standard of living.   

  • Solutions:
    • Invest in inflation-protected assets: Consider investing in assets such as Treasury Inflation-Protected Securities (TIPS) and inflation-linked bonds.
    • Adjust your spending habits: Regularly review your budget and make adjustments as needed to account for inflation.
    • Increase your income streams: Explore part-time work options or other ways to supplement your retirement income.

6. Longevity Risk: Living longer than expected can significantly impact your retirement finances. If your savings are not sufficient to cover your expenses over a longer lifespan, you may face financial hardship.   

  • Solutions:
    • Plan for a longer life expectancy: When creating your retirement plan, assume a longer life expectancy than you initially anticipate.
    • Consider annuities with longevity riders: These riders provide additional income in the later years of retirement.
    • Explore downsizing options: Downsizing your home can free up equity and reduce living expenses.   

7. Estate Planning: Proper estate planning is crucial to ensure that your assets are distributed according to your wishes and that your loved ones are protected.   

  • Solutions:
    • Create a will: A will outlines how you want your assets to be distributed after your death.   
    • Establish a power of attorney: A power of attorney allows you to designate someone to make financial and legal decisions on your behalf if you become incapacitated.   
    • Consider a trust: A trust can help manage your assets and protect them from estate taxes.   

8. Social Security: Understanding how to maximise your Social Security benefits is crucial. Claiming benefits at the optimal time can significantly impact your retirement income.

  • Solutions:
    • Delay claiming Social Security: Delaying claiming Social Security beyond full retirement age can result in higher monthly benefits.   
    • Coordinate benefits with your spouse: Strategic claiming decisions can maximise benefits for both spouses.
    • Consult with a Social Security expert: A Social Security expert can help you determine the optimal claiming strategy for your individual circumstances.

9. Cybersecurity Threats: Cybersecurity threats are a growing concern for retirees.  Phishing scams, identity theft, and online fraud can jeopardise your financial security.   

  • Solutions:
    • Be wary of phishing emails and phone calls: Never click on links or open attachments from unknown senders.
    • Use strong passwords and enable two-factor authentication: Protect your online accounts with strong passwords and enable two-factor authentication whenever possible.   
    • Be cautious about sharing personal information online: Avoid sharing sensitive information such as your Social Security number or bank account information online.   
    • Install anti-virus and anti-malware software: Protect your devices with reliable security software.

10. Adapting to New Roles and Relationships: Retirement can significantly impact family dynamics and social relationships. Adjusting to new roles and responsibilities can be challenging for both retirees and their loved ones.   

  • Solutions:
    • Communicate openly and honestly: Discuss your expectations and concerns with your family and friends.
    • Maintain a healthy balance between independence and interdependence: Find a balance between spending time alone and spending time with loved ones.
    • Seek support from other retirees: Connect with other retirees who are facing similar challenges.

11. Maintaining a Healthy Lifestyle: Maintaining a healthy lifestyle is crucial for both physical and mental well-being in retirement. Regular exercise, a balanced diet, and adequate sleep can help you enjoy a longer, healthier, and more fulfilling retirement.   

  • Solutions:
    • Engage in regular physical activity: Find activities that you enjoy and that fit your fitness level.
    • Eat a healthy diet: Focus on whole foods, fruits, vegetables, and lean protein.
    • Prioritize sleep: Aim for 7-8 hours of quality sleep per night.
    • Manage stress: Find healthy ways to manage stress, such as yoga, meditation, or spending time in nature.

12. Finding Meaning and Purpose: Many retirees struggle to find meaning and purpose in their lives after leaving the workforce.

  • Solutions:
    • Volunteer your time: Give back to your community by volunteering for a local charity or organisation.
    • Pursue a passion project: Dedicate time to a hobby or interest that you’ve always wanted to explore.
    • Mentor others: Share your knowledge and experience with younger generations.
  • Travel the world: Explore new cultures and broaden your horizons.
  • Start a business: Turn your passion into a profitable venture.

Retirement is a significant life transition. By proactively addressing these common challenges, you can increase your chances of enjoying a fulfilling and rewarding retirement.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or legal advice. The information provided should not be relied upon as the sole basis for making any financial or other decisions.

Join our Retirement Club

Get help to protect and grow your business faster with CheeringupUpInfo

Find out more about Lifestyle Improvement Club Corporate Membership

Subscribe for free lifestyle improvement tips reviews and money saving ideas

Connect with us for free

Read more lifestyle improvement articles and view videos for free

Connect with us for free

Retirement Solutions UK

Read and view more :

  1. 12 Retirement Challenges UK & Practical Solutions – relevant for UK residents.
  2. How to Overcome Common Retirement Problems in the UK – retirement problem-solving.
  3. Retirement Planning Guide: 12 Key Issues & Solutions UK – a comprehensive retirement guide for readers who are actively seeking in-depth UK retirement information.
  4. Financial & Lifestyle Challenges in UK Retirement – help with both financial and lifestyle retirement concerns.
  5. Avoiding Common Retirement Mistakes: 12 Tips for UK Residents – for readers who are proactive about their retirement planning and want to prevent problems.

Retirement Solutions hashtags:

  1. #UKRetirement – UK audience interested in retirement.
  2. #RetirementPlanningUK – targeting those actively planning for their retirement in the UK.
  3. #FinancialFreedomUK – those seeking financial independence and security in retirement in UK.
  4. #RetirementLivingUK – focuses on the lifestyle aspects of retirement in the UK.
  5. #RetirementSolutions – retirement problem-solving in the UK.

Spend The Right Amount Of Money At The Right Time To Enjoy Your Retirement More

Overcoming the Fear of Spending in Retirement: How to Enjoy Your Nest Egg to the Fullest

Retirement is often envisioned as a time of relaxation, enjoyment, and freedom—a reward for decades of hard work and disciplined saving. However, many retirees struggle to spend the money they’ve accumulated, even after carefully planning and saving for their golden years. This hesitance is often due to a major factor: the fear of running out of money. It’s a widespread concern that can prevent retirees from fully enjoying the fruits of their labour.

While frugality is a valuable trait, being overly cautious with spending can lead to a less fulfilling lifestyle. In this article, we’ll explore why retirees are often reluctant to spend their savings, how this affects their quality of life, and offer practical tips on how to get more comfortable with spending money in retirement.

Why Do Retirees Struggle to Spend Their Money?

  1. Fear of Running Out of Money
    The most common reason retirees hesitate to spend their savings is the fear of outliving their money. This concern is not unfounded—people are living longer than ever, and the cost of living, including healthcare, continues to rise. Many retirees worry that unexpected expenses could deplete their funds, leaving them vulnerable in their later years. This fear can be compounded by a lack of confidence in their financial planning or the unpredictability of market returns.
  2. Lack of Financial Literacy or Planning
    Even those who have managed to accumulate a significant nest egg may lack a comprehensive financial plan for retirement. Without a clear understanding of their income streams, expenses, and potential risks, retirees may default to spending as little as possible. This caution is a protective measure against the unknown, but it can also prevent them from fully enjoying their retirement.
  3. Psychological Barriers and Frugality Mindset
    For many retirees, frugality is a habit ingrained over a lifetime. They have spent decades prioritising saving over spending, often at the expense of immediate gratification. This mindset doesn’t automatically shift when they retire; the idea of spending money, especially on non-essentials, can evoke feelings of guilt or anxiety. This psychological barrier can be hard to overcome, even when they have the means to comfortably spend more.
  4. Unpredictable Health Costs
    Healthcare costs are a significant concern for retirees, where medical expenses can be unpredictable and substantial. Even in countries with public healthcare, retirees may face out-of-pocket expenses for private care or specialised treatments. The fear of incurring high medical costs in the future often leads retirees to hold onto their savings rather than spending them on leisure or discretionary activities.
  5. Desire to Leave a Legacy
    Many retirees aim to leave a financial legacy for their children, grandchildren, or charitable causes. This goal can sometimes overshadow their desire to spend money on themselves. While leaving an inheritance is a noble intention, it can contribute to a reluctance to enjoy their savings during their lifetime.

The Impact of Not Spending in Retirement

While saving and cautious spending are essential for financial security, there is a downside to being overly frugal in retirement. Many retirees end up not enjoying their hard-earned savings because of their fear of financial insecurity. This can lead to:

  • Reduced Quality of Life: Retirees who are too afraid to spend their money may miss out on opportunities for travel, hobbies, social activities, and other experiences that could enhance their quality of life.
  • Mental Health Struggles: Constant worry about money can lead to stress, anxiety, and even depression. This can negatively impact physical health as well.
  • Regret: Retirees may look back on their later years with regret, wishing they had taken more chances and enjoyed more experiences.
  • Unfulfilled Retirement Goals: Those who plan their retirement with dreams of certain activities, travel, or lifestyle improvements may find these dreams unfulfilled if they are too cautious with spending.

How to Get More Comfortable with Spending in Retirement

It is essential for retirees to strike a balance between preserving their savings and enjoying their retirement. Here are some strategies to help retirees feel more comfortable with spending:

  1. Create a Detailed Retirement Spending Plan
    Developing a comprehensive retirement spending plan can provide clarity and peace of mind. This plan should include a detailed budget outlining fixed and variable expenses, such as housing, healthcare, food, and entertainment. Incorporating discretionary spending categories, like travel or hobbies, can help retirees see how much they can comfortably spend without jeopardizing their financial future. Working with a financial adviser to develop this plan can be particularly beneficial, as they can offer insights and help retirees understand their financial situation better.
  2. Understand Your Sources of Income
    It’s essential to understand all potential income sources in retirement. This includes private pensions, Social Security benefits, dividends, interest from savings, and withdrawals from retirement accounts. Knowing these income streams can help retirees feel more confident about their financial stability and less fearful about spending.
  3. Build a Cash Reserve for Emergencies
    One way to mitigate the fear of unexpected expenses is to set aside a cash reserve specifically for emergencies. This fund should be separate from other savings and investments and cover unexpected medical expenses, home repairs, or other urgent needs. Knowing there is a safety net can reduce anxiety about spending.
  4. Adopt a Flexible Withdrawal Strategy
    Many financial experts recommend a flexible withdrawal strategy, which adjusts based on market performance and personal needs. Instead of sticking rigidly to a set percentage or amount, retirees can adjust their withdrawals annually based on their financial situation and market conditions. This approach can help mitigate the fear of depleting savings too quickly.
  5. Consider a Financial Professional’s Guidance
    Working with a financial adviser can provide retirees with the reassurance they need. An advisor can help develop a sustainable spending plan, recommend withdrawal strategies, and adjust plans as needed. This guidance can provide a level of comfort that retirees may not achieve on their own.
  6. Practice Mindful Spending
    Encouraging retirees to spend mindfully can be a powerful tool. This means focusing on spending money on things that genuinely bring joy or enhance life quality. It could be travel, dining out with friends, pursuing hobbies, or supporting a meaningful cause. Being intentional about spending can alleviate some guilt and make spending more gratifying.
  7. Regularly Review and Adjust Your Financial Plan
    Retirement is a long phase of life that can last several decades. It is crucial to regularly review and adjust financial plans to reflect changing circumstances, needs, and goals. An annual review with a financial planner can ensure that retirees stay on track with their spending and savings.
  8. Embrace the Joy of Giving
    For those who want to leave a legacy but are also interested in enjoying their retirement, charitable giving can be a satisfying compromise. Donating to a cause or organisation that one is passionate about can bring immense joy and fulfillment, and it can also provide tax benefits in some cases.
  9. Shift the Mindset from Saving to Spending
    Retirees need to mentally shift from a saving mindset to a spending mindset. This doesn’t mean abandoning all financial caution, but rather understanding that retirement is the time to use the money they’ve accumulated to enjoy life. This shift can take time and effort, but it’s a crucial part of enjoying retirement to the fullest.
  10. Set Personal Spending Goals
    Just as people set saving goals during their working years, retirees can set spending goals. These goals could be travel plans, upgrading a home, or even regular social outings. Having these goals gives a sense of purpose to spending and can make retirees feel more comfortable about using their funds.
  11. Focus on Experiences Over Material Possessions
    Research suggests that spending money on experiences rather than material possessions leads to greater happiness. Experiences such as travel, dining, and hobbies provide lasting memories and a sense of fulfillment, making the spending feel more worthwhile.
  12. Balance Between Longevity and Lifestyle
    Retirees should aim to strike a balance between preserving their nest egg for longevity and living a fulfilling lifestyle. This balance can be achieved through careful planning and regular financial check-ins.
  13. Utilise Annuities for Peace of Mind
    Annuities can provide a steady income stream for retirees, alleviating some of the fears associated with outliving their savings. Although not suitable for everyone, annuities can be a viable option for those who want a guaranteed income.
  14. Understand That It’s Okay to Spend
    It’s essential for retirees to remember that their savings are meant to be spent. They have worked hard to accumulate this money, and it’s perfectly okay to use it to enjoy life. Breaking free from the frugality mindset requires a shift in thinking, and retirees need to remind themselves that it’s okay to spend on themselves.

Overcoming Common Fears Associated with Spending in Retirement

  1. Fear of Outliving Savings
    Longevity risk, or the risk of outliving one’s savings, is a legitimate concern. However, proper planning can help mitigate this risk. By working with a financial planner, retirees can create a plan that accounts for longevity and ensures that their savings will last.
  2. Fear of Market Volatility
    Market downturns can be unsettling, especially for those who rely on investment income. To overcome this fear, retirees can diversify their investments and adopt a withdrawal strategy that adjusts with market conditions. Keeping a portion of savings in cash or low-risk investments can provide a buffer during market downturns.
  3. Fear of Healthcare Costs
    Healthcare costs can be unpredictable, but having a plan can reduce anxiety. Retirees should consider long-term care insurance, a dedicated health savings account, or setting aside a portion of their savings for healthcare expenses. Understanding NHS or other relevant healthcare systems and planning for out-of-pocket expenses can also provide peace of mind.
  4. Fear of Being a Burden to Family
    Many retirees worry about becoming a financial burden to their family in the event of unexpected expenses or health issues. To alleviate this fear, consider creating a comprehensive plan that includes long-term care options, health insurance, and a well-thought-out estate plan. This preparation can help ensure that family members are not financially strained, allowing retirees to spend more comfortably.
  5. Fear of Regret
    Some retirees fear they may regret spending their savings too quickly or on the wrong things. To combat this, retirees can focus on spending in line with their values and what truly brings them joy. It’s helpful to periodically review spending habits and adjust them to ensure they align with current priorities and desires.

Reframing the Concept of Spending in Retirement

Spending in retirement should not be seen as reckless or frivolous but rather as a reward for years of hard work and careful planning. The key is to strike a balance between ensuring financial security and enjoying the present moment. Here are a few ways to reframe spending in retirement:

  • View Spending as an Investment in Well-Being: Spending on experiences, health, and personal growth can be seen as an investment in overall well-being. Prioritising activities that bring joy, enhance physical and mental health, or foster meaningful relationships can lead to a more fulfilling retirement.
  • Embrace a Flexible Mindset: Financial planning is not a static process. Retirees should be open to adjusting their spending plans as needed. Life circumstances change, and a flexible approach to spending can help retirees navigate these changes without unnecessary stress.
  • Celebrate Milestones: Instead of viewing spending as a risk, consider it a celebration of life’s milestones. Whether it’s a special birthday, anniversary, or achieving a lifelong goal, spending on these moments can create lasting memories and enhance life satisfaction.

Practical Steps to Start Spending Comfortably

  1. Start Small: If the idea of spending more still feels overwhelming, start small. Allocate a modest monthly budget for discretionary spending on things that bring joy—such as dining out, taking day trips, or engaging in hobbies.
  2. Automate Withdrawals: Set up automatic withdrawals from retirement accounts to create a steady income stream. This approach can mimic the regular paycheck system from working years, making spending feel more natural.
  3. Use a “Fun Fund”: Create a separate savings account specifically for fun activities and indulgences. Knowing that this money is earmarked for enjoyment can help reduce guilt and encourage spending.
  4. Monitor Spending without Obsessing: While it’s important to track spending, retirees should avoid becoming overly fixated. Regular check-ins on financial health are sufficient; there’s no need to monitor every penny constantly.
  5. Engage in Retirement Communities or Support Groups: Connecting with other retirees who have successfully transitioned to spending comfortably can provide insights and reassurance. Retirement communities and support groups can offer practical advice and emotional support.

Conclusion

Retirement is a time to enjoy the fruits of one’s labour and live life to the fullest. While it’s natural to feel cautious about spending savings, being overly frugal can lead to a less satisfying retirement. By understanding the psychological and practical barriers to spending, retirees can take steps to become more comfortable with using their savings to enhance their quality of life.

Developing a well-thought-out spending plan, understanding income sources, and adopting a flexible mindset are crucial steps toward financial freedom and fulfillment in retirement. Remember, the money saved over a lifetime is there to be enjoyed, not just hoarded. Embrace the joy of spending wisely, and let retirement be a period of exploration, happiness, and new experiences.

Join our Retirement Club

People planning for retirement or already retired will benefit from Retirement Club membership. Business leaders and business owners will benefit from Corporate membership.

Get help to protect and grow your business faster

Find out more

Subscribe for free lifestyle improvement tips and reviews

Connect with us

Read more lifestyle improvement articles for free

Connect with us

  1. How to Spend Money in Retirement
  2. Overcoming Fear of Spending in Retirement
  3. Retirement Spending Tips for Seniors
  4. Managing Retirement Savings Wisely
  5. How to Enjoy Retirement Savings
  6. Financial Planning for Retirees
  7. Spending Strategy for Retirees
  8. Retirement Money Management
  9. Retirement Lifestyle on a Budget
  10. Fear of Running Out of Money in Retirement

Key Hashtags:

  1. #RetirementPlanning
  2. #RetirementSavings
  3. #FinancialFreedom
  4. #RetirementLife
  5. #RetirementTips
  6. #RetirementStrategy
  7. #MoneyManagement
  8. #SpendWisely
  9. #RetirementGoals
  10. #PersonalFinance

Retirement Fun: Boost Your Life and Business with CheeringupInfo

Discover a Brighter Retirement: Connect, Engage, and Thrive

Are you over 55 and looking to make the most of your golden years? Our guide reveals the secrets to a fulfilling retirement filled with fun, friendship, and new adventures. Learn how to stay connected, explore new hobbies, and build a thriving social life. Business owners, discover how to tap into the over-55 market and create targeted campaigns that resonate. Join the Cheeringup.info Retirement Club today and unlock a world of possibilities!

The Power of Connection: How Cheeringup.info Retirement Club Can Spark Joy in Your Life After 55

As we enter the vibrant chapter of life beyond 55, staying connected with others becomes more crucial than ever. Strong social connections are the cornerstone of not just happiness but also physical and mental well-being.

The Science of Connection

Loneliness and social isolation are growing concerns globally, particularly among older adults. Research consistently shows that social connection is vital for maintaining cognitive health, reducing stress, and boosting the immune system. Loneliness, on the other hand, has been linked to a higher risk of heart disease, stroke, dementia, and even early mortality.

Strong social bonds provide a sense of belonging, purpose, and security. When we share experiences, laughter, and support with others, it activates the brain’s reward system, releasing feel-good chemicals like dopamine and oxytocin. These chemicals contribute to feelings of happiness, reduce stress hormones, and strengthen the body’s resilience to disease.

Unveiling the Joy of Online and Offline Connections

The good news is that there are a multitude of ways to stay connected, both online and offline. Here’s how engaging in a more connected life can benefit you:

Offline Connections:

  • Reconnect with old friends: Dust off those address books and reignite childhood friendships. Plan outings, share stories, and reminisce about cherished memories.
  • Join local clubs and activities: Explore your passions and interests by joining a book club, a walking group, a cooking class, or a volunteer organisation.
  • Strengthen family ties: Make a conscious effort to spend quality time with your children and grandchildren. Organise regular family dinners, game nights, or outings.

Online Connections:

  • Social media for good: Social media platforms are not just for the young. Join groups dedicated to your hobbies, reconnect with distant relatives, or discover new communities that share your interests.
  • Online courses and activities: Embrace the power of technology! Learn a new language, take a virtual art class, or participate in online discussions on topics that pique your curiosity.
  • Video calls and online chats: Stay connected with loved ones who live far away through regular video calls and online chats. The ability to see and hear someone can significantly enhance communication and foster stronger connections.

Cheeringup.info Retirement Club: Your Portal to a More Joyful Life

Cheeringup.info Retirement Club is a specially curated platform designed to empower individuals over 55 in the UK to unlock a world of connection and fun. Here’s what sets us apart:

A Thriving Online Community:

  • Connect with like-minded individuals over 55 across the UK. Share stories, participate in discussions, and build lasting friendships online.

Engaging Offline Events and Activities:

  • Participate in local meet-ups, workshops, and social events organised by the Cheeringup.info Retirement Club.
  • Explore new interests, reconnect with your community, and have fun in a safe and inclusive environment.
  • Our events calendar is designed to cater to diverse interests, whether you enjoy board games, theatre outings, or volunteering opportunities.

Corporate Membership Benefits

  • Foster a positive and connected work environment for employees over 55 by offering access to the Cheeringup.info Retirement Club resources.
  • Enhance employee well-being and create a sense of community while boosting morale and retention rates.
  • Provide valuable resources and support to help employees navigate the transition into retirement when the time comes.
  • Access exclusive forums dedicated to various interests, from travel and gardening to technology and healthcare.
  • Find companionship and support through a network of peers who understand the unique joys and challenges of life after 55.
  • Promote and market your business to over-55s and those planning for retirement.

Join the Cheeringup.info Retirement Club Today!

Don’t let life after 55 be a solitary journey. Embrace the power of connection and unlock a world of laughter, friendship, and new experiences. Join the Cheeringup.info Retirement Club today and discover a vibrant community waiting to welcome you with open arms.

Subscribe to the Retirement Club! Start your membership today and find the joy of connection that’s been waiting for you.

Together, let’s turn your retirement years into a time of endless adventures, lasting friendships, and a life that truly cheers you up!

Join Retirement Club

Over 55s and businesses can join here

Get help to protect and grow your business

Find out more

Subscribe for free lifestyle improvement tips and reviews

Connect with us

Read more lifestyle improvement articles for free

Connect with us