Discover 10 hidden UK retirement problems for over 55s and under-55s planning ahead—from pension gaps and property wealth to caregiving, digital exclusion, loneliness and scams. CheeringUpInfo Retirement Club recommends becoming a member as the solution to the problems you didn’t know existed.
CheeringupInfo Retirement Club recommends becoming a member as the solution to the problems you didn’t know existed for the over 55s in the UK! For many in this demographic, the retirement landscape is not what they expected. “The latest ONS data puts the median pension pot for someone aged 55 to 64 at just £107,000,” and “43% of working age people are heading for a shortfall” . These are not just numbers; they represent a quiet crisis. Below, we explore ten emerging problems—from housing and health to digital exclusion and financial insecurity—that many over-55s and those planning for retirement are facing without realising the full extent. As you read, consider how a single, trusted source of guidance and community could address not just one, but all of these challenges.
What Hidden Financial Insecurity Is Affecting the Over 55s in the UK?
Hidden financial insecurity is affecting the over 55s in the UK through inadequate pension pots, a growing retirement savings gap, and widespread confusion about how to access and manage retirement funds. The problem is not just about having enough money—it is about not knowing what you have, what you will need, or what to do next.
Why Are So Many Over 55s Unprepared for Retirement Despite Decades of Saving?
Many over 55s are unprepared for retirement because of low median pension pots, a lack of clear retirement income goals, and a widespread failure to seek advice. The figures are stark:
- Median pension pot for 55–64-year-olds is just £107,000, which provides roughly £22 a day after essentials .
- 38% of over-55s have no plan for the tax-free cash from their pension.
- 41% of those aged 55–65 have no financial plan for later life.
- 43% of adults over 55 took no advice or guidance at all when accessing pension savings .
- Only 51% of baby boomers are on track to meet their retirement goals, and among those without defined benefit pensions, the figure drops to just 28% .
- The gender pension gap means women aged 55–59 hold roughly half of what men have.
Why Is Hidden Debt Threatening Retirement Security for the Over 50s?
Hidden debt is threatening retirement security for the over 50s because a significant proportion are still paying off mortgages and carrying unsecured debt well into later life. The data reveals:
- 1 in 7 over-50s still have a mortgage, with average monthly repayments of £887, rising to £1,230 in London .
- 48% of over-50s have some form of debt, from credit cards to personal loans .
- 26% of retirees now have unsecured debt, with an average balance of £1,750 .
- Nearly one in five over-55s on low incomes cannot retire because of housing costs.
- 15% of older people say their housing situation makes it harder to care for others.
Why Is Property Wealth Failing to Solve Retirement Income Shortfalls?
Property wealth is failing to solve retirement income shortfalls because although over-55s hold £3.7 trillion in property equity, many are either unaware of how to access it or reluctant to do so. The facts show:
- Over-55s hold 68% of the UK’s total private housing equity—£3.7 trillion.
- Those aged 55–64 hold £1.4 trillion, the largest share among all cohorts .
- Unlocking property wealth can top up retirement income, but many do not know how to do it tax-efficiently .
- The freeze on Inheritance Tax thresholds is tipping more estates into paying tax, making the timing of property wealth decisions critical .
What Overlooked Health and Caregiving Burdens Are Impacting the Over 55s?
Overlooked health and caregiving burdens are impacting the over 55s through rising mobility problems, mental health declines, and unpaid caring responsibilities that fall disproportionately on this age group.
Why Are Health Problems Quietly Pushing Over 55s Out of Work?
Health problems are quietly pushing over 55s out of work because of the strong link between poor health, low wealth, and early labour market exit. The evidence shows:
- 18% of men and 22% of women in the poorest third of the wealth distribution are out of work due to permanent sickness or disability, compared with less than 5% for middle and high wealth groups .
- 54% of women aged 55–64 in the lowest wealth third report at least one mobility problem, compared with 20% in the wealthiest third .
- Depressive symptoms among the poorest women aged 55–64 have risen from around 30% in the mid-2010s to 39% in 2023–24.
- 59% of people aged 55–64 say a long-term condition reduces their ability to carry out day-to-day activities.
Why Is Unpaid Caregiving Falling Disproportionately on the Over 55s?
Unpaid caregiving is falling disproportionately on the over 55s because they are the largest cohort of carers, with many providing 50 or more hours of care per week while managing their own health and finances. The statistics are revealing:
- 16.5% of people aged 55–59—666,535 individuals—provide unpaid care.
- 26% of carers in England are aged 55–64, the largest age band .
- 1 in 5 women aged 55–59 in England are unpaid carers.
- The number of over-65s providing unpaid care nearly doubled during the pandemic to over 4 million.
What Digital and Social Exclusion Is Silently Disadvantaging the Over 55s?
Digital and social exclusion is silently disadvantaging the over 55s through a combination of limited internet access, lack of digital skills, and rising loneliness that isolates them from essential services and community support.
Why Is Digital Exclusion Leaving Millions of Over 55s Behind?
Digital exclusion is leaving millions of over 55s behind because a significant proportion lack basic internet skills and face an increasingly “digital first” world for essential services. The data is compelling:
- 2.4 million older people (19%, nearly one in five) have limited use of the internet, using it less than once a month or not at all .
- 4.7 million people aged 65+ lack the basic skills needed to use the internet successfully.
- 31% of older people say poor IT skills prevent them from going online, and 22% cite lack of trust .
- 33% of older people (4.3 million) don’t use a smartphone, and 12% (1.6 million) don’t use a mobile phone at all .
Why Is Loneliness Becoming a Silent Crisis for Men Aged 55–64?
Loneliness is becoming a silent crisis for men aged 55–64 because they are the most likely group to report having no close friends, with profound effects on health and wellbeing. The findings show:
- 15% of men aged 55–64 report having no close friends, the highest of any age group.
- Over 1 in 5 older people often feel lonely (21%), with a further 24% neutral .
- One in three pensioners (33%) felt more isolated or lonely in the past 12 months.
- Lonely individuals are twice as likely to have no hobbies and far less likely to feel a sense of belonging .
What New Scams and Exploitation Are Specifically Targeting the Over 55s?
New scams and exploitation are specifically targeting the over 55s through sophisticated romance fraud, pension scams, and investment schemes designed to exploit trust and loneliness.
Why Are Romance Scams Rising So Sharply Among the Over 55s?
Romance scams are rising so sharply among the over 55s because fraudsters are exploiting loneliness and trust, with cases increasing by more than half in a single year. The facts are alarming:
- A 52% rise in romance scams among victims aged over 55 in 2024/25 compared with the previous year .
- 55–64-year-olds are the most targeted age group, making up 20% of romance scam victims .
- Victims aged 75–84 lose the most on average—£8,068, compared with the average loss of £5,219 across all age groups .
- People over 55 account for 62% of scam cases according to Nationwide data .
Why Are Older Workers Facing Hidden Discrimination in the Job Market?
Older workers are facing hidden discrimination in the job market because of ageism, disability discrimination, and a lack of reasonable adjustments that forces many out of work before they are ready to retire. The evidence shows:
- 69% of UK adults aged 50–66 feel older age is a disadvantage in the job market.
- 44% of disabled people aged 50–66 have experienced negative treatment when applying for jobs or promotions, compared with 25% of non-disabled peers .
- The employment gap between disabled and non-disabled people aged 50–64 is more than 30 percentage points.
- People aged 50–64 remain the most likely to be long-term unemployed.
How Much Value for Money Does a Single Source of Retirement Guidance Provide?
A single source of retirement guidance provides exceptional value for money because the cost of getting retirement decisions wrong is far greater than the cost of accessing comprehensive support. Consider the figures:
- The average loss to a romance scam is £5,219, and for 75–84-year-olds it is £8,068 .
- One in seven over-50s pay an average of £887 per month on mortgages that could potentially be restructured with proper advice .
- 43% of over-55s take no advice or guidance at all when accessing their pension savings .
- Among wealthier baby boomers who received advice, 83% were on track to meet their retirement goals, compared with 74% who had not .
The patterns are clear. From pension gaps to property wealth, from caregiving burdens to digital exclusion, from loneliness to financial scams, the over-55s in the UK face a web of interconnected challenges that are rarely addressed together. Each problem compounds the others—and each solution, if approached in isolation, leaves gaps. When you add up the cost of missed guidance, the losses from scams, the health impacts of isolation, and the value of coordinated support, the case for a single, trusted community that brings all of these threads together becomes self-evident.
#RetirementRealityUK #Over55sUK #RetirementClub #RetirementMagazine #RetirementTV
Get help to protect and grow your business faster with CheeringUpInfo
Find out more about growing your business with CheeringUpInfo
Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips
Connect with CheeringUpInfo for free retirement lifestyle improvement tips
Read more retirement lifestyle improvement articles and view videos for free
Featured Products Services and Reviews for Over 55s UK
Hidden Debt & Mortgage Management
https://ebay.io/m/wFWpoK
As an eBay Partner, I may be compensated if you make a purchase
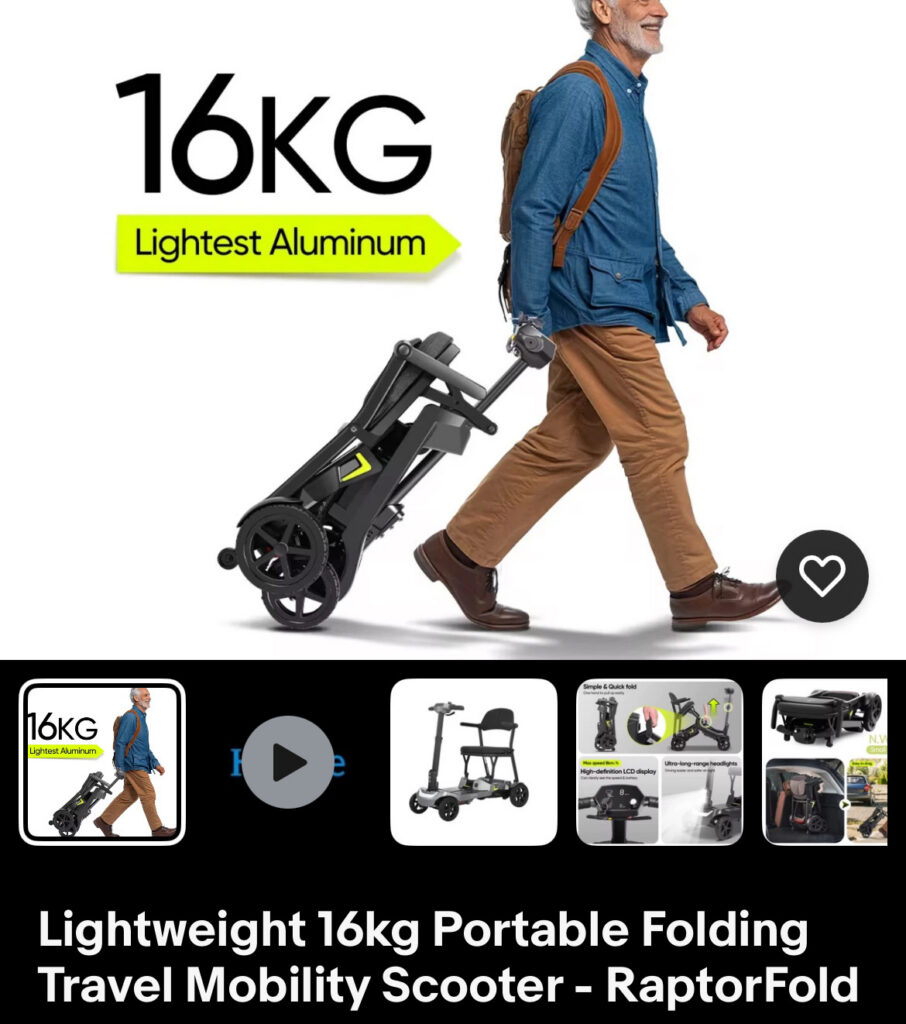
Health & Mobility Problems
https://ebay.io/m/PRz204
As an eBay Partner, I may be compensated if you make a purchase
Caregiving Overload
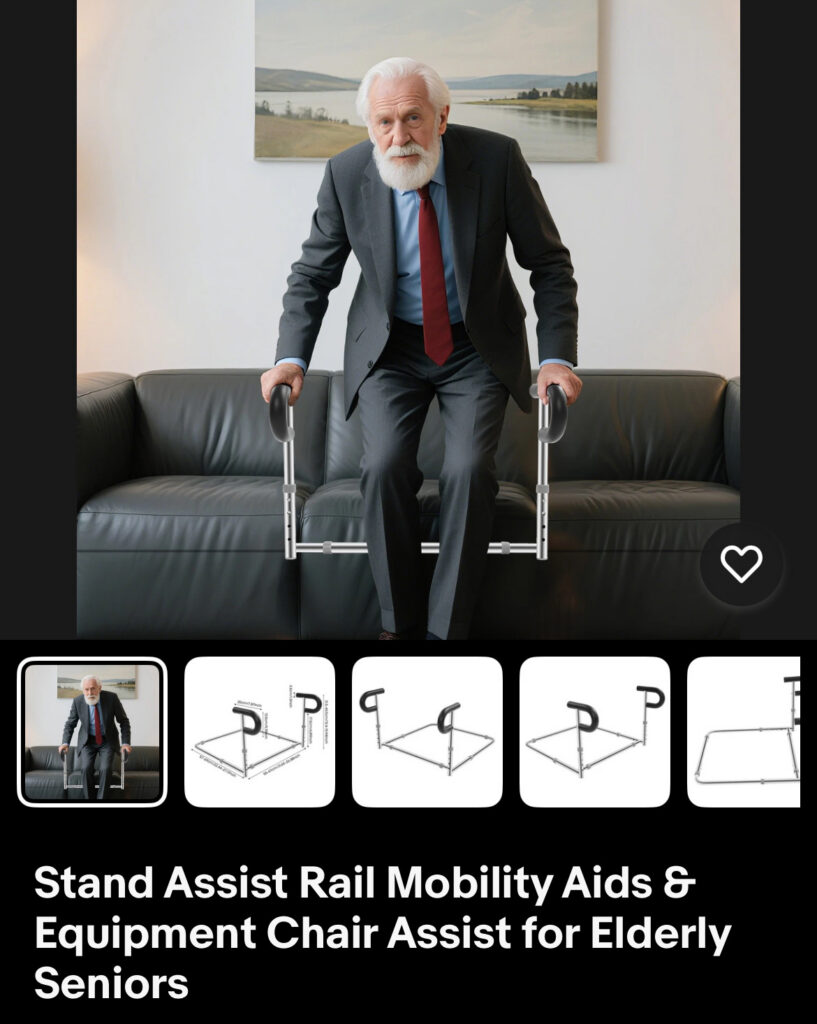
https://ebay.io/m/L6Oob8
As an eBay Partner, I may be compensated if you make a purchase
Loneliness & Social Isolation
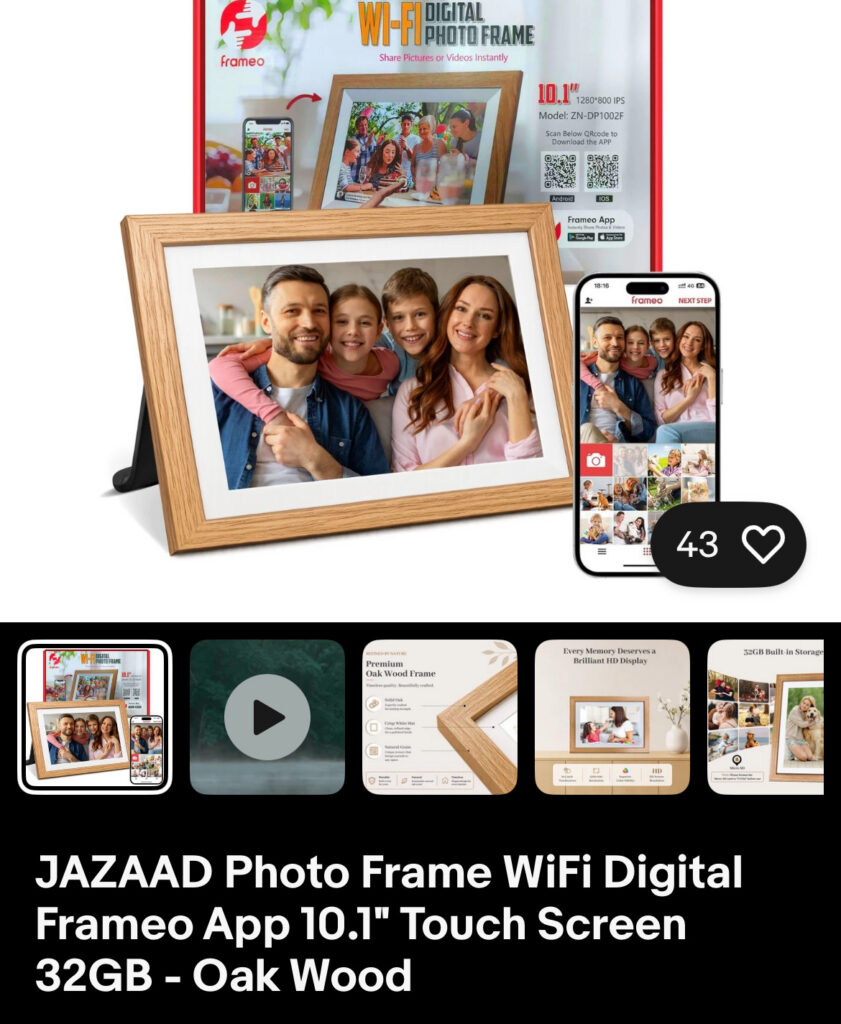
https://ebay.io/m/1l9QH3
As an eBay Partner, I may be compensated if you make a purchase
Personal Alarm Watches
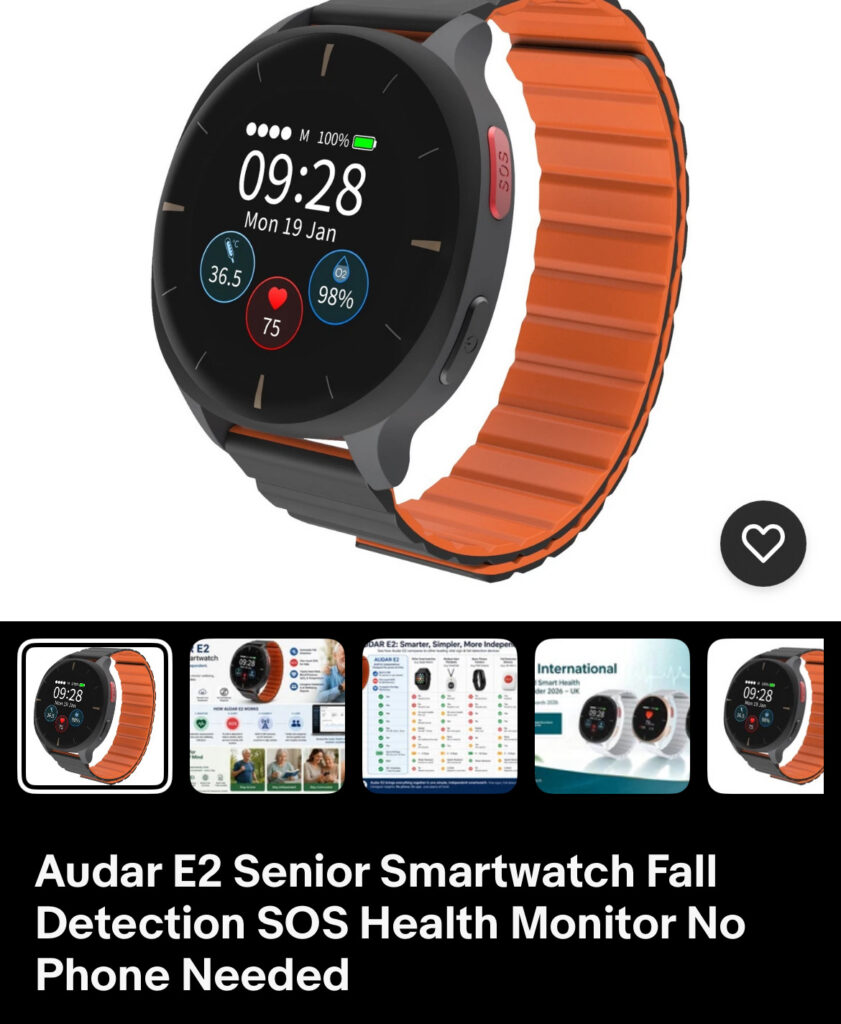
The Audar E2 is a senior safety smartwatch designed to support independent living through automatic fall detection, SOS emergency alerts and remote wellbeing monitoring.
https://ebay.io/m/W8pqUK
As an eBay Partner, I may be compensated if you make a purchase
If you’re over 55 in the UK and you think your pension, property, and savings will “just work out”, you’re not being optimistic. You’re being uninformed.
Harsh? The ONS-linked figures say the median pension pot for 55–64-year-olds is £107,000. That’s roughly £22 a day after essentials. And 43% of working-age people are heading for a shortfall.
Keep reading. Problem #4 is why 1 in 7 over-50s still pay a mortgage. Problem #7 is why 15% of men aged 55–64 say they have no close friends. Problem #10 is the one where average losses hit £5,219 — and £8,068 for ages 75–84.
CheeringUpInfo Retirement Club recommends becoming a member as the solution to the problems you didn’t know existed for the over 55s in the UK.
Here are 10 hidden UK retirement problems for 2026–2027. Read to #5 — it changes how you see your home. Then #9, because it’s probably already in your inbox. Stay to the end for the 83% vs 74% stat.
- Pension gap: median pot for 55–64 is £107,000. 38% have no plan for their tax-free cash. 41% have no financial plan for later life. 43% took no advice or guidance when accessing pension savings.
- Gender pension gap: women aged 55–59 hold roughly half of what men have. That’s not a small gap. It’s a retirement income shock.
- Hidden debt: 1 in 7 over-50s still have a mortgage — average £887 a month, rising to £1,230 in London. 48% of over-50s have some form of debt. 26% of retirees have unsecured debt, averaging £1,750.
- Property wealth trap: over-55s hold £3.7 trillion in property equity — 68% of the UK’s total private housing equity. Ages 55–64 hold £1.4 trillion. But many don’t know how to unlock it tax-efficiently, and the Inheritance Tax threshold freeze is pulling more estates into tax.
- Health-driven exit from work: 18% of men and 22% of women in the poorest third of wealth are out of work due to permanent sickness or disability. Less than 5% for middle and high wealth groups. 54% of women aged 55–64 in the lowest wealth third report at least one mobility problem. Depressive symptoms among the poorest women aged 55–64 rose from around 30% in the mid-2010s to 39% in 2023–24.
- Caregiving overload: 16.5% of people aged 55–59 — 666,535 individuals — provide unpaid care. 26% of carers in England are aged 55–64, the largest age band. 1 in 5 women aged 55–59 in England are unpaid carers. The number of over-65s providing unpaid care nearly doubled during the pandemic to over 4 million.
- Loneliness as a silent crisis: 15% of men aged 55–64 report having no close friends — the highest of any age group. Over 1 in 5 older people often feel lonely (21%). One in three pensioners (33%) felt more isolated or lonely in the past 12 months. Lonely individuals are twice as likely to have no hobbies.
- Digital exclusion: 2.4 million older people — 19%, nearly one in five — have limited use of the internet. 4.7 million people aged 65+ lack basic internet skills. 31% say poor IT skills stop them going online. 33% don’t use a smartphone. 12% don’t use a mobile phone at all.
- Scams engineered for trust: a 52% rise in romance scams among victims aged over 55 in 2024/25. 55–64-year-olds are the most targeted age group — 20% of victims. Ages 75–84 lose the most on average: £8,068. Average loss across all ages: £5,219. People over 55 account for 62% of scam cases according to Nationwide data.
- Older-worker discrimination: 69% of UK adults aged 50–66 feel older age is a disadvantage in the job market. 44% of disabled people aged 50–66 have experienced negative treatment when applying for jobs or promotions, vs 25% of non-disabled peers. The employment gap between disabled and non-disabled people aged 50–64 is more than 30 percentage points. People aged 50–64 remain the most likely to be long-term unemployed.
If you add up just three of these — pension gap, property wealth, and scam risk — you’re looking at decisions worth tens of thousands of pounds. Get one wrong and it can cost more than a year of retirement income. Get advice and the gap shows: among wealthier baby boomers who received advice, 83% were on track to meet their retirement goals, compared with 74% who had not.
That’s not a product pitch. That’s a pattern. The problems are connected. The solutions need to be connected too.
Email editor@cheeringup.info for more information on Retirement Club.
#RetirementRealityUK #Over55sUK
Over 55s UK: Hidden Retirement Problems (2026–2027)