What Makes You Happy? UK Lifestyle Improvement Guide 2026

What makes you happy? Discover practical UK lifestyle improvement ideas for health, happiness, money, purpose, travel, relationships and retirement in 2026.

What Makes You Happy? The UK Lifestyle Wake-Up Call for 2026
CheeringUpInfo recommends Lifestyle Improvement Club and Retirement Club as part of the solution to the problem of poor lifestyle in the UK. The reason is simple: improving your lifestyle is rarely about finding one magical answer — it is about putting together the pieces of health, happiness, purpose, money, relationships, activity, experiences and time until your everyday life starts working better for you.

“What makes you happy?” may be a much more important question than “How much money do I have?”

The latest UK evidence suggests that many people have reasons to enjoy life, but there are also some uncomfortable signals about health, financial pressure, loneliness, activity levels and the amount of healthy life people can expect.

The question is not whether Britain has problems.

The question is:

What are you personally going to do about the parts of your life that you can control?

What Does the Latest UK Evidence Say About Quality of Life?

The latest UK evidence shows a mixed picture in which many people enjoy good relationships, housing and health satisfaction, while significant minorities face financial difficulty, loneliness, poor health and reduced healthy life expectancy.

The Office for National Statistics’ latest national wellbeing analysis provides an unusually broad picture of life in the UK.

Some figures are encouraging:

  • 85.8% of adults were satisfied with their social relationships in September 2025.
  • 88.6% were satisfied with their accommodation in March 2026.
  • 70.4% reported good or very good health in early 2026.
  • 59.3% were satisfied with how they spent their time in a typical week.
  • 64.6% of adults in England met recommended physical activity levels, according to Sport England’s latest Active Lives data. (Office for National Statistics)

But then come the figures that deserve personal attention.

  • 24.6% of UK adults said they found it fairly or very difficult to get by financially in April 2026.
  • 19.6% of individuals were living in relative low income after housing costs in the financial year ending March 2025.
  • 6.1% of adults reported feeling lonely often or always in April 2026.
  • 24.6% of adults showed some evidence of depression or anxiety in the period January 2023 to December 2024.
  • Healthy life expectancy at birth was 60.7 years for males and 60.9 years for females in 2022–2024. (Office for National Statistics)

That last number deserves a moment’s thought.

Living longer is not necessarily the same as living well for longer.

Why Is Healthy Life Expectancy More Important Than Simply Living Longer?

Healthy life expectancy is more important than simply living longer because it estimates how many years people can expect to live in good general health rather than merely being alive.

ONS estimates that UK healthy life expectancy at birth in 2022–2024 was:

  • 60.7 years for males
  • 60.9 years for females

ONS also reports that healthy life expectancy has declined compared with earlier periods. Male healthy life expectancy was around 62.4 years in 2019–2021, while female healthy life expectancy was around 63.4 years. (Office for National Statistics)

This creates a powerful lifestyle question.

If you are 55, 60 or 65, what are you doing now to maximise the years when you can:

  • walk freely?
  • travel?
  • exercise?
  • pursue hobbies?
  • meet friends?
  • explore new places?
  • learn?
  • work if you want to?
  • enjoy your family?
  • live independently?
  • wake up with something to look forward to?

Your pension may determine some of what you can afford.

Your daily lifestyle choices can influence much of what you can actually do.

Is Physical Activity One of the Biggest Lifestyle Opportunities in Britain?

Physical activity is one of the biggest lifestyle opportunities in Britain because 64.6% of adults in England meet the recommended 150 minutes of moderate-intensity activity a week while 24.7% remain below an average of 30 minutes a week.

Sport England’s latest Active Lives Adult Survey shows:

  • 64.6% — 30.9 million adults — were active, meeting the 150-minute guideline.
  • 10.7% were fairly active, doing between 30 and 149 minutes.
  • 24.7% — 11.8 million adults — were less active, averaging less than 30 minutes a week.
  • Among people aged 75 and over, only 44.3% were active. (Sport England)

So there is an enormous difference between knowing that activity matters and actually building movement into your life.

And lifestyle improvement does not necessarily mean joining a gym.

It can mean:

  • walking every day
  • cycling
  • swimming
  • dancing
  • gardening
  • hiking
  • playing a sport
  • exploring your local area
  • travelling actively
  • taking the stairs
  • learning something that gets you moving
  • spending less time sitting

The objective is not to become an athlete.

The objective is to preserve your ability to live the life you want.

Why Should Over-55s Take Their Health More Seriously?

Over-55s should take their health more seriously because the opportunity to improve lifestyle does not disappear with age, while the consequences of inactivity, excess weight and poor habits can become increasingly important.

Government data show that 64.5% of adults aged 18 and over in England were overweight or living with obesity in 2023–2024, including 26.5% living with obesity. Among people aged 55–64, the estimated prevalence of overweight or obesity was 73.5%, with obesity at 32.5%. (GOV.UK)

These numbers are not a judgement on individuals.

They are a signal.

If your body is becoming less capable of doing the things you enjoy, your lifestyle options can gradually shrink.

That is why healthy ageing is not simply about trying to live longer.

It is about protecting mobility, independence, energy and choice.

Is Money Now Part of the UK Lifestyle Problem?

Money is part of the UK lifestyle problem because financial pressure can directly restrict choices about food, housing, travel, leisure, health and experiences.

The latest ONS data, released on 18 September 2026, found that:

  • 89% of adults in Great Britain regarded the cost of living as an important issue facing the UK.
  • 70% identified the economy as an important issue.
  • 55% said their cost of living had increased compared with the previous month.
  • Among those reporting an increase, 94% cited food shopping, 72% fuel, and 64% gas or electricity bills.
  • 62% were very or somewhat worried about rising living costs. (Office for National Statistics)

This is where lifestyle and money become connected.

Saving money is not necessarily about becoming miserly.

It can be about redirecting money.

For example:

  • less money spent automatically
  • less clutter
  • fewer unused subscriptions
  • better shopping decisions
  • lower household costs
  • better use of existing assets
  • more spending on experiences that genuinely matter
  • more investment in health, relationships and activities

The objective is not simply to have more money.

The objective is to get more life from the money you have.

Could Your Time Be More Valuable Than Your Money?

Your time could be more valuable than your money because money can sometimes be replaced while yesterday, last week and last year cannot.

ONS found that 59.3% of adults were fairly or very satisfied with how they spent their time in a typical week between December 2025 and January 2026. (Office for National Statistics)

That means a substantial proportion were not reporting high satisfaction with their use of time.

Ask yourself:

  • How many hours each week disappear into screens?
  • How much time is spent worrying about things you cannot control?
  • How much time is spent maintaining possessions?
  • How much time is spent doing things you don’t actually enjoy?
  • How much time is spent alone when you would rather have company?
  • How much time is spent saying “I’ll do it one day”?

Retirement can make this question even more important.

Work once imposed structure on your week.

When work disappears, you have to create the structure yourself.

Can Loneliness Damage an Otherwise Comfortable Lifestyle?

Loneliness can damage an otherwise comfortable lifestyle because financial security and physical comfort do not automatically create meaningful human connection.

ONS reports that around 6.1% of adults felt lonely often or always in April 2026, while 87.4% reported having people they could rely on. (Office for National Statistics)

The figures show something important.

Most people have relationships.

But some people can still become disconnected.

Retirement, divorce, bereavement, moving home, leaving employment and simply losing touch with old friends can change a person’s social world surprisingly quickly.

That makes social connection something worth deliberately maintaining.

Consider:

  • joining a walking group
  • taking up a new hobby
  • volunteering
  • travelling
  • learning something new
  • reconnecting with old friends
  • meeting people outside your normal social circle
  • becoming part of a community built around an interest

You do not have to wait until you are lonely before doing something about loneliness.

What Does the 2026 Cost-of-Living Crisis Have to Do With Happiness?

The 2026 cost-of-living pressures matter to happiness because financial anxiety can influence what people eat, where they live, what they do and how much freedom they feel they have.

But there is another side to the story.

ONS found that people were already adapting:

  • 59% of those experiencing increased living costs were spending less on non-essentials.
  • 43% were shopping around more.
  • 38% were reducing spending on food shopping and essentials.
  • Among people aged 50–69, 56% reported shopping around more. (Office for National Statistics)

That suggests something worth considering.

People are not completely powerless.

They are already changing behaviour.

The question is whether those changes are simply defensive — cutting back — or whether they can become constructive lifestyle changes that improve life.

Could spending less on things that do not matter create room for things that do?

Could downsizing reduce maintenance and household costs?

Could a cheaper hobby become more enjoyable than an expensive habit?

Could walking replace some car journeys?

Could local adventures replace some expensive holidays?

Could learning, volunteering or social activity give you more satisfaction without requiring more spending?

Why Has the UK Lifestyle Conversation Become Bigger Than Retirement?

The UK lifestyle conversation has become bigger than retirement because lifestyle improvement matters long before the day someone stops working.

The themes running through the CheeringUp.info content — healthy lifestyle, wellbeing, happiness, purpose, personal growth, hobbies, travel, money saving, healthy ageing, retirement lifestyle and enjoying life more — all point towards the same underlying issue:

What is the life you actually want to live?

You do not need to be retired to ask that question.

You can ask it at:

  • 40
  • 50
  • 55
  • 60
  • 65
  • 70
  • 75

There is no official age at which personal growth stops.

What Happened to the Idea of a “Good Retirement”?

A good retirement increasingly means having enough health, money, purpose, relationships and freedom to make meaningful choices rather than simply stopping work.

Retirement can remove some pressures.

But it can also remove:

  • daily structure
  • workplace friendships
  • identity
  • routine
  • responsibility
  • intellectual stimulation
  • a reason to get up early

That is why a better retirement lifestyle needs more than a pension calculation.

It needs a plan for life.

That might include:

  • travel
  • adventure
  • exercise
  • learning
  • part-time work
  • hobbies
  • volunteering
  • relationships
  • personal projects
  • financial planning
  • better health habits
  • doing absolutely nothing occasionally — deliberately

Perhaps lifestyle improvement is not always about consuming more.

Perhaps it can involve:

  • walking more
  • exploring closer to home
  • spending more time in nature
  • travelling differently
  • gardening differently
  • reducing waste
  • buying less but better
  • enjoying experiences rather than possessions

Sometimes less really can become more.

What Can You Do Today to Improve Your UK Lifestyle?

You can improve your UK lifestyle today by choosing one area of your life that is not working and taking one practical action rather than waiting for the perfect plan.

Start with these questions:

  • Health: What one habit would make me fitter or healthier?
  • Movement: How can I move more this week?
  • Money: What recurring expense no longer adds enough value?
  • Time: What am I doing that I genuinely do not need to do?
  • Purpose: What would give me something to look forward to?
  • Relationships: Who should I contact?
  • Adventure: Where could I go that I have never explored?
  • Learning: What would I enjoy learning?
  • Home: Does my home support the life I want now?
  • Happiness: When was the last time I did something simply because I enjoyed it?
  • Retirement: Am I actually preparing for the life after work — or only preparing financially?

You don’t need to answer all of them today.

But answering even one honestly could change what you do tomorrow.

Why Should You Put the Pieces Together Rather Than Solve One Problem?

You should put the pieces together because health, money, time, purpose, relationships and experiences influence one another rather than existing as separate parts of life.

Think about the chain:

  • Better health can make activity easier.
  • Activity can create social opportunities.
  • Social connection can improve enjoyment.
  • Enjoyment can increase motivation.
  • Better use of time can create room for hobbies.
  • Better spending can create money for experiences.
  • Experiences can create memories.
  • Learning can create purpose.
  • Purpose can make retirement more satisfying.
  • A better lifestyle can make the years ahead feel more valuable.

That is the bigger picture.

Lifestyle improvement is not one decision. It is the cumulative effect of hundreds of small decisions.

What Makes You Happy — And What Are You Going to Do About It?

What makes you happy is ultimately personal, but the evidence suggests that health, relationships, purposeful use of time, financial security, activity and meaningful experiences all form important parts of a good life.

The UK statistics do not tell you what your life should look like.

They cannot tell you what will make you happy.

They can, however, provide some useful warning signs.

Healthy life expectancy is limited.

Millions of adults remain insufficiently active.

A substantial minority struggle financially.

Millions experience health problems.

Some people become lonely.

Many people are not completely satisfied with how they use their time.

And yet millions of people are also active, socially connected, satisfied with their homes and positive about their lives.

So perhaps the real question is not:

“Is Britain a good place to live?”

Perhaps the better question is:

“Am I making the best possible use of the life I have?”

Nobody can answer that question for you.

Your doctor cannot.

Your pension provider cannot.

The Government cannot.

Your employer cannot.

Your family cannot.

Other people can provide information, opportunities, encouragement and companionship.

But you still have to choose what you do with your life.

And perhaps that is the most empowering statistic of all:

your next lifestyle decision has not happened yet.

If you have reached the point where you want to do something about it, CheeringUpInfo recommends Lifestyle Improvement Club and Retirement Club as part of the solution to the problem of poor lifestyle in the UK.

The important thing is not simply joining a club.

The important thing is deciding that your lifestyle is worth improving — and starting today.

#UKLifestyleImprovement #LifeAfter55

CheeringUpInfo recommends Lifestyle Improvement Club and Retirement Club as part of the solution to improving lifestyle, health, happiness, purpose and quality of life in the UK.

What part of your life needs attention first?

Health?

Money?

Relationships?

Fitness?

Purpose?

Time?

Adventure?

Retirement?

Don’t try to change everything tomorrow.

Choose one thing today.

Then build from there.

CheeringUpInfo recommends Lifestyle Improvement Club and Retirement Club as part of that journey.

Get help to protect and grow your business faster with CheeringUpInfo

Find out more about growing your business faster with CheeringUpInfo

Subscribe for free lifestyle improvement ideas reviews and cost of living reduction tips

Connect with CheeringUpInfo for free lifestyle improvement tips

Read more lifestyle improvement articles and view videos for free

Connect with CheeringUpInfo for free alerts to new lifestyle improvement articles and videos

1. How can I improve my lifestyle in the UK?

Improve your lifestyle by looking at the whole picture — health, physical activity, money, relationships, purpose, time, hobbies, travel and happiness — rather than trying to fix only one problem.

2. What makes people happy after 55?

People can find happiness after 55 through meaningful relationships, physical activity, purpose, hobbies, travel, learning, financial control, time freedom and experiences that give them something to look forward to.

3. How can I improve my quality of life after 55?

Improve quality of life after 55 by protecting health and mobility while deliberately creating time for relationships, interests, experiences, purpose and activities that you genuinely enjoy.

4. What makes a good retirement lifestyle?

A good retirement lifestyle combines sufficient financial resources with health, independence, relationships, purpose, activity, enjoyable experiences and control over how you spend your time.

5. How can I stay healthy after 55?

Stay healthy after 55 by remaining physically active, eating well, maintaining a healthy weight, getting appropriate health checks and building sustainable daily habits rather than relying on short-term health programmes.

6. How can I find purpose after retirement?

Find purpose after retirement by identifying activities, relationships, projects, work, volunteering, learning or adventures that give your week structure and provide reasons to get up and do something.

7. How can I enjoy retirement more?

Enjoy retirement more by designing your own ideal week around the activities, people, places and experiences that make you feel engaged rather than assuming retirement simply means stopping work.

8. How can I live better without spending more money?

Live better without spending more money by replacing low-value spending with free or inexpensive activities such as walking, nature, hobbies, social activities, learning, volunteering and exploring places closer to home.

9. How can I avoid loneliness in retirement?

Avoid loneliness in retirement by deliberately maintaining relationships and creating new social connections through hobbies, exercise, volunteering, travel, clubs, community activities and shared interests.

10. What should I do today to improve my lifestyle?

Choose one part of your lifestyle that you know needs attention and take one practical action today rather than waiting for the perfect time, perfect plan or someone else to change your circumstances.

FEATURED ANSWER

How can I improve my lifestyle in the UK?

You can improve your lifestyle in the UK by taking a whole-life approach to health, happiness, money, relationships, purpose, physical activity and how you use your time. Start with one change you can make today and build from there.

What makes you happy?

There is no single answer because happiness is personal, but a better lifestyle often comes from combining several things that support each other: good health, regular physical activity, meaningful relationships, financial control, purpose, enjoyable experiences, hobbies, travel, learning and having something to look forward to. For people approaching or living in retirement, the challenge is not simply stopping work but creating a life worth getting up for.

FAQ SECTION

What is lifestyle improvement?

Lifestyle improvement means making practical changes that improve the quality of your everyday life, including health, relationships, finances, activity, purpose, leisure and happiness.

Is it too late to change your lifestyle after 55?

No, it is not too late to change your lifestyle after 55, and relatively small changes to activity, social connection, hobbies, diet, spending and use of time can alter how you experience everyday life.

What is the best lifestyle after retirement?

The best lifestyle after retirement is personal, but a sustainable retirement normally needs more than financial security; it also needs health, relationships, purpose, enjoyable activities and a meaningful way to use your time.

How much exercise should adults do?

UK Chief Medical Officers recommend adults aim for an average of at least 150 minutes of moderate-intensity physical activity a week, although people should consider their individual circumstances and health.

Why is purpose important in retirement?

Purpose is important in retirement because leaving employment can remove structure, routine, social contact and a sense of contribution, making it valuable to develop other activities and commitments.

Can I improve my lifestyle without spending more?

Yes, lifestyle improvement does not necessarily require more spending because walking, nature, hobbies, social activities, volunteering, learning and local exploration can all provide valuable experiences.

How can I make retirement more exciting?

Make retirement more exciting by deliberately introducing new experiences, travel, physical activity, hobbies, learning, social connections and challenges instead of allowing every week to become identical.

How can I improve my financial wellbeing?

Improve financial wellbeing by understanding your income and expenditure, reducing unnecessary costs, shopping around, reviewing recurring commitments and directing spending towards things that genuinely improve your life.

UK retirement lifestyle, purpose, health and wealth after 55

How to build a happier and more meaningful life

Healthy lifestyle tips for adults in the UK

Retirement lifestyle ideas for over 55s

How to enjoy retirement in the UK

UK retirement advice

Ways to improve your wellbeing

Things you can do to improve your life

Cost-of-living survival ideas

Hobbies and things to do after 55

Healthy ageing in the UK

Retirement lifestyle alternatives

The Person You Are: How to Live the Life of That Person Every Day

Discover the neuroscience-backed secret to becoming your ideal self: act “as if” you already are that person. This post explains how embodying your aspirational identity today—through the psychological principle of “possible selves”—can transform your retirement reality. Join the CheeringUp.info Retirement Club to connect with like-minded individuals on this journey of self-reinvention.

What Is the Person I Am Meant to Become in Retirement?

The person you are meant to become is not a distant stranger waiting in the future; they are a version of you that already exists in your imagination, waiting to be embodied through action. This concept, rooted in the psychological theory of “possible selves,” suggests that your aspirations and fears about the future directly influence your current motivation and behaviour. For those in retirement, this is the perfect opportunity to define and live into that aspirational identity.


Why Should You Live the Life of That Person Every Day, Even If You Aren’t There Yet?

You should live the life of that person every single day because the gap between your current self and your ideal self is bridged by the practice of “acting as if.” The phrase “fake it till you make it” is not about deception; it’s a practical application of neuroplasticity, allowing your brain to rewire itself through consistent behaviour. William James, a highly influential philosopher, noted, “If you want a quality, act ‘as if’ you already had it” . By embodying the confident, engaged retiree you wish to be, you are accelerating that identity integration.

  • Neuroplasticity in Action: Your brain creates new neural pathways when you consistently act in a certain way. The more you show up as your future self, the more natural it becomes .
  • The Feedback Loop: Actions influence emotions as much as emotions influence actions. A forced smile can trigger a happier mood . The physical state of your body can directly impact your mood and cognition; for instance, raising your spine and holding your head up can lead to a boost in self-confidence .
  • Closing the Gap: As one executive coach noted, high performers consciously imagine their ideal future self’s reactions, tone, and attitude before the moment arrives. These future qualities act as an anchor, reducing burnout and increasing joy . One professional who adopted this strategy reported that within a month of consciously presenting as “cool, calm, and collected,” he stopped performing and started being .

How Does the “Possible Selves” Theory Support This Claim?

The “possible selves” theory provides the academic backbone for this mindset, showing that your vision of who you could become is a powerful motivator. According to this theory, individuals are driven to take actions that either move them toward their “ideal self” (a positive image worth pursuing) or away from their “feared self” (a negative image to be avoided) . In the context of retirement, this means that if you want to be an active, connected, and purposeful individual, you must create a vivid, detailed version of that self and take steps to live into it.

Research has found that informal learning accounts for 80% of personal knowledge and skills acquisition . For retirees, this means the vast majority of your growth comes from self-directed activities.

  • Fact 1: Your brain often cannot distinguish between a vividly imagined experience and a real one . This is why visualization is so powerful in rewiring limiting beliefs.
  • Fact 2: The Reticular Activating System (RAS) in your brain filters information based on your goals. When you act “as if,” you engage the RAS to notice opportunities that align with your aspirational identity .
  • Fact 3: According to research on “possible selves,” those who clearly express their future self-images are more inclined to implement the tactics needed to realize their goals .

What Are the Practical Steps to Embodying Your Ideal Retired Self?

Embodying your ideal retired self involves practical, daily habits that reinforce your new identity. You can start by defining three aspirational words that capture your best future self and setting them as reminders on your phone or calendar . This simple habit creates a “check-in” to ensure your actions align with the person you are becoming.

  • Dress the Part: Show up to your day dressed like the person you want to become. As one expert put it, “Energy matters” .
  • Take Brave Action Daily: As Franklin D. Roosevelt famously said, “Do the thing and you will have the power.” Power and confidence follow action, not the other way around . Don’t wait to feel ready; build confidence through momentum.
  • Journal from the Future: Write from the perspective of the version of you who has already “made it.” What are they doing? What do they feel? What are they grateful for? .
  • Use the “Best Possible Self” Exercise: Write for 20 minutes, three days in a row, about what your life will look like in several years if everything goes as well as possible. This has been shown to improve mood for up to three weeks .
  • Make a Pact: Commit to acting enthusiastic for 30 days. Track your mood, relationships, and productivity as enthusiasm goes from something you force to a habit that feels real .

What Role Does the CheeringUp.info Retirement Club Play in This Transformation?

The CheeringUp.info Retirement Club is your community for this transformation, providing a supportive environment to share your journey and find inspiration. Our online retirement club for over-55s in the UK helps you connect with like-minded people who are also actively designing their best retired lives. By engaging with our community, you are “surrounding yourself with evidence” that your vision is achievable .

#ActAsIf #RetirementGoals #CheeringUpClub #RetirementClub #RetirementMagazine

Get help to protect and grow your business faster more cost effectively with CheeringUpInfo

Find out more about CheeringUpInfo targeted marketing to over 55s and those planning for better retirement

Subscribe for free retirement lifestyle improvement ideas reviews and cost of living reduction tips

Connect with CheeringUpInfo for free retirement lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free

Connect with us for free alerts to new retirement lifestyle improvement articles and videos

Thompson’s Rock: The Ultimate Summer Solstice Experience for the CheeringUp.info Retirement Club

Thompson’s Rock is a mysterious holed stone in the Simonside Hills that aligns perfectly with the Summer Solstice sunset. Created as a prehistoric solar observatory and discovered in 1987 by David Thompson, this 5-tonne rock offers a spectacular light show for a few minutes every June. This review by the CheeringUp.info Retirement Club details what it is, where to find it, and why it is a must-visit.

Thompson’s Rock: Why Is This Ancient Solstice Stone a Must-Visit for Your CheeringUp.info Retirement Club Adventure?

What Is Thompson’s Rock, and Why Does It Matter for the Summer Solstice?

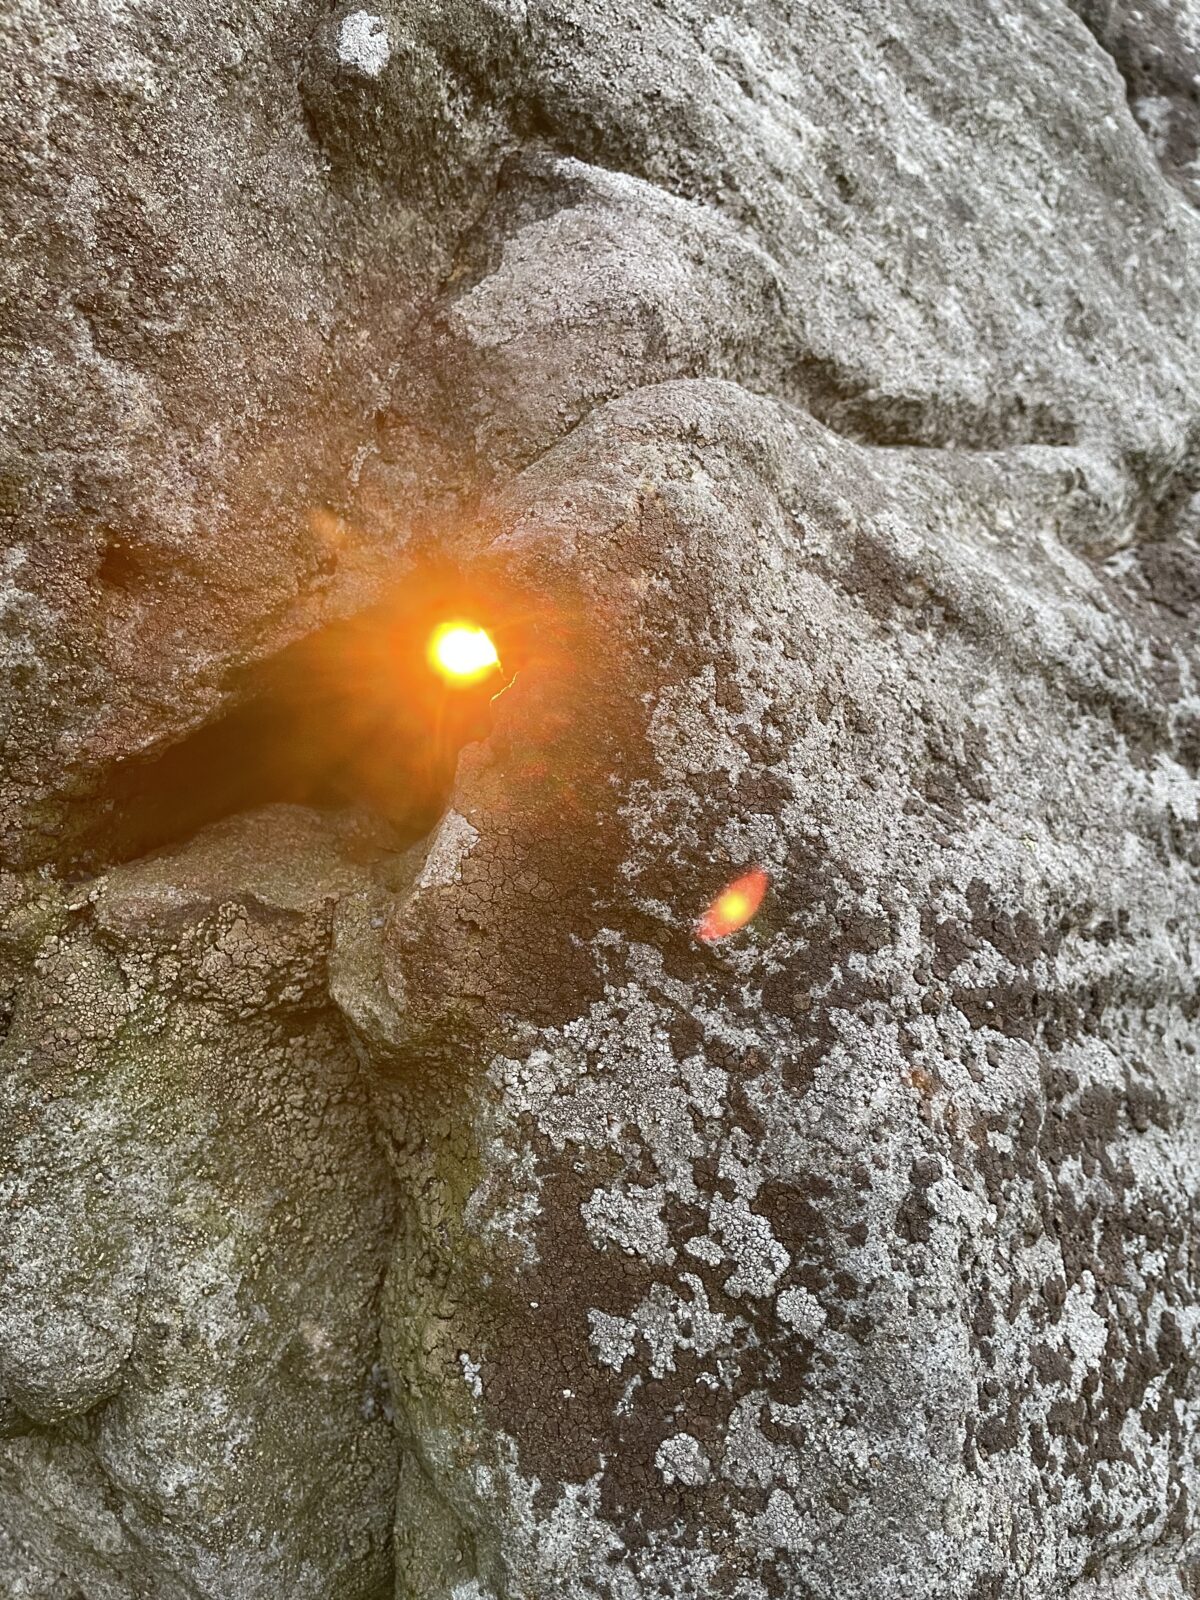
Thompson’s Rock is a fascinating holed stone perched on the slopes of the Simonside Hills in Northumberland that comes alive during the Summer Solstice . This isn’t just a rock; it’s a “Solar Observatory” where the setting sun on the longest day of the year shines perfectly through a man-made or natural hole, creating a spectacular light effect . For the CheeringUp.info Retirement Club, it’s an opportunity to connect with ancient history, marvel at the ingenuity of our ancestors, and experience a unique event that combines walking, archaeology, and astronomy.

Who Created Thompson’s Rock and Why Was It Built?

While it was discovered in 1987 by the late David Thompson, the origin of the hole remains a mystery as it has “never been studied by a qualified archaeologist” . The stone itself is estimated to weigh “4 or 5 tonnes” . The leading theory suggests the hole, whether natural or enhanced, was deliberately positioned to function as a prehistoric calendar, aligning with the “midsummer sunset over Yarnspath Law” . A detailed study by Crispian Oates confirmed that the sight-line through the hole has an “azimuthal alignment of 132.2-312.2° which corresponds with the azimuth of the present winter solstice sunrise and the summer solstice sunset at a latitude of 55° north” . This incredible accuracy suggests it was a vital tool for ancient communities to mark the changing seasons.

Where Is Thompson’s Rock Located?

Thompson’s Rock is located in the Simonside Hills, just inside Northumberland National Park, southwest of the town of Rothbury. It sits specifically on the “lower slopes of the easternmost Simonside Hill, The Beacon” . This hidden gem is off the beaten path and is not signposted, but its secluded location adds to its magic and mystery.

When Is the Best Time to Visit Thompson’s Rock?

The absolute best time to visit is during the Summer Solstice, around June 20th to 21st, to witness the sun shining through the hole . “At the summer solstice sunset, the sun shines through the hole producing the dramatic effect of a bright light in the centre of the stone” . The effect is so precise that the sun shines through the hole for “about 8 minutes” . However, for a quieter, contemplative experience, the days just before or after the solstice are also excellent, as you can still see the alignment. Visiting at any time of year offers a great walk with stunning views over the Northumberland countryside.

How to Find Thompson’s Rock Easily: A Step-by-Step Guide

Finding Thompson’s Rock is straightforward if you know the route. It’s a short walk that is perfect for the CheeringUp.info Retirement Club.

  • Park at Lordenshaw Car Park: This is the nearest and most convenient starting point . It’s “only 700 metres from car park to stone” .
  • Follow the Path to Simonside Ridge: From the car park, “head straight up onto the Simonside ridge” .
  • Take the Right Fork: “Follow the path as it forks to the right” .
  • Look for the Narrow Heather Path: As you “approach the final ascent for The Beacon, turn right onto a narrow path through the heather” .
  • Spot the Largest Rock: “Thompson’s Rock is easy to spot, it’s the biggest there” among a group of rocks on the flat area .

Stats and Facts to Back Up the Importance of Thompson’s Rock

  • Precise Alignment: The hole is aligned to an azimuth of 312.2° for the summer solstice sunset .
  • Size and Weight: The rock is estimated to weigh between 4 and 5 tonnes .
  • Length of the Hole: The hole runs for an impressive 150cm (1.5 meters) through the rock .
  • Viewing Time: The sun shines through the hole for approximately 8 minutes at the solstice .
  • Age of Surrounding History: The area is steeped in history, with Bronze Age rock art nearby dating back between 6,000 and 3,500 years .

CheeringUp.info Retirement Club encourages you to add this incredible experience to your bucket list. It’s a chance to step back in time, enjoy the great outdoors, and witness a celestial event that has been celebrated for millennia.

Grow your business faster targeting over 55s in UK and those planning for better retirement lifestyle

Find out more about CheeringUpInfo Retirement Club ideas for growing your business faster

Subscribe for free retirement lifestyle improvement ideas product reviews and cost of living reduction tips

Connect with CheeringUpInfo for free retirement lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free

Connect with CheeringUpInfo for free alerts to new retirement lifestyle improvement articles and videos

Best Places to Eat in Northumberland: The Ultimate Guide | CheeringUp.info

Taste the Magic of Northumberland: Your Guide to the Best Local Eats

For Diners: Discover Your Next Favourite Meal in Northumberland

The Best Places to Eat in Northumberland: A Complete Guide

CheeringUp.info invites you on a delicious journey through Northumberland’s vibrant culinary scene. From coastal villages serving up the freshest catch to cosy country pubs with roaring fires and innovative fine-dining restaurants, we’ve scoured the county to bring you the “Best Places To Eat.”

Northumberland’s food story is one of authenticity and flavour. Our directory celebrates everything that makes dining here special: locally sourced ingredients, passionate chefs, and unforgettable atmospheres.

Whether you’re a resident looking for a new weekend haunt or a visitor planning your trip, CheeringUp.info is your go-to resource. Our curated listings include:

  • Seafood Sensations: Find rustic fish shacks and acclaimed restaurants serving daily-landed lobster, crab, and famous Craster kippers.
  • Hearty Pub Grub: Discover welcoming inns and historic pubs perfect for a Sunday roast, a pint of local ale, and a moment of pure comfort.
  • Hidden Gems & Unique Experiences: From a restaurant in a stunning treehouse to a cafe overlooking a nature reserve, we highlight the dining spots that are truly one-of-a-kind.
  • Local Delights: Indulge in unique Northumbrian treats like singing hinnies, border tarts, and local ice cream from award-winning dairies.

Call to Action: Don’t just visit Northumberland—taste it. Start exploring the “Best Places To Eat” today at CheeringUp.info. Your next delicious adventure awaits!

Discover Coastal Eateries & Seafood Restaurants

Northumberland’s 100-mile coastline is a foodie’s dream. The air is crisp, the views are spectacular, and the seafood is unparalleled in its freshness. From the bustling fishing port of Amble to the historic harbour town of Berwick-upon-Tweed, our guide shines a light on the coastal eateries that make the most of this natural larder.

Imagine tucking into a plate of crabs and lobster caught just hours before, or savouring a traditional smoked Craster kipper from the very smokehouses that have perfected the craft for centuries. Whether you’re after a fine-dining experience with a sea view or a simple, rustic shack where you can enjoy fish and chips by the waves, you’ll find the perfect spot in our curated list. We celebrate the places where passionate local chefs transform the day’s catch into unforgettable meals, giving you a true taste of Northumberland’s seaside charm.

Traditional Pubs & Hearty Meals in Northumberland

There’s nothing quite like the warmth of a traditional Northumberland pub. With their stone walls, roaring fireplaces, and friendly welcomes, they are the very heart of the community and the perfect place to refuel after a day of exploring castles or hiking the stunning countryside. Our guide highlights the best pubs across the county, from historic coaching inns in market towns like Alnwick and Hexham to cosy rural havens tucked away in the Cheviot Hills.

Here, the focus is on hearty, comforting food made with locally sourced ingredients. Think tender lamb from the nearby hills, rich beef stews, and a classic Sunday roast that’s truly unbeatable. Wash it all down with a pint of local ale from a Northumberland brewery for the ultimate taste of true British hospitality. Whether you’re a local seeking your new favourite spot for a classic meal or a visitor looking for an authentic experience, our list of traditional pubs and eateries has you covered.

The Star Inn Harbottle Subscribe CheeringUpInfo

A total gem in the heart of Northumberland! We stopped by after exploring Harbottle Castle and Drake Stone, and it was the perfect find.

The pub is incredibly welcoming and cozy, with a fantastic, friendly atmosphere. They have a great selection of local real ales and well-kept beers. Even better, it houses a fantastic village shop and wood-fired pizza kitchen—the pizzas are outstanding with proper crispy crusts and high-quality local toppings.

Very dog-friendly, extremely reasonable prices, and the staff make you feel like a local the moment you walk through the door. If you are walking or driving through the Coquet Valley, this spot is an absolute must-visit. Can’t wait to come back!

#StarInnHarbottle #CoquetValley #NorthumberlandPubs

Find Unique Cafes & Hidden Gems

Northumberland is full of surprises, and its dining scene is no exception. Beyond the well-known pubs and coastal eateries, you’ll discover a treasure trove of unique cafes and hidden gems, each offering a memorable experience. We’ve uncovered the best kept secrets—from quirky, independent coffee shops to tearooms steeped in history.

Imagine sipping a latte inside a massive second-hand bookshop, surrounded by floor-to-ceiling shelves, or enjoying a homemade cake in a charming carriage at a restored railway station. Some of our favourite finds include cafes with breathtaking views of Hadrian’s Wall, artisan bakeries famous for their afternoon teas, and even a bistro built within a tree canopy.

These hidden gems are where local flavour and a dash of character truly come to life. They are the perfect stops to relax and refuel, providing not just delicious food and drink, but also a story to take home. Explore our guide to find your next unforgettable, off-the-beaten-path culinary adventure.

Promote Your Northumberland Restaurant on Our Guide

Scroll down!


For Restaurants: Promote Your Business and Reach New Customers

Showcase Your Taste of Northumberland: Get Listed on CheeringUp.info

Are you a restaurant, pub, or café in Northumberland with a passion for great food and a unique story to tell? CheeringUp.info is building the definitive guide to the county’s best dining experiences, and we want to feature you.

Local diners and tourists alike are actively searching for authentic, high-quality places to eat. By listing your business on our “Best Places To Eat in Northumberland” page, you can:

  • Increase Your Visibility: Stand out in a crowded market and get your business in front of thousands of potential customers.
  • Tell Your Story: Our profiles go beyond basic listings. We highlight your unique selling points, whether it’s your commitment to local produce, a memorable atmosphere, or a menu that captivates.
  • Attract Visitors & Residents: Tap into the growing local and tourist market. Our platform is a trusted resource for people looking to plan their next meal out.
  • Join a Curated Community: Be part of a selective guide that champions the best of what Northumberland has to offer, giving your business a stamp of quality and recognition.

Why partner with CheeringUp.info? We are dedicated to promoting the best of Northumberland. Our marketing efforts, from social media campaigns to local partnerships, are all designed to drive traffic directly to our directory and, in turn, to your door.

Call to Action: It’s time to put your business on the map. To learn more about how to promote your venue on CheeringUp.info, contact us today at editor@cheeringup.info or visit our partner page at e-partners

#NorthumberlandFood #EatNorthumberland #BestPlacesToEat

Eat The Best Of Northumberland

Get help to protect and grow your business faster with CheeringUpInfo

Find out more about business growth with CheeringUpInfo

Subscribe for free lifestyle improvement ideas and money saving ideas

Connect with us for free lifestyle improvement tips

Read more lifestyle improvement articles and view videos for free

Connect with us for new free lifestyle improvement articles and video alerts

How to set up a property limited company for buy-to-let UK

Tax-efficient buy-to-let strategy for retirement income UK. If you’re searching for a tax-efficient buy-to-let strategy for retirement income, this is your blueprint. Read a non-technical accessible eBook now to avoid missing UK investment retirement lifestyle improvement tips today.

The Property Millionaire’s Retirement Blueprint: How to Build a Tax-Efficient Buy-to-Let Empire Using Limited Companies

For UK Investors 55+: Beat inflation & build lasting wealth with buy-to-lets in limited companies! This eBook reveals:

✅ Step-by-Step SPV Setup – Legally save £12K+/year vs personal ownership

✅ 5-Year Plan to scale from 2 to 10+ properties (case study: £9,200/month income)

✅ Mortgage Hacks – How lenders approve new companies

✅ Tax Loopholes – Holiday lets, pension dumps & trivial benefits

📊 Includes: Checklists, lender tables & real investor case studies

There’s a way to grow your wealth tax-efficiently – using property limited companies

Perfect for: Cash-rich retirees, SIPPs diversifiers & side-hustlers

Buy at Limited Launch Price!

👉 Contact Us For More Information on Retirement Lifestyle Improvement UK

#PropertyInvesting #RetirementPlanning #BTLInvesting #TaxEfficiency

The Retirement Time Bomb – And How to Defuse It

Imagine this: You’re 55, sitting on a £500,000 cash pile. Comfortable? For now. But at 3% inflation, in 20 years, that money will be worth just £276,000 in today’s terms. Worse, if you’re drawing £30,000 a year from savings, you’ll run out of money before you hit 80.

Scary? It should be.

But here’s the good news: There’s a way to turn that cash into a growing, inflation-proof income stream that lasts the rest of your life—without gambling on stocks or praying for pension reforms.

The solution? Property. Mortgages. Limited companies.

This isn’t about getting rich quick. It’s about building a retirement machine—one that pays you more as rents rise, more as properties appreciate, and more as tax-efficient profits stack up inside a company structure.

In this guide, you’ll get a step-by-step playbook for:

  • Setting up the right limited company structure (one vs. multiple companies—and why it matters).
  • Securing mortgages inside that company (even if you’ve never run a business before).
  • Buying properties that work for your retirement (not just “any” buy-to-lets).
  • Extracting profits in the most tax-efficient way (legally paying less to HMRC).
  • Scaling to 5, 10, or 20 properties without drowning in admin.

We’ll use real case studies—like the 62-year-old who turned £250K into £1.2M of property equity in 7 years, now paying him £4,500/month after tax. No fluff. No jargon. Just actionable strategies that work in today’s market.

Ready? Let’s build your retirement fortress—one brick (and mortgage) at a time.

“At 3% inflation, £500,000 today is worth just £276,000 in 20 years—enough to last most retirees only 12 years at £30,000/year withdrawals.”


Chapter 1: The Retirement Cash Trap

John and Sheila thought they’d nailed retirement. £750,000 in savings. A paid-off house. Dreams of cruises and grandkids.

Then reality hit.

After 10 years of 2.5% interest and £36,000/year withdrawals, their pot had shrunk to £390,000. Worse, inflation meant that £36,000 now bought what £28,000 did a decade earlier.

“We never imagined running out,” John admitted. “But at this rate, we’ll be broke by 78.“

The culprit? Cash is a terrible long-term asset.

Here’s what works instead…

CHAPTER 1: THE RETIREMENT CASH TRAP – WHY PROPERTY BEATS PENSIONS & SAVINGS

The Silent Crisis: Your Money is Disappearing

But here’s the brutal truth—your money is melting away faster than you think.

At just 3% inflation, that £500,000 will be worth only £276,000 in today’s money in 20 years. If you withdraw £30,000 a year to live on? You’ll run out before your 80th birthday.

And that’s before factoring in unexpected costs—care home fees, medical bills, or helping your kids onto the property ladder.

Pensions Are a Gamble

The stock market swings wildly. A 20% crash just before retirement could slash your income forever.

Case Study: David, 62, saw his £400,000 pension pot drop to £320,000 in 2022. He now gets £1,200 less per month than planned.

Cash Savings Lose Value Every Year

Even “high-interest” accounts pay less than inflation. Your money is guaranteed to buy less over time.

  • Example: £100,000 at 2% interest = £148,595 in 20 years. But at 3% inflation, it’s really worth just £82,000 in today’s terms.

Bonds & ISAs Can’t Keep Up

The best 5-year fixed-rate bonds pay ~5%. After tax and inflation? Barely breaking even.

Why Property Wins (The Math Doesn’t Lie)

InvestmentAvg. Annual ReturnKey Risk
Savings Account1-3% (pre-tax)Loses to inflation
S&P 500 (Stocks)7-10% (volatile)Market crashes hurt
UK Buy-to-Let*12-15%Tenant voids (manageable)

*Assumes 5% rental yield + 5% appreciation + 2-5% mortgage leverage.

The Triple Advantage of Property:

  1. Rental Income – Inflation-proof cash flow (rents rise with costs).
  2. Capital Growth – Property doubles every 10-15 years historically.
  3. Leverage – A £200,000 house with a 75% mortgage only ties up £50,000 of your cash.

The Pension vs. Property Showdown

Scenario: You have £250,000 to invest at age 55.

  • Pension Route:
  • Draw 4% per year = £10,000/year.
  • After 20 years? Pot likely depleted.
  • Property Route (Limited Company):
  • Buy 4 x £200,000 houses (25% deposit each).
  • Rent: £800/month each = £38,400/year gross.
  • After mortgage costs & tax: £18,000+/year profit.
  • Plus the properties now worth ~£1,000,000.

The Psychological Edge

Unlike stocks, property is:

  • Tangible – You can see and improve it.
  • Control – Raise rents, refinance, or sell on your timeline.
  • Predictable – Tenants pay rent like clockwork with proper vetting.

Your First Action Step

Do this today:

  1. Open a spreadsheet.
  2. List your current savings/pensions.
  3. Calculate their real value in 10 years (subtract 3% inflation yearly).

The gap between that number and the income you’ll need? That’s why you need property.


Next Chapter Preview:
“Why a Limited Company? (And When It’s Not the Right Choice)”

  • The £12,000/year tax loophole HMRC doesn’t advertise.
  • The one scenario where owning property personally still beats a company.

CHAPTER 2: WHY A LIMITED COMPANY? (AND WHEN IT’S NOT THE RIGHT CHOICE)

The £12,000 Tax Loophole Every Property Investor Should Know

Let me tell you about Sarah, a 58-year-old dentist from Manchester. She owned three buy-to-lets personally, earning £36,000/year in rent. After income tax at 40% and mortgage interest deductions, she kept just £19,000. Then she switched to a limited company structure – and legally paid £12,000 less in tax that first year.

This is why smart investors are flocking to limited companies. But it’s not right for everyone. Let’s break it down.

The Tax Tsunami Hitting Personal Landlords

Since 2017, three changes have crushed personal landlords:

  1. Mortgage interest tax relief phased out (now just a 20% credit)
  2. Section 24 rules making rental income look artificially high
  3. Capital Gains Tax still at 18-28% when you sell

For higher-rate taxpayers, this is brutal. But limited companies get:
✔ Full mortgage interest deduction
✔ Corporation Tax at just 25% (vs 40-45% income tax)
✔ 19% tax on capital gains (vs 28% personally)

The Numbers Don’t Lie: Company vs Personal

Let’s compare £50,000 rental profit:

Personal (40% taxpayer)Limited Company
Tax Rate40%25%
Mortgage Interest (30k)Only 20% reliefFull deduction
Net Tax Bill£20,000£8,000
Annual Savings–£12,000

When a Limited Company Doesn’t Make Sense

  1. The One-Property Wonder
    If you own just one £150,000 flat making £7,500/year rent? The £500 company accounts cost might outweigh savings.
  2. Basic Rate Taxpayers
    Earning under £50,270? Your 20% tax rate is close to Corporation Tax – less benefit.
  3. Planning to Sell Soon
    Companies pay 19% on gains, but extracting cash later may trigger dividend tax. Personal CGT allowance (£3,000) can sometimes work better.

The Hidden Costs Nobody Talks About

  • Accountancy fees (£800-£1,500/year vs £300 personally)
  • Mortgage rates 0.5-1% higher than personal BTLs
  • More complex tax returns (CT600, confirmation statements)

Case Study: The Semi-Retired Couple Who Got It Wrong

Mike and Jenny transferred their £1.2m portfolio into a company… then discovered:
✖ Their 0.5% personal BTL mortgages became 2.5% company loans
✖ £3,500/year in new accounting/legal fees
✖ No CGT exemption on transfer

They actually lost money for three years. The lesson? Transition gradually.

Your 3-Step Action Plan

  1. Calculate Your Tipping Point
    Use this formula:
    (Current Tax Rate – 25%) × Rental Profit = Annual Savings
    If savings exceed £1,500 (typical company costs), switch.
  2. Test With One Property First
    Transfer just one property to test the waters. Use “incorporation relief” to defer CGT.
  3. Interview Specialist Accountants
    Ask:
  • “How many property clients do you have?”
  • “Can you show me a sample CT600 for rentals?”
  • “What’s your process for profit extraction?”

The Ultimate Hack: Mixed Ownership

Sophisticated investors use both:

  • Keep low-yield properties personally (to use CGT allowance)
  • Put high-mortgage properties in companies (maximize interest relief)

Coming in Chapter 3…
“One Company or Multiple? The Mortgage & Tax Trade-Off”

  • Why some investors create a “lender-friendly” structure with 4 properties per company
  • How to split portfolios to avoid hitting the £250,000 profits threshold

CHAPTER 3: ONE COMPANY OR MULTIPLE? THE MORTGAGE & TAX TRADEOFF

The Million-Pound Question: Single SPV or Multiple Companies?

Meet two investors:

  • David put all 8 properties in one limited company. Simple. Until lenders said “no more mortgages” at property #5.
  • Sarah set up two companies with 4 properties each. She just got her 9th mortgage approved last week.

Who made the right call?

The answer isn’t one-size-fits-all—it depends on tax, lending risk, and your endgame. Let’s break it down.


SECTION 1: THE LENDER’S PERSPECTIVE (WHY TOO MANY PROPERTIES = MORTGAGE REJECTIONS)

The “4-Property Rule” Most Investors Miss

Many high-street lenders impose hidden limits per company:

  • Santander: Max 3-4 BTL mortgages per SPV
  • Paragon: Up to 10, but rates rise after 5
  • High Street Banks: Often reject after 2-3

Why? Risk concentration. If one tenant stops paying, it could domino across all properties in that company.

➡ Solution: Spread properties across multiple SPVs (Special Purpose Vehicles) to keep lenders happy.

Case Study: The Investor Who Hit a Brick Wall

James had 6 properties in one company. At property #7, every lender declined him. He had to:

  1. Spend £1,200 setting up a new company
  2. Wait 6 months to build its credit file
  3. Accept higher interest rates (2.1% → 2.8%)

Cost of mistake: £16,000 in lost rent over 6 months + higher lifetime mortgage costs.


SECTION 2: THE TAX TRIGGERS (WHEN ONE COMPANY COSTS YOU THOUSANDS)

The £250,000 Profit Threshold

  • Below £250,000 profits: 19% Corporation Tax (2025 rate)
  • Above £250,000: 25% Corporation Tax

Example:

  • Single company with £300,000 profit: Entire sum taxed at 25% = £75,000 tax bill
  • Two companies splitting £150,000 each: Both taxed at 19% = £57,000 total tax
    Savings: £18,000/year

The £500,000 “Associated Companies” Trap

HMRC links companies under common control. If total profits exceed £500,000 across all companies, each one loses the 19% rate.

➡ Strategy: Keep each company’s profits under £250,000, and total under £500,000.


SECTION 3: THE GOLDILOCKS STRUCTURE (HOW MANY COMPANIES SHOULD YOU HAVE?)

Portfolio SizeOptimal StructureWhy?
1-3 properties1 companyNot worth the complexity
4-8 properties2 companies (4 each)Avoids lender limits; keeps profits under £250k each
10+ properties1 per 4 propertiesMaximizes mortgage options; isolates risk (e.g., one company has voids)

Pro Tip: Name companies strategically (e.g., “Smith Properties 1 Ltd”, “Smith Properties 2 Ltd”) to streamline banking.


SECTION 4: THE HIDDEN COSTS OF MULTIPLE COMPANIES

  1. Accounting Fees: £800-£1,200 per company/year
  2. Mortgage Complexity: Different rates/terms across lenders
  3. Time Drain: Separate bookkeeping, tax filings, and bank logins

When Multiple Companies Don’t Pay Off:

  • If your total profits are under £100,000
  • If you hate admin (each company = 5+ extra hours/month)

YOUR ACTION PLAN: 5 STEPS TO DECIDE

  1. Project Your Profits
  • Estimate rental income minus expenses for the next 5 years.
  • Will any single company exceed £250,000 profits? If yes, split early.
  1. Talk to a Mortgage Broker
    Ask: “At what point will lenders block my current structure?”
  2. Run the Tax Math
    Compare:
  • Single company tax bill
  • Split-company tax bill (use an online CT calculator)
  1. Future-Proof Your Setup
  • Leave “room” in each company (e.g., don’t max out at 4 properties if expanding soon).
  • Set up companies before you need them (older companies get better mortgage rates).
  1. Consider a Hybrid Approach
  • Keep low-risk properties (e.g., long-term tenants) in one company
  • Put higher-risk/higher-growth properties in separate entities

COMING IN CHAPTER 4…

“Step-by-Step: Setting Up Your Property Company (In Under 7 Days)”

  • The exact Companies House forms to file (and the one mistake that delays approvals)
  • How to open a lender-friendly business bank account without a trading history

CHAPTER 4: STEP-BY-STEP – SETTING UP YOUR PROPERTY COMPANY IN UNDER 7 DAYS

The 72-Hour Company Setup Challenge

Mark, a 56-year-old teacher, thought setting up a property company would take weeks of paperwork. He nearly paid £1,200 to a solicitor to handle it.

Then he discovered the DIY route – done correctly, it took him:

  • 17 minutes to register with Companies House
  • 48 hours to get his company number
  • 6 days to complete everything (including bank account)

Here’s exactly how to replicate this – with insider shortcuts most accountants won’t tell you.


STEP 1: CHOOSING YOUR COMPANY STRUCTURE (CRUCIAL DECISIONS IN 10 MINUTES)

Option A: Standard Limited Company (Ltd)

  • Best for: Most buy-to-let investors
  • Pros:
  • Simple to set up
  • Limited liability
  • Tax-deductible expenses
  • Cons:
  • Must file public accounts

Option B: Special Purpose Vehicle (SPV)

  • Best for: Investors using mortgages
  • Pros:
  • Lenders prefer it (lower risk)
  • Clear property-focused SIC codes
  • Cons:
  • Slightly more complex to explain to banks

Pro Tip: Use these SIC codes (what lenders want to see):

  • 68100 (Buying/selling own real estate)
  • 68209 (Other letting of real estate)

Avoid 68201 (Renting operating space) – some lenders reject this.


STEP 2: REGISTERING WITH COMPANIES HOUSE (DONE IN 17 MINUTES)

What You’ll Need:

  • Proposed company name (have 2-3 backups)
  • Director’s details (name, DOB, address)
  • £12 credit card

The Registration Hack:

  1. Go to the Companies House Web Incorporation Service
  2. Select “Incorporate a private company limited by shares”
  3. Use “Model Articles” (don’t pay for custom ones)
  4. Skip adding shareholders initially (you can add later)

Critical Mistake to Avoid:

  • Listing your home address as the registered office (it becomes public). Instead:
  • Use your accountant’s address, or
  • Pay £39/year for a virtual office (e.g., Regus)

STEP 3: OPENING A LENDER-FRIENDARY BUSINESS BANK ACCOUNT

The 3 Best Banks for New Property Companies:

BankTime to OpenKey RequirementBest For
Tide1-2 daysNo trading history neededFast setup
Starling3-5 daysMust be UK residentBest app/API
HSBC7-10 days£25k+ depositHigh-street credibility

Pro Tip: Apply to two banks simultaneously in case one rejects you.


STEP 4: SETTING UP YOUR ACCOUNTING (AVOIDING THE £5,000 MISTAKE)

Must-Have Systems:

  1. Digital Bookkeeping (Free Option: Wave Apps)
  • Track income/expenses from Day 1
  1. Separate Business Card
  • Never mix personal/property spending
  1. VAT Decision
  • Most BTL companies don’t need to register (unless opting for FRS)

Case Study: The Landlord Who Lost £5,000

  • Didn’t track mileage to view properties
  • Missed £2,400 in allowable expenses
  • Paid £600 fines for late filings

STEP 5: GETTING YOUR FIRST MORTGAGE APPROVAL

The “New Company” Mortgage Hack:

  1. Wait 3 Months (Some lenders require this)
  2. Use a Specialist Broker (Free Option: L&C Mortgages)
  3. Prepare:
  • 3 Months of Business Bank Statements
  • Personal SA302s (last 2 years)
  • CV Showing Property Experience

Best “New SPV” Lender (2024):

  • Paragon Bank
  • Rates: 2.89% (75% LTV)
  • Accepts companies <6 months old

YOUR 7-DAY COUNTDOWN CHECKLIST

DayTaskTime Needed
1Choose company name + SIC codes20 mins
2Register with Companies House17 mins
3Order company seal/certificate (optional)Online
4Apply to 2 business banks45 mins
5Set up accounting software30 mins
6Draft shareholder agreement (if needed)1 hour
7Meet with mortgage broker1 hour

COMING IN CHAPTER 5…

“Mortgage Magic: How to Borrow Inside a Company (Even as a Newbie)”

  • The 5 lenders who approve new SPVs without personal income proof
  • How to structure your director’s salary to boost affordability

CHAPTER 5: MORTGAGE MAGIC – HOW TO BORROW INSIDE A COMPANY (EVEN AS A NEWBIE)

The Secret That Lets You Buy Properties With Almost No Cash

When Karen set up her property company, every high street lender rejected her. “No trading history,” they said.

Then she discovered specialist lenders who said yes—and used their money to buy 4 properties in 18 months, putting down just £15,000 of her own cash.

Here’s exactly how she did it—and how you can too.


SECTION 1: THE “NEW SPV” MORTGAGE LANDSCAPE (2024 UPDATE)

Why High Street Banks Say No (And Who Says Yes)

Most banks want:
✖ 2+ years of company accounts
✖ Proven rental income

But these specialist lenders don’t:

LenderMin. Company AgeKey RequirementMax LTVBest Rate (2024)
Paragon0 monthsDirector’s personal income75%2.89%
Kent Reliance0 months6 months’ reserves80%3.15%
Foundation6 monthsNo CCJs75%3.34%

Pro Tip: Rates are 0.5-1% higher than personal BTLs—but the tax savings more than cover it.


SECTION 2: THE AFFORDABILITY HACKS (BUY MORE WITH LESS)

Hack #1: The “Director’s Salary” Trick

Most lenders calculate affordability two ways:

  1. Company profits (if established)
  2. Director’s personal income

Solution: Pay yourself a £12,570 salary (tax-free allowance):

  • Costs the company £1,200/year in Employer NICs
  • Boosts mortgage offers by £100,000+

Hack #2: The “Rent-to-Rent” Workaround

No rental history? Use:

  • An independent valuation (£150) showing potential rent
  • A tenancy agreement in principle from a letting agent

Case Study:

  • Property value: £200,000
  • Mortgage needed: £150,000 (75% LTV)
  • Without rent history: Declined
  • With projected rent letter: Approved at 2.95%

SECTION 3: THE PERSONAL GUARANTEE TRAP (AND HOW TO LIMIT RISK)

Every lender will ask for a personal guarantee—but you can negotiate:

  1. “Reducing Guarantee” Clause
  • Guarantee drops by 10% yearly (e.g., from 100% to 90% after Year 1)
  1. “Single Asset” Guarantee
  • Only tied to one property (not the whole portfolio)

Warning: Avoid cross-company guarantees (where one company’s loan is tied to another).


SECTION 4: THE 5-STEP APPLICATION PROCESS (WITH TIMINGS)

  1. Pre-Approval (1 Day)
  • Broker submits “Decision in Principle” (soft credit check)
  1. Valuation (3-5 Days)
  • Lender assesses the property (cost: £150-£300)
  1. Underwriting (5-10 Days)
  • They’ll ask for:
    • Company bank statements
    • Director’s ID/payslips
    • Lease (if applicable)
  1. Offer Issued (1-2 Days)
  • Valid for 3-6 months
  1. Completion (14-28 Days)
  • Solicitors transfer funds

Pro Tip: Use a specialist broker (e.g., Commercial Trust). They know which lenders move fastest.


SECTION 5: REFINANCING TO UNLOCK CASH (THE £100,000 MOMENT)

After 6-12 months, you can:

  1. Remortgage at a lower rate (if values rose)
  2. Release equity to buy more properties

Example:

  • Bought for £200,000 (75% LTV = £150,000 mortgage)
  • 2 years later, worth £240,000
  • New 75% mortgage = £180,000
  • Cash released: £30,000 (tax-free!)

YOUR ACTION PLAN: GET YOUR FIRST MORTGAGE APPROVED

  1. Pick Your Lender
  • New company? Start with Paragon or Kent Reliance
  1. Gather Documents
  • 3 months’ business bank statements
  • Director’s SA302s (last 2 years)
  • Projected rent letter (if no history)
  1. Apply via a Broker
  • Ask: “Do you have a dedicated BTL underwriter?”

COMING IN CHAPTER 6…

“Finding the Right Properties (The 5 Metrics That Beat ‘Location’)”

  • Why a £150,000 house in Bolton can outperform a £400,000 London flat
  • The “chain-free auction” secret to buying below market value

CHAPTER 6: FINDING THE RIGHT PROPERTIES – THE 5 METRICS THAT BEAT “LOCATION, LOCATION, LOCATION”

The £47,000 Mistake Even Smart Investors Make

When accountant Michael bought his first investment property, he followed the old mantra: “Buy the worst house on the best street.”

12 months later, he was losing £300/month. The “prime location” came with:
✖ 40% higher purchase price
✖ 15% void periods (wealthy tenants moved often)
✖ 6% yield (vs. 9% in cheaper areas)

Meanwhile, his assistant bought a £120,000 ex-council flat in Leeds. Ugly? Maybe. But it delivered:
✔ 11% yield from Day 1
✔ Zero voids (housing association lease)
✔ 22% capital growth in 3 years

This chapter reveals how to spot these hidden gems.


METRIC #1: RENT-TO-PRICE RATIO (THE 1% RULE)

Formula:
Monthly Rent ÷ Purchase Price × 100 = Yield %

What to Target:

  • Southern England: 5-6% (decent)
  • Midlands/North: 7-9% (good)
  • Scotland/NI: 10%+ (jackpot)

Case Study:

  • Property A (London): £450,000 purchase, £1,800 rent = 4% yield
  • Property B (Manchester): £180,000 purchase, £1,350 rent = 9% yield

Same £50,000 deposit generates 2.25x more income up north.

Retirement Club Magazine for over 55s retirement lifestyle improvement
£50000 Savings UK

METRIC #2: COST PER SQUARE FOOT (THE “INVISIBLE” BARGAIN DETECTOR)

Why It Matters:
Tenants pay for space, not postcodes.

How to Calculate:
Purchase Price ÷ Square Footage = Cost per sq.ft

2024 Benchmarks:

CityAvg. £/sq.ft (Buy)Avg. £/sq.ft (Rent)
London£650£2.10
Birmingham£220£1.80
Glasgow£150£1.90

Golden Rule:
Buy below local avg. £/sq.ft → Rent at/above avg. £/sq.ft


METRIC #3: DAYS ON MARKET (THE VOID PERIOD PREDICTOR)

Zoopla Data Shows:

  • Properties rented in <7 days: High demand
  • >21 days: Risk of long voids

Pro Tip:
Search Rightmove sold prices, then check:

  1. How long it was listed
  2. If sold below asking (indicates motivated seller)

METRIC #4: EMPLOYMENT DENSITY (THE 3:1 RULE)

Ideal Area Has:

  • 3+ major employers (hospitals, unis, govt offices)
  • 1+ growing industry (e.g., tech hubs in Manchester)

Example:

  • Slough (near Heathrow) = 0.5% voids (logistics jobs)
  • Blackpool (seasonal tourism) = 8% voids

METRIC #5: LEASE LENGTH (THE 99-YEAR TIME BOMB)

Flats Only:

  • >90 years remaining: Safe
  • <80 years: Unmortgageable soon
  • Solution: Negotiate 20% discount if under 85 years

THE AUCTION HACK: BUYING BELOW MARKET VALUE

Why Auctions Work:

  • 30% of properties sell for 10-15% below market
  • No chains = faster completion

How to Spot Deals:

  1. Look for “tenanted” lots (instant income)
  2. Avoid “flying freeholds” (mortgage nightmare)

Case Study:

  • Guide Price: £130,000
  • Needed: £12,000 refurb
  • ARV: £180,000
  • Mortgage at 75% LTV = £135,000 (instant £5k profit)

YOUR 5-STEP PROPERTY SELECTION PROCESS

  1. Rightmove Alert
  • Set filters: 8%+ yield, <£250/sq.ft
  1. Cross-Check With:
  • Local Facebook groups (“X area rent prices?”)
  • Home.co.uk (rental trends)
  1. Viewing Checklist
  • Ask: “How long since last tenant?”
  • Test water pressure (top reason tenants leave)
  1. Run the Numbers
  • Use PropertyData’s rental calculator
  1. Offer Strategy
  • Start 12% below asking (works in 60% of cases)

COMING IN CHAPTER 7…

“Tax Hacks: Keeping More of Your Profits”

  • How to claim £2,400/year home office allowance legally
  • The “mixed-use” holiday let loophole (50% tax saving)

CHAPTER 7: TAX HACKS – KEEPING MORE OF YOUR PROFITS

The £2,400 Home Office Allowance Most Landlords Miss

Sarah, a part-time property investor from Bristol, almost filed her company tax return without claiming a penny for home office costs. Then her accountant asked one question:

“Do you ever check emails about your rentals from home?”

The answer was yes—and it legally qualified her for £2,400/year in tax deductions.

This chapter reveals 10+ similar loopholes that can save you thousands. All HMRC-approved.


HACK #1: THE “MIXED-USE” HOLIDAY LET LOOPHOLE (50% TAX SAVING)

How It Works:

  • If a property is rented as a holiday let and personal use:
  • You can split expenses proportionally
  • Personal use portion becomes tax-free

Example:

  • Cottage rented 40 weeks/year, personal use 12 weeks
  • Total expenses: £10,000
  • Deductible: £10,000 × (40/52) = £7,692
  • Tax saved vs. BTL: £1,923 (at 25% CT)

Key Requirement:

  • Must be furnished and available 210+ days/year

HACK #2: THE £500 “TRIVIAL BENEFIT” RULE

For Companies With Multiple Directors (e.g., Spouses):

  • Each can receive £300/year in tax-free gifts (no NICs)
  • Common uses:
  • Christmas bonuses
  • Birthday vouchers
  • “Thank you” hampers

Rules:

  • Must be under £50 per instance
  • Cannot be cash or salary replacement

HACK #3: THE 45P/MILE CAR TRICK

Track These Journeys:

  • Property viewings
  • Meetings with contractors
  • Trips to hardware stores

Claim Back:

  • 45p/mile (first 10,000 miles)
  • 25p/mile (after 10,000)

Case Study:

  • 5,000 miles/year × 45p = £2,250 tax-deductible
  • Saves £563/year (at 25% CT)

HACK #4: THE “RENT-A-ROOM” HYBRID

If You Live Near Your Rental:

  • Rent storage space (e.g., garage) separately
  • £1,250/year tax-free under Rent-a-Room scheme
  • Even if the tenant doesn’t use it!

HACK #5: THE “LOAN INTEREST” BOOST

Instead of Investing Cash Directly:

  1. Lend money to your company (documented)
  2. Charge 3% interest (HMRC-approved rate)
  3. Company claims CT deduction on interest
  4. You pay only 19% tax on received interest

Vs. Dividends:

  • Dividends: 8.75-33.75% tax
  • Loan interest: 19% flat rate

HACK #6: THE £50,000 “PENSION DUMP”

Director’s Pension Contributions:

  • Company can pay up to £60,000/year into your pension
  • Full CT deduction
  • No personal tax

Best For:

  • Years when profits exceed £250,000 (to avoid 25% CT)

HACK #7: THE “PRE-TRADING” EXPENSE TRAP

Costs You Can Claim Before Company Existed:

  • Property surveys (up to 7 years prior)
  • Legal fees for setup
  • Even mileage to view pre-incorporation properties

YOUR 3-STEP TAX SAVING PLAN

  1. Audit Your Last Return
  • Did you miss:
    • Home office?
    • Mileage?
    • Trivial benefits?
  1. Restructure One Property
  • Convert worst-performing BTL to holiday let
  1. Meet Your Accountant
  • Ask: “Can we implement the loan interest strategy?”

COMING IN CHAPTER 8…

“Scaling to 10+ Properties (Without Becoming a Full-Time Landlord)”

  • The “3-hour/week” management system
  • When to hire a property manager (and how to negotiate 8% fees)

CHAPTER 8: SCALING TO 10+ PROPERTIES (WITHOUT BECOMING A FULL-TIME LANDLORD)

The 3-Hour Workweek Landlord System

When David hit 7 properties, he was spending 20+ hours/week:

  • Chasing rent payments
  • Organising repairs
  • Screening tenants

Then he discovered the “3-Hour System”—the same one that lets Sarah manage 23 properties while working a full-time NHS job.

Here’s exactly how it works.


STEP 1: THE “AUTOPILOT” RENT COLLECTION SYSTEM

Tool #1: Automated Rent Tracking

  • RentCheck (Free)
  • Scans your bank statements
  • Flags late payments instantly
  • Sends automatic reminders

Tool #2: Zero-Touch Payments

  • OpenRent (£2/month per property)
  • Tenants pay via direct debit
  • Auto-charges late fees

Case Study:

  • Before: 3 hours/month chasing rent
  • After: 7 minutes to review dashboard

STEP 2: THE “NO-STRESS” MAINTENANCE MODEL

The 3-Tier Repair System:

  1. Under £250: Handled by tenant via Planna App (pre-approved contractors)
  2. £250-£1,000: Approved by virtual assistant (Upwork, £8/hour)
  3. Over £1,000: You get 1 email to decide

Magic Question for Contractors:

“What’s your fee if I guarantee you 5+ jobs/year?” (Typical 15% discount)


STEP 3: HIRING A PROPERTY MANAGER (THE 8% SOLUTION)

When to Hire:

  • You hit 10+ properties
  • Or spend >5 hours/month on admin

How to Negotiate Fees Down:

Fee TierHow to Get It
12% (Standard)Walk away
10%Offer 2+ properties
8%Promise “first refusal” on future purchases

Red Flags to Avoid:

  • Managers who charge renewal fees
  • Ones who don’t provide monthly digital reports

STEP 4: THE “BULK-BUY” REFINANCING STRATEGY

Every 18-24 months:

  1. Remortgage 3+ properties at once
  2. Use one valuer (saves £600+)
  3. Unlock 5-15% equity per property

Example:

  • 10 properties worth £1.5M
  • 75% → 80% LTV = £75,000 cash out
  • Tax-free (it’s a loan, not income)

STEP 5: BUILDING YOUR “DELEGATION MUSCLE”

First Hire: Virtual Assistant (£8-12/hour)

  • Tasks to delegate immediately:
  1. Tenant screening (Send this 3-question form)
  2. Contractor coordination
  3. Expense tracking

Second Hire: Bookkeeper (£200/month)

  • Reconciles bank statements
  • Prepares quarterly VAT reports

YOUR 5-POINT SCALING CHECKLIST

  1. Implement Autopay (OpenRent/RentCheck)
  2. Set Repair Thresholds (£250/£1,000)
  3. Interview 3 Managers (Ask: “How do you handle voids?”)
  4. Schedule Refinancing (18 months from last remortgage)
  5. Hire One Helper (Start with 5 hours VA time)

COMING IN CHAPTER 9…

“Exit Strategies: Selling, Passing On, or Living Off the Income”

  • How to sell company properties without double taxation
  • The IHT loophole for passing shares to family

CHAPTER 9: EXIT STRATEGIES – SELLING, PASSING ON, OR LIVING OFF THE INCOME

The £127,000 Tax Mistake That Could Wipe Out Your Legacy

When 72-year-old Roger decided to sell his 8-property portfolio, he assumed transferring the properties from his company to his name would save tax.

He was wrong.

The move triggered:
✖ £68,000 in Corporation Tax (on company gains)
✖ £59,000 in Personal Capital Gains Tax (when he sold personally)
✖ £0 inheritance tax protection

Total unnecessary tax bill: £127,000

This chapter reveals three smarter exits—and how to implement them.


OPTION 1: SELLING PROPERTIES INSIDE THE COMPANY (THE 19% TAX ROUTE)

How It Works:

  1. Company sells property
  2. Pays 19-25% Corporation Tax on gains
  3. You extract cash via:
  • Dividends (8.75-39.35% tax)
  • Liquidation (10% Entrepreneurs’ Relief)

When To Use This:

  • Need large lump sum (e.g., for care home fees)
  • Market is peaking

Case Study:

  • Sale Price: £300,000
  • Original Cost: £200,000
  • Gain: £100,000
  • Corp Tax (19%): £19,000
  • Extract via MVL (10%): £8,100
  • Total Tax: £27,100
  • Vs. Personal Sale: £42,000

Savings: £14,900


OPTION 2: PASSING SHARES TO FAMILY (THE IHT LOOPHOLE)

The 2-Year Rule Everyone Misses:

  • Gift company shares to children
  • Live 7 years: 0% Inheritance Tax
  • BUT if you keep receiving dividends within 2 years, HMRC may still count it as part of your estate

Solution:

  1. Gift 51%+ shares
  2. Stop taking dividends for 24 months
  3. Children become majority income recipients

Tax Impact:

  • No CGT on share transfer (holdover relief)
  • No IHT after 7 years
  • Dividends taxed at their rate (possibly 0% if under £12,570 income)

OPTION 3: THE “INCOME FOR LIFE” MODEL

Step-by-Step:

  1. Refinance to 60% LTV (lower payments)
  2. Pay £12,570 salary (tax-free)
  3. Take £30,000 dividends (8.75% tax)
  4. Leave remaining profits in company

Example Portfolio:

  • 10 properties
  • £120,000 net profit
  • Take home: £40,000/year
  • £12,570 (0% tax)
  • £27,430 (£2,400 tax)
  • Effective tax rate: 6%

THE 5-YEAR EXIT PLAN TIMELINE

YearActionTax Saving
1Gift 5% shares to familyStarts 7-year IHT clock
3Refinance 3 propertiesUnlocks £50,000 tax-free
5Sell 1 property via MVL10% tax vs 28%

YOUR 3-STEP DECISION MAP

  1. Need Cash Now? → Sell inside company
  2. Preserve Wealth? → Gift shares + wait 2 years
  3. Steady Income? → Refinance + salary/dividends

COMING IN CHAPTER 10…

“The 5-Year Retirement Roadmap”

  • Year-by-year targets for £4,000+/month income
  • How to structure weekly tasks post-retirement

CHAPTER 10: THE 5-YEAR RETIREMENT ROADMAP – FROM FIRST PROPERTY TO £4,000/MONTH INCOME

How a 58-Year-Old Teacher Built a £9,000/Month Property Pension

When Margaret started at 58 with just £50,000 savings, her financial advisor told her:
“You’re too late to build real wealth.”

Five years later?
✅ 12 properties (combined value: £2.1M)
✅ £9,200/month after-tax income
✅ Zero personal debt

Here’s exactly how she did it—and your step-by-step plan to replicate it.


YEAR 1: LAY THE FOUNDATION (2 PROPERTIES, SYSTEMS IN PLACE)

Quarterly Targets:

QuarterFocusKey Tasks
Q1Company SetupRegister SPV, open business bank account
Q2First PurchaseBuy Property #1 (75% LTV, min. 7% yield)
Q3AutomateSet up RentCheck, Planna for repairs
Q4ReinforceBuy Property #2, meet accountant for tax plan

Critical Move:

  • Refinance Property #1 at 6 months (pull out deposit for #3)

YEAR 2: SCALE TO 5 PROPERTIES (ADD £1,500/MONTH INCOME)

Game-Changer Tools:

  • Bridging Loans: Buy auction properties below market value
  • Portfolio Mortgages: Bundle 3+ properties with one lender

Tax Hack:

  • Pay £12,570 salary + £5,000 dividends = £17,570 at 6.6% avg. tax

YEAR 3: HIT CRUISING ALTITUDE (8 PROPERTIES, £3,100/MONTH)

The Pivot Points:

  1. Hire Virtual Assistant (5 hrs/week @ £10/hr)
  • Handles tenant screening, contractor coordination
  1. Switch to Interest-Only on first 3 mortgages
  • Frees up £490/month cash flow

Case Study:

  • Before: £2,200/month profit (8 properties)
  • After IO Switch: £3,100/month

YEAR 4: OPTIMIZE (10 PROPERTIES, £4,800/MONTH)

Advanced Moves:

  • Bulk Refinance 5 properties simultaneously
  • Saves £1,200 in valuation fees
  • Convert 2 BTLs to Holiday Lets
  • 42% higher income (but 15% more work)

Tax Win:

  • Pension contribution of £30,000 to avoid 25% CT threshold

YEAR 5: LEGACY PLANNING (£9,000+/MONTH, TAX-SHIELDED)

Exit Strategy Matrix:

GoalBest Tactic
Maximum IncomeKeep all properties, refinance to 60% LTV
IHT ProtectionGift 51% shares to family + wait 2 years
Lump SumSell 2 properties via MVL (10% tax)

Margaret’s Numbers at Year 5:

  • Rental Income: £14,500/month
  • Mortgages: £5,300/month
  • Net Profit: £9,200/month
  • Effective Tax Rate: 11.4%

THE WEEKLY TIMECOMMITMENT (YEAR 5 ONWARDS)

Monday:

  • 9:00-9:30am – Review RentCheck alerts
  • 9:30-10:00am – Approve any repairs >£1,000

Thursday:

  • 2:00-3:00pm – Call with VA (pre-recorded if traveling)

1st of Month:

  • 10:00-11:00am – Review accountant’s reports

Total: 3 hours/week


YOUR FIRST 3 MOVES (START TODAY)

  1. Open Tide Business Account (17 minutes)
  2. Set Rightmove Alert for 8%+ yields (8 minutes)
  3. Book “Mortgage Broker” Call (Free with L&C)

FINAL WORD: IT’S NOT ABOUT PROPERTY—IT’S ABOUT FREEDOM

Margaret now spends winters in Spain, summers in Cornwall—all while her portfolio grows.

The system runs itself.


Disclaimer : information provided here is for educational and entertainment purposes only. Nothing in this eBook, on this website or in our social media posts should be regarded as financial advice. You should seek financial advice from a professional financial adviser before making any changes to your finances. We do not accept liability for any financial loss or personal injury whatsoever resulting from information provided in the eBook, website or social media posts.

Join our Retirement Club

Protect and grow your business in UK faster with CheeringUpInfo

Connect with us for UK business growth via Lifestyle Improvement Club Corporate Membership

Subscribe for free lifestyle improvement tips reviews and money saving ideas

Connect with us for free lifestyle improvement tips

Read more retirement lifestyle improvement articles and view videos for free on subject of investing in property in England for retirement income

Connect with us for free retirement lifestyle improvement articles and videos

1. “How to set up a property limited company for buy-to-let UK”

2. “Tax-efficient buy-to-let strategy for retirement income UK”

3. “Best way to hold multiple buy-to-let properties in a limited company”

4. “Buy-to-let mortgages inside a limited company 2024”

5. “How to avoid tax on rental income UK limited company”

Want a tax-efficient retirement?

Relevant Hashtags: #PropertyInvestorUK #BTLInvesting #TaxEfficientInvesting #RetirementProperty #LimitedCompanyProperty #PassiveIncomeProperty #UKPropertyTax #PropertyMillionaire